Assessment Officer Cannot Reopen Assessment Finalised By Settlement Commission: SC
 Copy Link
 Share
 Save
In a major setback to the Revenue, the Supreme Court held that the Assessing Officer lacks statutory jurisdiction to reopen an assessment finalized by the Income Tax Settlement Commission under the guise of reassessment. The Apex Court affirmed that once a settlement order achieves finality, the statutory scheme under Chapter XIX-A permanently ousts parallel assessment machinery unless the order is annulled for fraud or misrepresentation by the Commission itself.
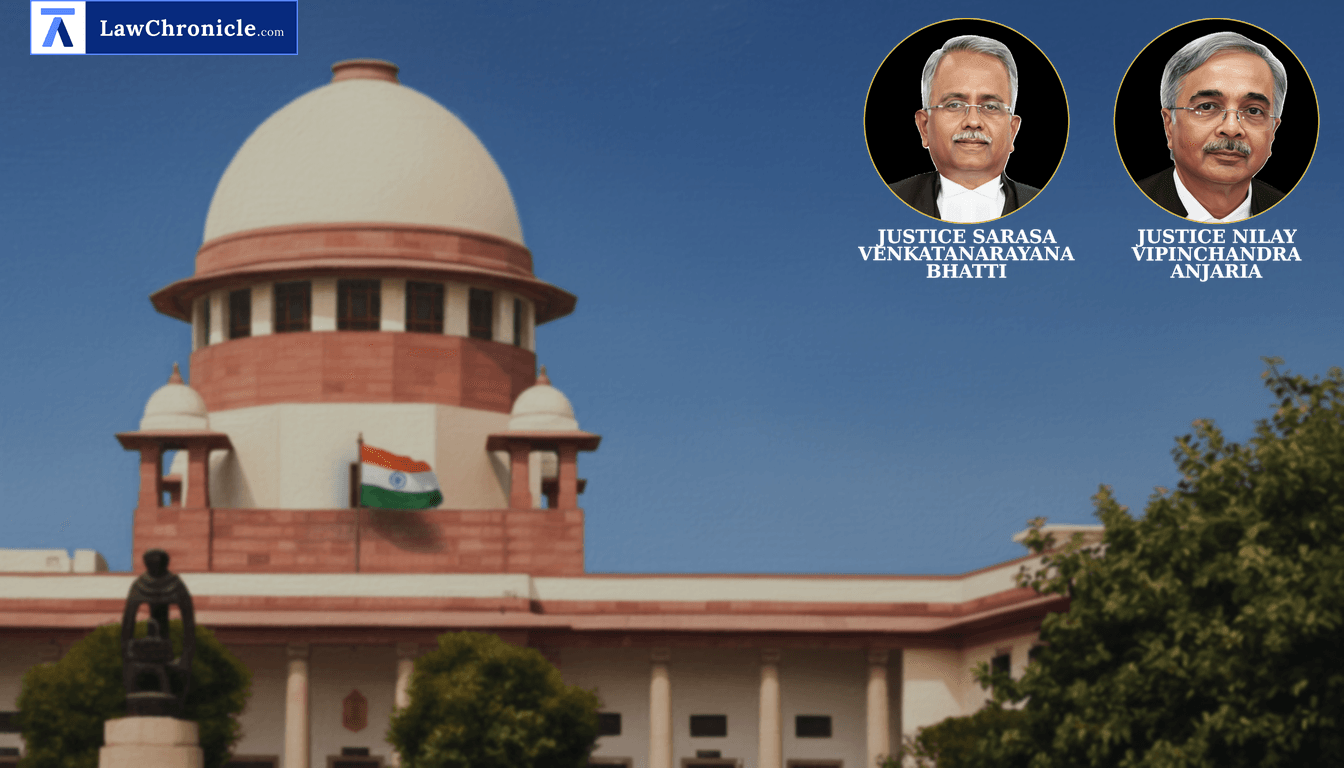
A bench of Justice S.V.N. Bhatti and Justice N. V. Anjaria dismissed the Revenue's appeal challenging a High Court ruling that quashed reassessment proceedings initiated against an assessee post-settlement. The Bench examined whether an Assessing Officer can invoke reassessment powers regarding matters already encompassed within a final settlement order.
Key Takeaways
Exclusive Jurisdiction Prevails: The Settlement Commission holds total administrative and adjudicatory control over admitted cases, completely barring parallel proceedings by lower tax authorities.
Reassessment Ousted: Assessing Officers cannot use reassessment provisions to circumvent final settlement orders or revisit claims implicit in the settled income.
Strict Remedy for Revenue: If the Revenue suspects suppression, its sole legal recourse is moving an application for annulment before the Settlement Commission on grounds of fraud or misrepresentation.
Self-Contained Statutory Scheme: The settlement mechanism acts as a binding alternate dispute resolution process where both tax authorities and assessees must accept the final statutory compromise.
Powers of Assessment Officer
The Supreme Court emphasized that allowing assessing authorities independent jurisdiction to reopen settled orders would undermine the statutory finality guaranteed by Parliament. The bench noted that the procedure under Chapter XIX-A functions as an integrated framework designed for final tax resolution. As expressed by the Apex Court, “Once the crust is avoided and the crumb is accepted, further crust and crumb are not the intention of Chapter XIX-A of the Act, 1961... If the jurisdiction of the AO under Sections 143(2), 148, 154, etc., is made independent and available for exercise again, the finality attached to the Settlement Commission will be defeated. Parliament did not envisage this course.” Addressing the interaction between statutory assessment and settlement finality, the Court noted that the Revenue cannot choose to reassess matters post-finality through regular channels.
Ratio
An order passed by the Income Tax Settlement Commission under Section 245D(4) of the Income Tax Act, 1961 is conclusive and binding. The Assessing Officer possesses no statutory jurisdiction under Section 147 or Section 148 to reopen or reassess matters covered by such a settlement order, except through an explicit declaration of invalidity passed by the Settlement Commission itself under Section 245D(6) on grounds of fraud or misrepresentation.
Background
The assessee, a public limited company in real estate, filed its income tax return for Assessment Year 2006-07 claiming deduction under Section 80IB(10) of the Income Tax Act, 1961. Following a search and seizure operation under Section 132 of the Income Tax Act, 1961, the company moved an application for settlement under Section 245C before the Income Tax Settlement Commission. On March 17, 2008, the Commission passed a final settlement order under Section 245D(4), computing the total taxable income after considering the statutory deductions.
Subsequent to a survey conducted under Section 133A of the Income Tax Act, 1961, the Revenue issued a notice under Section 148 seeking to reopen the assessment. The Assessing Officer alleged that commercial areas in housing projects exceeded statutory limits, disentitling the assessee to Section 80IB(10) benefits. The Revenue then passed a reassessment order disallowing the deduction. Parallelly, the Revenue's application under Section 245D(6) to declare the settlement void was rejected by the Commission.
The Delhi High Court quashed the notice and reassessment order, relying on Major Metals Ltd., W.P. No. 397 of 2011 and CIT v. Smt. Diksha Singh to hold that the Settlement Commission exercises exclusive jurisdiction once proceedings commence. Distinguishing CIT v. Damani Brothers, the High Court held that piecemeal assessment is impermissible and reinforced the principles laid out in Commissioner of Income Tax, madras v. Express Newspapers Ltd. and Jyotendrasinhji v. S.I. Tripathi & Ors. ( "(1993) Supp (3) SCC 389": 1993 CaseBase(SC) 343) regarding judicial review and statutory finality. Highlighting Brij Lal and Ors. v. CIT ( "(2011) 1 SCC 1": 2010 CaseBase(SC) 1517), the Supreme Court confirmed that Chapter XIX-A constitutes a self-contained code, rendering the Assessing Officer's reassessment without jurisdiction.
Case Details:
Case No.: CIVIL APPEAL NO. 9190 OF 2013
Neutral Citation: 2026 INSC 1000
Case Title: ASSISTANT COMMISSIONER OF INCOME TAX & ANOTHER v. M/S. OMAXE LIMITED
Appearances:
For the Petitioner(s): Mr. Arijit Prasad, Senior Counsel
For the Respondent(s): Ms. Kavita Jha, Senior Counsel
Source: 2026 CaseBase(SC) 7007
 Breaking News