Bombay HC Remits matter Back to ITAT for Missing Evidence on Record
 Copy Link
 Share
 Save
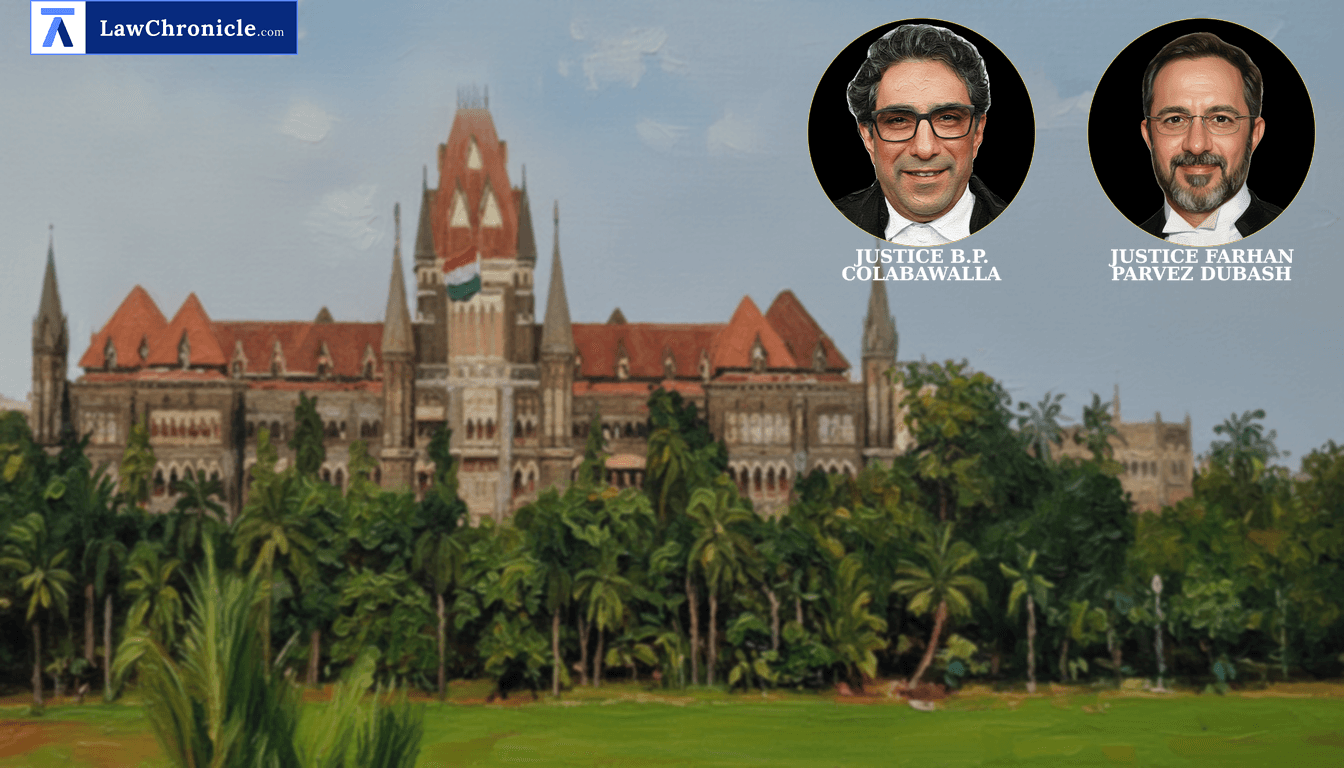
The Bombay High Court has reprimanded the Income Tax Appellate Tribunal for dismissing a rectification application based on a factual doubt regarding the filing of evidence, despite such evidence being present in the official records. A division bench comprising Justice B. P. Colabawalla and Justice Farhan P. Dubash heard the writ petition challenging an order passed under Section 254(2) of the Income Tax Act, 1961. The Petitioner sought to recall a previous common order on the grounds that certain paper books and an affidavit containing crucial evidence were inadvertently ignored by the Tribunal during the original appellate proceedings.
Key Takeaways
Judicial Duty to Verify Records
Tribunals cannot dismiss applications based on a mere doubt about whether documents were filed when those documents are physically present in the case file.
Substantial Compliance vs. Technicality
While procedural rules like Income Tax (Appellate Tribunal) Rules, 1963 must be followed, an affidavit seeking permission for additional evidence may be considered in the context of record verification even if a separate formal petition is missing.
Remand on Specific Factual Errors
High Courts will exercise writ jurisdiction to remit matters where a lower authority proceeds on an erroneous premise that contradicts the physical reality of the case record.
Tribunal's Observations on Missing Paper Books Quashed
The Bombay High Court noted that the Petitioner had provided evidence, including a chartered accountant's inspection report, confirming that the disputed Paper Book No. II-A and an accompanying affidavit were indeed part of the Tribunal's records. The Court found that the ITAT's doubt regarding the existence of these documents was unsustainable given their presence in the original record and proceedings.
The Court has following directions:
"Accordingly, the impugned order is partly set aside. Miscellaneous Application No. 275/Mum/2019 is remitted to the ITAT for a fresh consideration. While doing so, the ITAT shall only consider, in the first instance, whether Paper Book No. II-A was duly filed by the Petitioner in compliance with Rule 29 of the said Rules, having regard, inter alia, to the fact that the same was accompanied by the said affidavit. If the answer to the first issue is in the affirmative, then the ITAT shall consider whether the documents in Paper Book No. II-A were relevant for deciding the controversy in the Appeal filed by the Petitioner."
The Bombay High Court expressed that "Having considered the facts narrated earlier, we are prima facie satisfied that the said affidavit and the accompanying Paper Book No. II-A were filed by the Petitioner before the ITAT, and were on the file of the Tribunal. In such circumstances, the observations of the ITAT expressing doubt as to whether the said documents had ever been filed before it cannot, prima facie, be sustained."
Ratio
When a litigant claims that specific evidence or documents were filed and relies on them during arguments, a Tribunal's failure to consider those documents while simultaneously doubting their existence—despite their presence in the official record, constitutes an error apparent on the face of the record, necessitating a fresh adjudication.
Background
The dispute originated from an assessment for the Assessment Year 2010-11. Both the Revenue and the Petitioner filed appeals before the ITAT against an order of the CIT(A). During the proceedings, the Petitioner filed multiple paper books. In December 2018, the ITAT passed a common order, which the Petitioner claimed ignored Paper Book Nos. II and II-A.
The Petitioner subsequently filed Miscellaneous Applications under Section 254(2) of the Income Tax Act, 1961 to recall the order. The ITAT dismissed the application relating to the ignored evidence, questioning if the documents were ever filed because they were not accompanied by a formal petition under Rule 29 of the Income Tax (Appellate Tribunal) Rules, 1963. However, an inspection of the records by the Petitioner's representative confirmed the documents were in the ITAT’s possession. The Bombay High Court, while remitting the matter, clarified that while Paper Book No. II was rightly ignored due to a total lack of procedural compliance, Paper Book No. II-A required fresh consideration as it was accompanied by an affidavit seeking the requisite permission.
Case Details:
Case No.: WRIT PETITION NO. 2727 OF 2023
Neutral Citation: 2026:BHC-OS:20025-DB
Case Title: Crest Paper Mills Ltd. vs. Dy. CIT.
Appearances:
For the Petitioner(s): Mr. Ajay R Singh a/w Mr. Akshay A Pawar
For the Respondent(s): Mr. Suresh Kumar
Source: 2026 CaseBase(BOM) 5650
 Breaking News