Clearing Members Have No Obligation To Verify Client Balances Post-Default: SC
 Copy Link
 Share
 Save
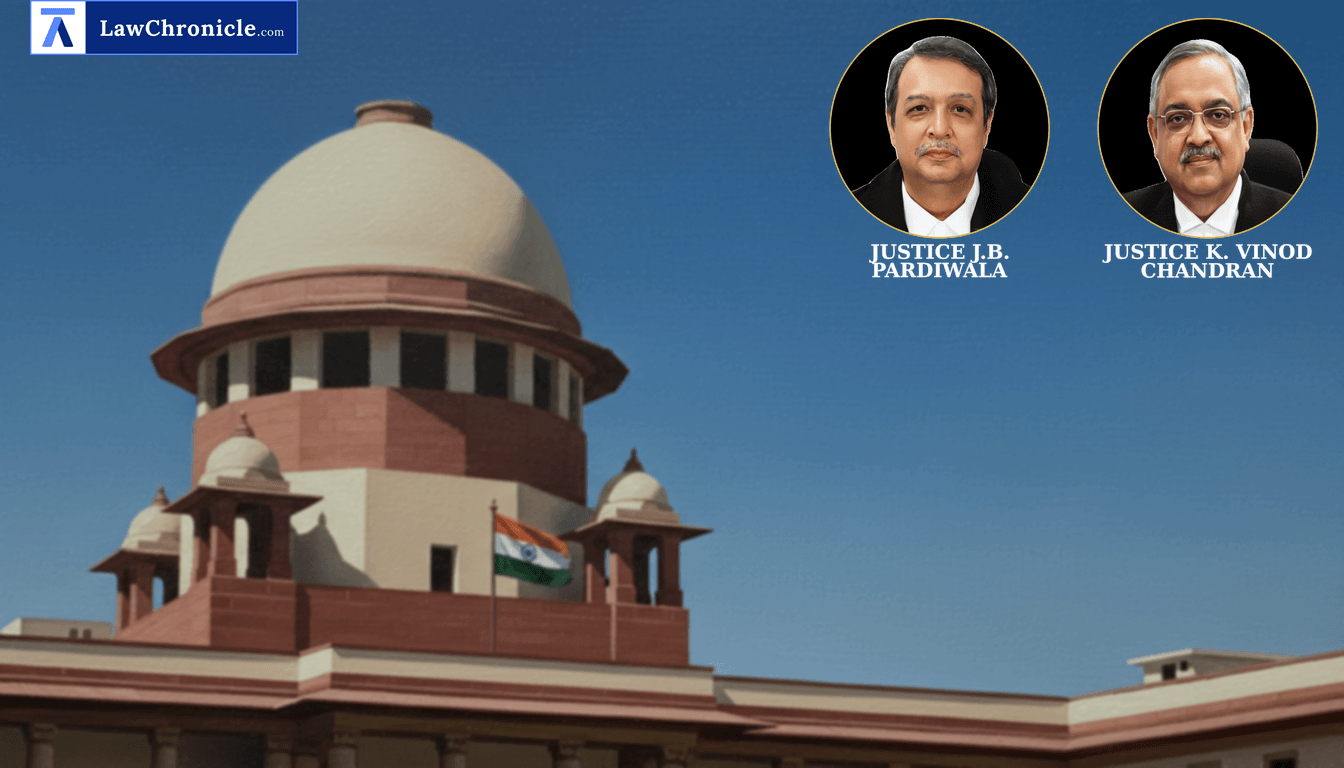
In a decisive verdict shielding Professional Clearing Members from sweeping financial liabilities, the Supreme Court ruled that clearing entities cannot be forced to pay monetary restitution for liquidated client collaterals prior to the introduction of daily segregation regimes. Dismantling key orders of market regulators, the apex court established that clearing members lacked both visibility of individual debit-credit positions and a statutory duty to inspect end-client accounts when executing default liquidations.
A bench of Justice J.B. Pardiwala and Justice K. Vinod Chandran set aside the directions issued by the Core Settlement Guarantee Fund Committee of the clearing corporation as well as the Securities Appellate Tribunal. The Court was considering a batch of appeals filed by Professional Clearing Members (PCMs) challenging orders that required them to restitute hundreds of crores worth of client securities liquidated following broker defaults in the Futures & Options (F&O) segment.
Key Takeaways
No Third-Party Duty: PCMs have no privity of contract with the individual clients of Trading Members and carry no duty to verify client-level balances prior to liquidating collaterals.
Restitution Power Barred: Stock exchange committees cannot pass monetary restitution or disgorgement orders under statutory byelaws governed by Section 9 of the Securities Contracts (Regulation) Act, 1956.
Regulatory Evolution Contextualized: Daily reporting and pledge-repledge mechanisms introduced by Securities and Exchange Board of India Act, 1992 in 2020 and 2021 cannot be applied retrospectively to penalize past liquidations.
Investor Risk Assumed: Retail investors entering unapproved assured-return schemes with stockbrokers cannot claim indemnification from clearing entities upon broker insolvency.
The Court delivered an extensive analysis on the mechanics of clearing operations, statutory limits on disciplinary powers, and the contractual architecture governing derivative trading.
The Court directions were delivered as follows:
"The four appeals, Civil Appeal Nos. 31 of 2024, 2187 of 2024, 3179 of 2024 & 7313 of 2024 stand allowed setting aside the impugned orders of the MCSGF Committee and that of the SAT. The other appeal, Civil Appeal No. 4238 of 2026 stands rejected as not maintainable, since the orders impugned therein have already been set aside by us and the prayer is to grant the benefit of the orders set-aside, in restoring the cash margin of that individual appellant."
Evaluating the legal framework governing disciplinary actions by market infrastructure institutions, the Court, in its reasoning, observed:
"The Legislature while conferring the power of disgorgement on the SEBI, in two related statutes, consciously omitted it from being conferred under the byelaws of a stock exchange; which cannot be brought in, that too against the specific statutory bar, on grounds of equity, justice and good conscience."
Addressing the lack of client-level visibility prior to regulatory overhauls, the bench further noted:
"Obviously, these measures were not available earlier, and in that circumstance, we have to accept the contention of the PCM/Appellants that they had no visibility of the debit/credit positions of individual clients whose securities were furnished as collaterals by the TM to the CM. The absence of privity of contract, with the constituents of the TM, has also to be reckoned in favour of the PCMs..."
Ratio
In the absence of a specific statutory framework providing real-time client-level visibility, a Professional Clearing Member owes no statutory duty to verify individual debit or credit balances of a Trading Member's clients before liquidating collaterals upon broker default. Furthermore, disciplinary bodies of stock exchanges operating under Section 9(3)(b) of the Securities Contracts (Regulation) Act, 1956 lack the statutory jurisdiction to order monetary restitution or disgorgement.
Background
The controversy stemmed from massive defaults by defaulting Trading Members (TMs), such as Anugrah Stock & Broking Private Limited, who collected securities from individual investors and proffered them as collateral to PCMs. When the TMs defaulted on settlement obligations in the F&O segment, the PCMs liquidated the collaterals to cover the shortfall. The end-clients argued that their securities were improperly sold off despite having no debit balances with the TM.
The Member and Core Settlement Guarantee Fund Committee (MCSGFC) of the NSE Clearing Corporation (NCL) found the PCMs guilty of failing to exercise due diligence and ordered full restitution of the liquidated securities or equivalent monetary blocking. The Securities Appellate Tribunal upheld these orders, relying on equitable principles and procedural powers. Relying on constitutional principles outlined in Ahmedabad St. Xavier's College Society and Another v. State of Gujarat and Another, NCL maintained that the power to expel members included the lesser power to order restitution. However, the Supreme Court rejected this stance, distinguishing precedents like Director of Enforcement v. M.C.T.M. Corporation Pvt. Ltd. and Others and South Eastern Coalfields Ltd. v. State of M.P. and Others ( "(2003) 8 SCC 648": 2003 CaseBase(SC) 391), and emphasizing that Section 9(3)(b)(iv) of the Securities Contracts (Regulation) Act, 1956 explicitly prohibits penalties involving the payment of money.
Case Details:
Case No.: Civil Appeal No. 31 of 2024
Neutral Citation: 2026 INSC 941
Case Title: Edelweiss Custodial Services Limited v. NSE Clearing Ltd. & Anr.
Appearances:
For the Petitioner(s): Mr. Shyam Divan, Sr. Adv., Mr. Niranjan Reddy, Sr. Adv., Mr. Amar Nath Saini, Sr. Adv.
For the Respondent(s): Mr. Arvind P. Dattar, Sr. Adv., Ms. Meenakshi Arora, Sr. Adv.
Source: 2026 CaseBase(SC) 912
 Breaking News