


Madrs HC Bars Review for Tax Assessees failing Due Diligence on New Evidence
 Copy Link
 Share
 Save
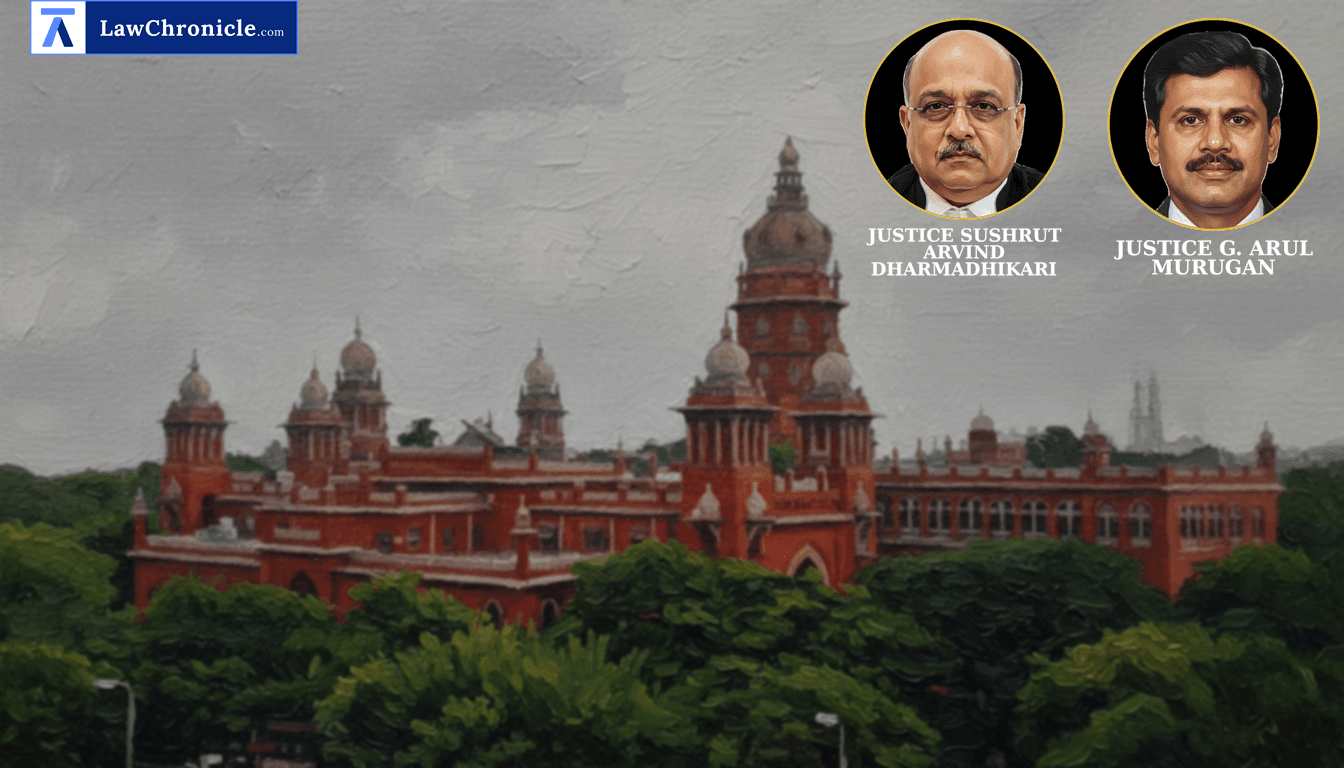
The Madras High Court has slammed the door on tax assessees attempting to use review petitions as a 'backdoor appeal,' ruling that the discovery of public documents years later does not satisfy the 'due diligence' requirement for reopening settled tax liabilities. The judgment reaffirms that the statutory burden under Section 68 of the Income-tax Act, 1961 remains absolute once funds are admitted into a personal account, regardless of claims of being a mere 'accommodation party.'
A Division Bench comprising Chief Justice Sushrut Arvind Dharmadhikari and Justice G. Arul Murugan delivered the verdict while dismissing a review application against a 2016 judgment. The Bench was hearing a challenge where an individual civil contractor sought to overturn the addition of Rs. 10 Crores to his income as unexplained cash credit, despite the dismissal of his earlier appeal by both the High Court and the Supreme Court.
Key Takeaways
Strict Due Diligence Mandatory
Review petitioners cannot rely on 'new evidence' that was already in the public domain during original proceedings unless they prove they couldn't access it despite due diligence.
Section 68 Burden is Absolute
Once a credit entry in a bank account is admitted, the assessee must prove the creditor's identity, creditworthiness, and the transaction's genuineness; failing which, it is taxable income.
No Second Bite at the Cherry
Review jurisdiction under the Code of Civil Procedure, 1908 cannot be used to substitute a judicial view or re-argue a case on merits that has already attained finality.
Court Observations on Section 68 and Review Scope
The Bench emphasized that the nature of Section 68 proceedings requires a triple-test of identity, capacity, and genuineness. The Madras High Court expressed that "The explanation offered by the assessee that he received Rs.10 Crores as an accommodation entry and passed on Rs.9.97 Crores to a third party, was tested by the authorities and found completely unsatisfactory. A mere paper arrangement or routing of funds through a personal bank account does not discharge the statutory burden under Section 68 of the Act."
Furthermore, the Madras High Court highlighted the limited scope of review, citing Malleeswari v. K. Suguna ( "2025 SCC OnLine SC 1927": 2025 CaseBase(SC) 660) to underscore that a review is not an appeal in disguise. It noted that the sale deeds and tribunal orders cited by the petitioner were public records available since 2007 and 2015 respectively. The Bench further added that “The assessee failed to demonstrate due diligence. Re-evaluating the same set of factual explanations under the guise of 'new material' amounts to seeking a re-hearing of the appeal, which review jurisdiction strictly forbids.”
Ratio
A review application under Order XLVII Rule 1 of the Code of Civil Procedure, 1908 based on the discovery of new evidence is only maintainable if the petitioner proves that such evidence was not within their knowledge or could not be produced at the time of the original decree despite the exercise of due diligence. Furthermore, the statutory burden under Section 68 of the Income-tax Act, 1961 is not discharged by admitting to being a conduit for 'accommodation entries' without proving the three essential pillars of the transaction.
Background
The dispute originated in Assessment Year 2007-08 when the Revenue, during a survey under Section 133A of the Income-tax Act, 1961, found a Rs. 10 Crore credit in the petitioner's bank account. The petitioner claimed he was a mere conduit for a friend and had transferred the bulk of the funds to a jeweler, retaining only a small commission. However, the Assessing Officer treated the entire amount as unexplained cash credit under Section 68, an addition upheld by the CIT(A), the ITAT, and subsequently by the High Court in 2016.
The petitioner had even approached the Supreme Court, where his SLP was dismissed in 2017. Years later, he filed this review, citing 'new' sale deeds and a different Tribunal order involving a co-party, claiming these documents proved he acted for a partnership firm and not in an individual capacity. The Madras High Court rejected these contentions, noting that the documents were always available and the receipt of funds in his personal account was an admitted fact that remained unexplained.
Case Details:
Case No.: REV.APPL.No. 107 of 2021
Neutral Citation: 2026:MHC:3956
Case Title: V.Babu Vs Deputy Commissioner of Income Tax
Appearances:
For the Petitioner(s): Mr.N.V.Balaji
For the Respondent(s): Mr.T.Ravikumar, Senior Standing Counsel; Mr.Umesh Rao.K., Junior Standing Counsel
Source: 2026 CaseBase(MAD) 24540
Similar Articles
 Breaking News


