


PHHC Rejects Capital Gains Tax On Aborted Joint Development Agreements
 Copy Link
 Share
 Save
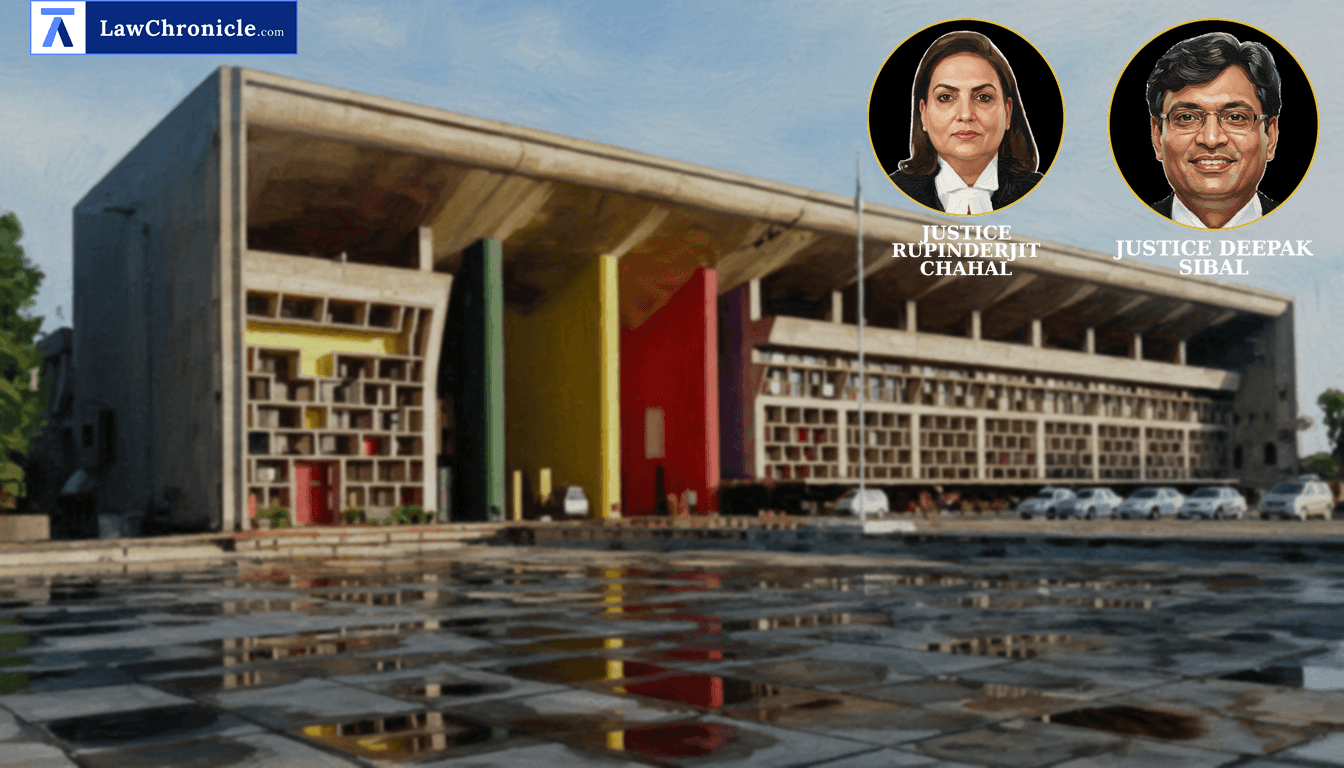
The Punjab and Haryana High Court paused the tax authorities' attempts to levy capital gains tax on Joint Development Agreements which were incomplete, ruling that partial possession without full consideration does not trigger a taxable transfer.
A bench comprising Justice Deepak Sibal and Justice Rupinderjit Chahal heard the appeal filed by an individual assessee challenging the imposition of capital gains tax arising from a 2007 Tripartite Joint Development Agreement (JDA). The Bench examined whether the execution of a JDA and delivery of possession for development constitutes a 'transfer' under the Income Tax Act, 1961.
Key Takeaways
Taxability of JDAs Defined
Execution of a Joint Development Agreement does not automatically trigger capital gains tax if the conditions of a valid transfer are not fully met.
Possession for Development vs. Transfer
Granting rights to a developer for the purpose of construction does not equate to a transfer of title under Section 53A of the [Transfer of Property Act, 1882 unless the transaction is complete.
Accrual of Income Requirement
Tax cannot be levied on consideration, such as built-up flats or future monetary installments, that have neither been received nor have legally accrued to the assessee.
Protection for Super Senior Citizens
Illiterate and elderly citizens cannot be penalized for technical non-compliance when the underlying transaction itself does not attract liability.
Same Developer - Identical Controversy
The Punjab and Haryana High Court observed that the controversy was identical to previous litigation involving the same developer and the same cooperative society. The Bench noted that the legal principles regarding the interaction between Section 2(47) of the Income Tax Act, 1961 and Section 53A of the Transfer of Property Act, 1882 were already settled.
The Court, in its reasoning, observed: "Since the present appeal arises from the very same JDA and involves an identical controversy, the findings recorded therein directly govern the issue before this Court. Consequently, the controversy raised in the present appeal stands concluded by the aforesaid decision….The present appeal is, accordingly, disposed of in terms of the judgment dated 22.07.2015 passed by this Court in C.S. Atwal v. Commissioner of Income Tax, Ludhiana and another, ITA No. 200 of 2013."
Ratio
Where a Joint Development Agreement remains incomplete and the full consideration (whether monetary or in-kind) is not received, the mere handing over of possession for development purposes does not constitute a 'transfer' under Section 2(47)(v) of the Income Tax Act, 1961 read with Section 53A of the Transfer of Property Act, 1882. Consequently, capital gains tax cannot be assessed on the total agreed consideration if the project is stalled and payments are defaulted.
Background
The appellant, a widow and nominee of a member of the Punjabi Cooperative House Building Society Limited, was involved in a JDA with Hash Builders and Tata Housing. Under the agreement, she was to receive ₹82.50 lakhs and a 2250 sq. ft. flat in exchange for development rights on a 500 square yard plot. However, she only received ₹33 lakhs as the project faced disputes. The Assessing Officer invoked Section 2(47) of the Income Tax Act, 1961, treating the JDA as a complete transfer and assessed a long-term capital gain of ₹1.77 crores, calculating the market value of the unbuilt flat.
The assessee argued that as a super senior citizen who was unaware of tax filings, she should not be liable for tax on income that never reached her. The Tribunal had previously dismissed her appeal, sustaining the Assessing Officer's view. However, the Punjab and Haryana High Court relied on its landmark precedent in C.S. Atwal v. Commissioner of Income Tax, Ludhiana and another, which dealt with the exact same JDA and held that such transactions did not attract capital gains tax at that stage. The Bench set aside the previous orders, allowing the appeal in favor of the assessee.
Case Details:
Case No.: ITA-447-2019(O&M)
Case Title: M/S Surjeet Kaur Dalam v. The Commissioner of Income Tax, Chandigarh and Others
Appearances:
For the Petitioner(s): Mr. Rajesh Kapoor, Advocate
For the Respondent(s): Ms. Urvashi Dhugga, Sr. Standing Counsel with Ms. Kavita, Advocate
Source: 2026 CaseBase(PNH) 21575
Similar Articles

 Breaking News


