Punjab and Hayana HC upholds Validity of Income Tax Return filed after death in Accident Claims
 Copy Link
 Share
 Save
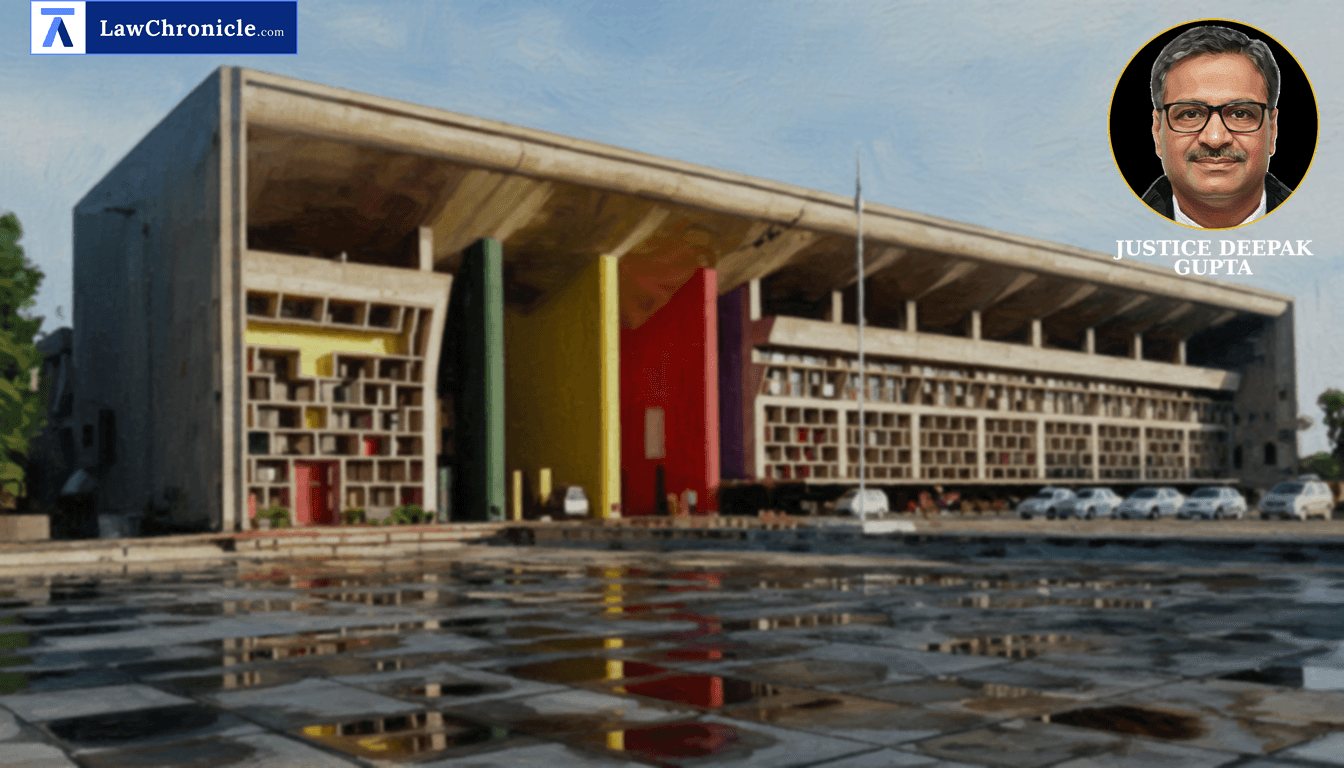
The Punjab and Haryana High Court has ruled that an income tax return filed after a person's death cannot be summarily discarded in motor accident claims. The Bench asserted that such documents serve as vital benchmarks for assessing just compensation, provided they withstand judicial scrutiny.
Justice Deepak Gupta presided over the appeal filed by the Punjab State, challenging the quantum of compensation awarded to the family of a 29-year-old deceased. The proceedings centered on the evidentiary weight of posthumous financial filings and the limits of the Court's power to modify awards under Section 151 of the Code of Civil Procedure, 1908 after significant delays. In a firm stand on procedural finality, the Court simultaneously refused to enhance a decade-old award, holding that beneficial legislation does not grant litigants an unrestricted right to bypass statutory limitation periods through inherent powers.
Key Takeaways
Posthumous Returns Admissible
Income tax returns filed after death of the deceased are not inherently invalid and can be considered for income assessment if they align with prior financial benchmarks.
Limits on Inherent Powers
Section 151 of the Code of Civil Procedure, 1908 cannot be used to circumvent statutory limitation periods for filing appeals or cross-objections, even in beneficial legislation like the Motor Vehicles Act.
Benchmark for Future Prospects
Following the [National Insurance Company Limited v. Pranay Sethi ( "(2017) 16 SCC 680": 2017 CaseBase(SC) 551) principles, future prospects and consortium must be calculated based on the deceased's age and family composition, though temporal delays may bar actual recovery.
Scrutiny of Income Spikes
Courts must exercise caution and scrutiny when a posthumous return shows a significant increase in income compared to returns filed during the deceased's lifetime.
Judicial Scrutiny of Income Tax returns Filed After Death
The appellants contested the Tribunal's reliance on an income tax return filed after the death of the deceased, Amit Goyal. They argued that only returns filed during the lifetime of the individual should be considered for determining dependency loss. However, the Punjab and Haryana High Court, relying on Nidhi Bhargava v. National Insurance Co. Ltd. ( "2025 SCC OnLine SC 872": 2025 CaseBase(SC) 1010) and Sayar & Ors. v. Ramkaran & Ors., clarified that while such returns require careful scrutiny, they are not automatically excluded from evidence.
The Court addressed the legal confusion that "It is true that a posthumously filed income-tax return calls for careful scrutiny. However, the mere fact that the return was filed after the death of the deceased cannot, by itself, constitute a valid ground for discarding it. The evidentiary value of such return has to be assessed in the context of the other material available on record, including the income disclosed in the return filed by the deceased during his lifetime."
Finality of Litigation and Section 151 CPC
While the Punjab and Haryana High Court found that a recalculated compensation based on National Insurance Company Limited v. Pranay Sethi ( "(2017) 16 SCC 680": 2017 CaseBase(SC) 551) would have resulted in a higher amount, it strictly declined the enhancement due to a ten-year delay by the claimants. The Bench emphasized that the inherent jurisdiction of the Court cannot be a tool to revive stale claims where the parties remained silent for a decade without explanation.
Ratio
An income-tax return filed posthumously is a relevant document for assessing the income of the deceased under the Motor Vehicles Act, 1988, provided it is supported by previous benchmarks and judicial scrutiny. However, the inherent power of the Court under Section 151 of the Code of Civil Procedure, 1908 cannot be invoked to seek enhancement of an award after an inordinate and unexplained delay, as the principle of finality of litigation must be balanced against the beneficial nature of the statute.
Background
The dispute arose from a fatal accident on December 27, 2012, involving a bus owned by the Punjab State. The Motor Accidents Claims Tribunal (MACT) awarded ₹59,08,078/- to the family of the deceased under Section 166 of the Motor Vehicles Act, 1988. The State appealed the quantum, primarily attacking the income assessment based on a return filed after his death. The claimants, during the pendency of the State's appeal in 2024, sought an enhancement of the compensation through an application under the Code of Civil Procedure, 1908, citing the principles in Surekha and others v. Santosh and others ( "(2021) 16 SCC 467": 2020 CaseBase(SC) 1026). The Punjab and Haryana High Court dismissed both the appeal and the application for enhancement, maintaining the original 2014 award.
Case Details:
Case No.: FAO-1818-2015 (O&M)
Neutral Citation: 2026:PHHC:128497
Case Title: Punjab State through its Chief Secretary and another Vs. Pooja Goyal and others
Appearances:
For the Petitioner(s): Mr. Ravinder Singh Rawal, AAG Punjab
For the Respondent(s): Mr. Harinder Sharma, Advocate, for Mr. Ajay Kumar Chaudhary, Advocate
Source: 2026 CaseBase(PNH) 19883
 Breaking News