SC Questions Requirement Of Fraudulent Intent To Invoke Section 47-A Stamp Act
 Copy Link
 Share
 Save
In a pivotal shift regarding property undervaluation laws, the Supreme Court has referred the correctness of its earlier precedents to a larger Bench, questioning whether a 'fraudulent intent' must be proven before revenue authorities can check undervaluation under the Indian Stamp Act, 1899.
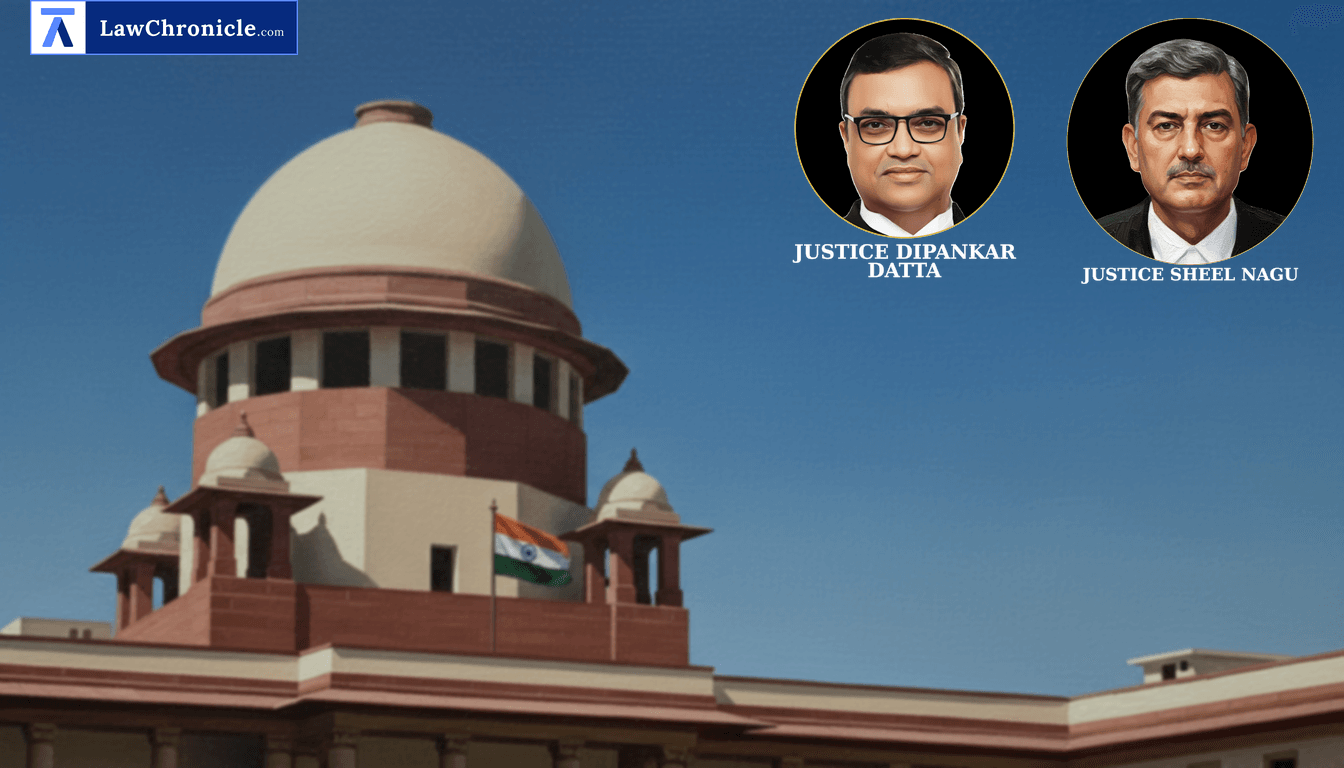
A Division Bench comprising Justice Dipankar Datta and Justice Sheel Nagu was hearing an appeal challenging a judgment of the Madras High Court that permitted stamp duty re-assessment proceedings against a PSU vendee without examining fraudulent intent at the threshold.
Key Takeaways
- Referral to Larger Bench: The Supreme Court has expressed serious doubts on the three-judge bench ruling in V.N. Devadoss v. Chief Revenue Control Officer-cum-Inspector of Stamps and referred the issue of interpreting Section 47-A of the Indian Stamp Act, 1899 to a larger Bench.
- Textual vs Fraud-Centric Approach: The Court observed that reading 'wilful undervaluation' or 'fraudulent intent' into Section 47-A goes beyond the plain statutory text.
- Impact on Honest Buyers: The Bench highlighted that a fraud-centric test unfairly forces honest purchasers of encumbered properties to defend their character rather than proving objective market value.
- Exchequer Protection: The Court noted that requiring prior proof of fraudulent intent can disable registering authorities from initiating legitimate inquiries where secret cash transactions occurred.
Court's Observations and Legal Rationale
The Supreme Court analyzed the statutory framework of Section 47-A of the Indian Stamp Act, 1899 and observed that the section merely requires a 'reason to believe' that market value has not been truly set forth, without expressly mentioning fraudulent intent.
The Court, in its reasoning, observed: "The expressions 'wilful undervaluation' and/or 'fraudulent intention' is/are conspicuously absent in the plain phraseology of sub-section (1) of the said provision. On its own terms, Section 47-A does not require the registering authority to issue notice having 'reason to believe' of a culpable mindset being the motive behind the transaction; it merely requires reason to believe that the market value of the property has not been truly set forth in the instrument presented before him for consideration."
Addressing the precedent in V.N. Devadoss v. Chief Revenue Control Officer-cum-Inspector of Stamps, which was followed in Registrar of Assurances v. ASL Vyapar (P) Ltd, the Court doubted its efficacy and noted that importing a culpable mindset converts a pure valuation inquiry into a quasi-criminal proceeding. Conversely, decisions like Ramesh Chand Bansal v. District Magistrate/Collector and Shanti Bhushan v. State of U.P. emphasize that taxing statutes must be strictly construed according to their plain literal meaning.
Ratio
Section 47-A of the Indian Stamp Act, 1899 on its plain language requires only a reason to believe that the market value or consideration of a property has not been truly set forth in the instrument. Judicial interpretation cannot read 'wilful undervaluation' or 'fraudulent intent' as mandatory jurisdictional pre-conditions into a taxing statute when such words are absent in the text.
Background
The appellant purchased a parcel of land from the Government of India in 2014 and presented the transfer deed for registration in 2016 after paying stamp duty on the agreed sale consideration. The registering officer referred the matter under Section 47-A of the Indian Stamp Act, 1899 based on administrative guideline values, resulting in a show-cause notice demanding differential stamp duty.
A Single Judge of the High Court quashed the notice relying on V.N. Devadoss v. Chief Revenue Control Officer-cum-Inspector of Stamps, holding that recourse to Section 47-A requires deliberate undervaluation with fraudulent intent. However, a Division Bench of the High Court reversed this decision, holding that writ petitions against show-cause notices are maintainable only in exceptional cases and that statutory alternative remedies under the Indian Stamp Act, 1899 and the Tamil Nadu Stamp (Prevention of Undervaluation of Instruments) Rules, 1968 must be exhausted.
On further appeal, the Supreme Court observed that while judicial discipline required adherence to larger bench precedents, it was appropriate to refer the conflict to a larger Bench to decide whether Section 47-A can be invoked irrespective of the absence of a culpable mindset.
Case Details:
Case No.: Civil Appeal No.______ of 2026 [Arising out of SLP (C) No. 37096 of 2025]
Neutral Citation: 2026 INSC 963
Case Title: Bharat Petroleum Corporation Limited v. The District Revenue Officer (Stamps) & Anr.
Appearances:
For the Petitioner(s): Mr. N. Venkataraman, Additional Solicitor General
For the Respondent(s): Ms. Haripriya Padmanabhan, Senior Advocate
Source: 2026 CaseBase(SC) 5096
 Breaking News