


Section 263 Revisionary Powers Cannot Be Used to Improve Assessment Orders: Gujarat HC
 Copy Link
 Share
 Save
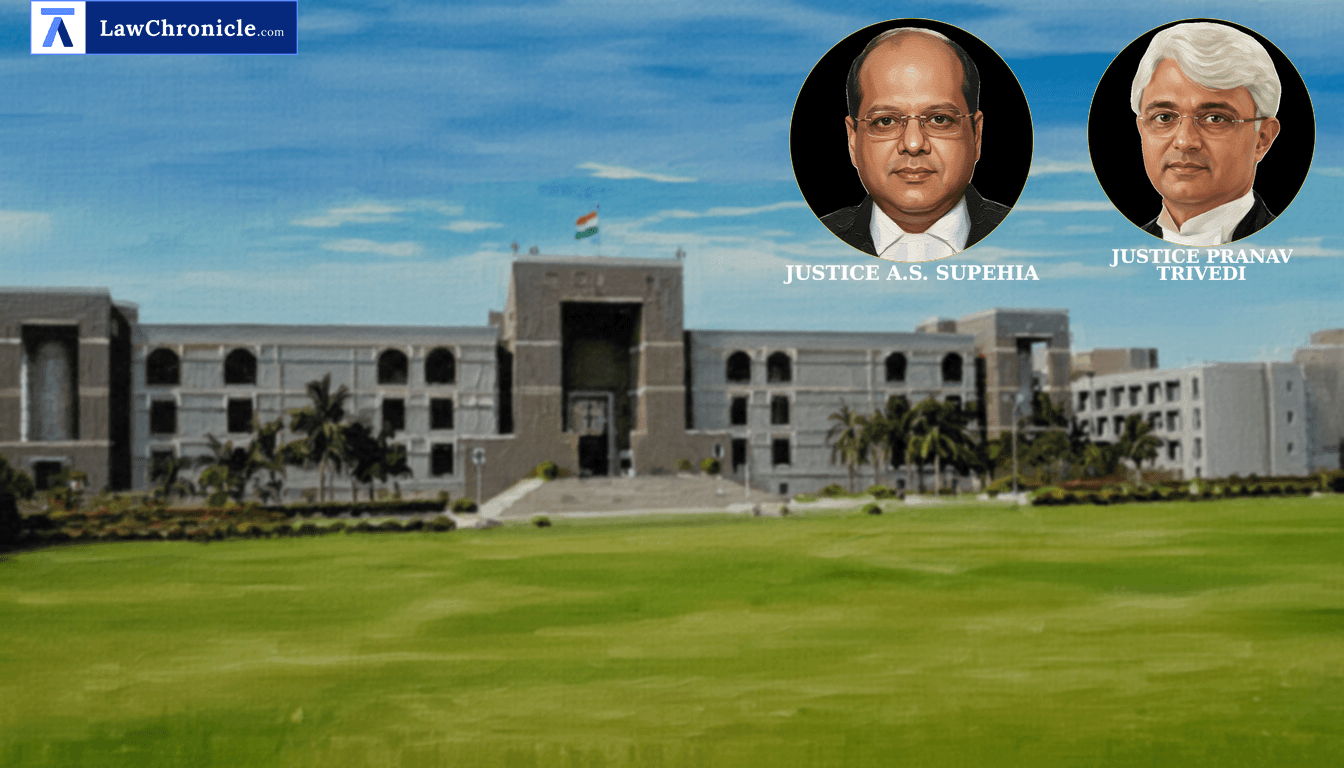
The Gujarat High Court quashed revision notices issued under the Income Tax Act, 1961, holding that revisionary powers cannot be exercised when the Assessing Officer has taken a plausible view based on the available material.
A division bench comprising Justice A.S. Supehiya and Justice Pranav Trivedi heard the challenge against notices seeking to revise completed assessments for the year 2019-20. The Court emphasized that Section 263 of the Income Tax Act, 1961 is not a tool for the revenue to improve a legally sound assessment order or substitute its opinion with that of the Assessing Officer.
Court Rejects Revision Based on Valuation Disputes
The dispute centered around the valuation of land sold by the petitioner. While a seized Memorandum of Understanding (MoU) suggested a value of Rs. 39.32 crores, the property was eventually sold for Rs. 12 crores. The Assessing Officer (AO) had referred the matter to a Departmental Valuation Officer (DVO), who valued it at Rs. 28.50 crores, leading to an addition of Rs. 8.25 crores to the petitioner's income. The Principal Commissioner sought to revise this, arguing the AO should have stuck to the MoU value.
However, the Court found that the AO had conducted a thorough inquiry by considering circumstantial evidence, sworn statements, and the DVO report. The Court, in its reasoning, observed: "it is settled precedent that though the Commissioner can certainly invoke the powers under Section 263 of the Act... such powers are to be exercised sparingly in those case where the Assessing Officer had perfunctorily made the inquiry bereft of any discussion... in case it is found that the view adopted by the Assessing Officer is a plausible view taken after considering the relevant material on record, the Commissioner would not substitute his opinion with that of the Assessing Officer."
Jurisdictional Error in Penalty Proceedings
The revenue also contended that the AO failed to initiate penalty proceedings under Section 271D for alleged violations of Section 269SS. The Court noted a glaring jurisdictional error in this reasoning, as the power for an AO to impose such penalties only commences from April 1, 2025. Referring to Aryan arcade Ltd. vs. Commissioner of Income-tax I and JMC Projects (India) Limited vs. Principal Commissioner of Income-tax (Central) ( "[2016] 67 taxmann.com 258 (Gujarat)": 2015 CaseBase(GUJ) 1990), the Court reiterated that if a legitimate tax has been realized via a plausible methodology, the order cannot be deemed prejudicial to the revenue.
Background:
The case originated from a search and seizure action under Section 132 of the Income Tax Act, 1961 on a land broker group in 2019, where an MoU involving the petitioner was discovered. Following the search, assessment proceedings were initiated under Section 153C. The petitioner challenged the subsequent Section 263 revision notices on the grounds that the AO had already applied his mind to the seized material and obtained a DVO report. The High Court agreed with the petitioner, ruling that the revenue cannot invoke revisionary jurisdiction simply because it prefers a different valuation methodology or seeks to "iron out" flaws in a valid assessment order.
Case Details:
Case No.: R/SPECIAL CIVIL APPLICATION NO. 4314 of 2026
NeutralCitation: 2026:GUJHC:29206-DB
Case Title: DILIP PATEL Versus THE PRINCIPAL COMMISSIONER OF INCOME TAX (CENTRAL), AHMEDABAD
Appearances:
For the Petitioner(s): MR B S SOPARKAR(6851)
For the Respondent(s): MR. VARUN K. PATEL(3802)
Source: 2026 CaseBase(GUJ) 236
Similar Articles
 Breaking News


