


Statutory Deeming Fiction Under Waqf Act Precludes Fresh Property Inquiry: Gujarat HC
 Copy Link
 Share
 Save
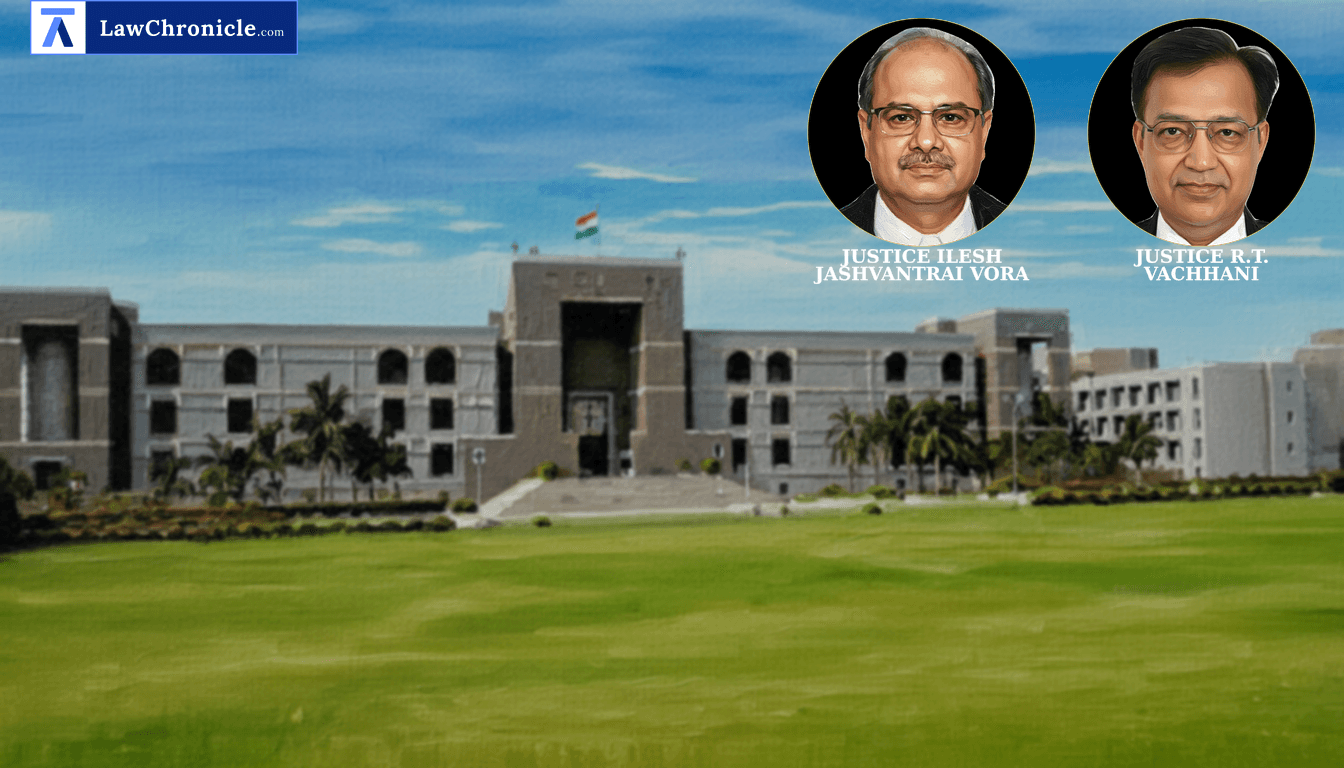
In a decisive reinforcement of statutory finality, the Gujarat High Court has ruled that trusts registered under the Bombay Public Trust Act, 1950 with religious and charitable objectives are deemed registered under the Waqf Act, 1995, effectively barring subsequent challenges to their waqf status. The Bench affirmed that where a trust's objectives include maintaining mosques or graveyards, the automatic transition under Section 43 of the Waqf Act, 1995 leaves no room for administrative re-classification or fresh inquiries.
A Division Bench comprising Justice Ilesh J. Vora and Justice R. T. Vachhani delivered this judgment while hearing a First Appeal filed by the Muslim Kuzafarosh Jamat Trust. The appellant sought to overturn a Waqf Tribunal order which had categorized the institution as a 'Waqf' rather than a 'Trust', challenging the validity of a Registration Certificate issued by the Waqf Act, 1995 Board.
Key Takeaways
Mandatory Deeming Fiction
Registration under the Bombay Public Trust Act, 1950 prior to 1996 triggers an automatic deeming fiction under Section 43 of the Waqf Act, 1995, obviating the need for fresh registration or inquiries into the nature of the property.
Administrative Limits
Communications from a Chief Executive Officer (CEO) cannot override statutory classifications or take the place of a formal judicial or board inquiry as mandated by law.
Defining Religious Purpose
Trusts dedicated to maintaining mosques, Madrasas, Dargahs, or graveyards fall squarely within the definition of 'Waqf' under Section 3(r) of the Waqf Act, 1995, regardless of their prior registration category.
Jurisdictional Finality
Once a property is deemed a Waqf by operation of law, the Waqf Tribunal holds exclusive jurisdiction to determine disputes related to its management and character.
Judicial Scrutiny of the 'Waqf' Classification
The High Court analyzed the interplay between Sections 40 and 43 of the Waqf Act, 1995. The appellant contended that a proper inquiry under Section 40 was necessary before the property could be treated as Waqf, especially following a 2011 CEO communication suggesting the trust be remitted to the Charity Commissioner. However, the Court rejected this, noting that Section 43 applies to all Waqf registered under any law in force before the 1995 Act's commencement.
The Court has the following directions:
"For the reasons recorded herein above, the appeal fails and it is accordingly dismissed while confirming the impugned order passed by the Tribunal. Consequently, the Civil Application for Stay is also dismissed."
The Court, in its reasoning, observed: "It is expressly clear that in the aforesaid circumstances since the appellant - Trust - Jamat has already been registered for the purpose as enshrined therein and again after the enactment of the Waqf Act, 1995 came into force the same is not subject to any inquiry or decision as to whether the properties is a waqf property or not and therefore, under the aforesaid circumstances the provisions of Section 43 of the Waqf Act does apply to the facts of the case on hand."
Ratio
Registration of a public trust under the Bombay Public Trust Act, 1950 with objects of a religious or charitable nature relevant to the Islamic faith constitutes a 'deemed registration' under Section 43 of the Waqf Act, 1995. Such statutory conversion precludes the necessity of a fresh inquiry under Section 40 of the Waqf Act, 1995, and administrative correspondence by a CEO cannot negate this legal status or the jurisdiction of the Waqf Board.
Background
The dispute originated from a 1952 application where the appellant-Trust claimed to be a mere association. This was rejected by the Deputy Joint Charity Commissioner, who registered it as a Muslim Trust (Category 'B') under the Bombay Public Trust Act, 1950, a decision upheld by the District Court in 1953. Following the enactment of the Waqf Act, 1995, the trust's records were transferred to the Waqf Board.
In 2011, the CEO of the Waqf Board issued a letter suggesting the trust was not a 'Waqf' under Section 3(r) and should be returned to the Charity Commissioner. Internal management disputes later led to the issuance of a Registration Certificate by the Waqf Board in 2017. The appellant challenged this certificate before the Waqf Tribunal, relying on the 2011 CEO letter. The Tribunal dismissed the application, holding the trust to be a Waqf, leading to the present appeal. The High Court distinguished the precedents Maharashtra State Board of Waqfs vs. Shaikh Yusuf Bhai Chawla & Ors. ( "[2022 SCC Online SC 1653]": 2022 CaseBase(SC) 1288) and M.P. Waqf Board vs. Subhan Shah (Dead) by Lrs & Ors. ( "[(2006) 10 SCC 696]": 2006 CaseBase(SC) 1143), finding that the mandatory inquiry issue did not apply where a valid prior registration existed.
Case Details:
Case No.: R/FIRST APPEAL NO. 3498 of 2025
Neutral Citation: 2026:GUJHC:57030-DB
Case Title: Muslim Kuzafarosh Jamat Through President Versus Gujarat State Waqf Board & Ors.
Appearances:
For the Petitioner(s): Mr Mtm Hakim With Mr Rizwan Shaikh(7146)
For the Respondent(s): Fouzan N Soniwala(8442), Mr Manish S Shah(5859), Ms Ratna Vora Advocate
Source: 2026 CaseBase(GUJ) 20972
Similar Articles
 Breaking News


