


Unregistered Agreement To Sell No Bar To Specific Performance Suits: Delhi High Court
 Copy Link
 Share
 Save
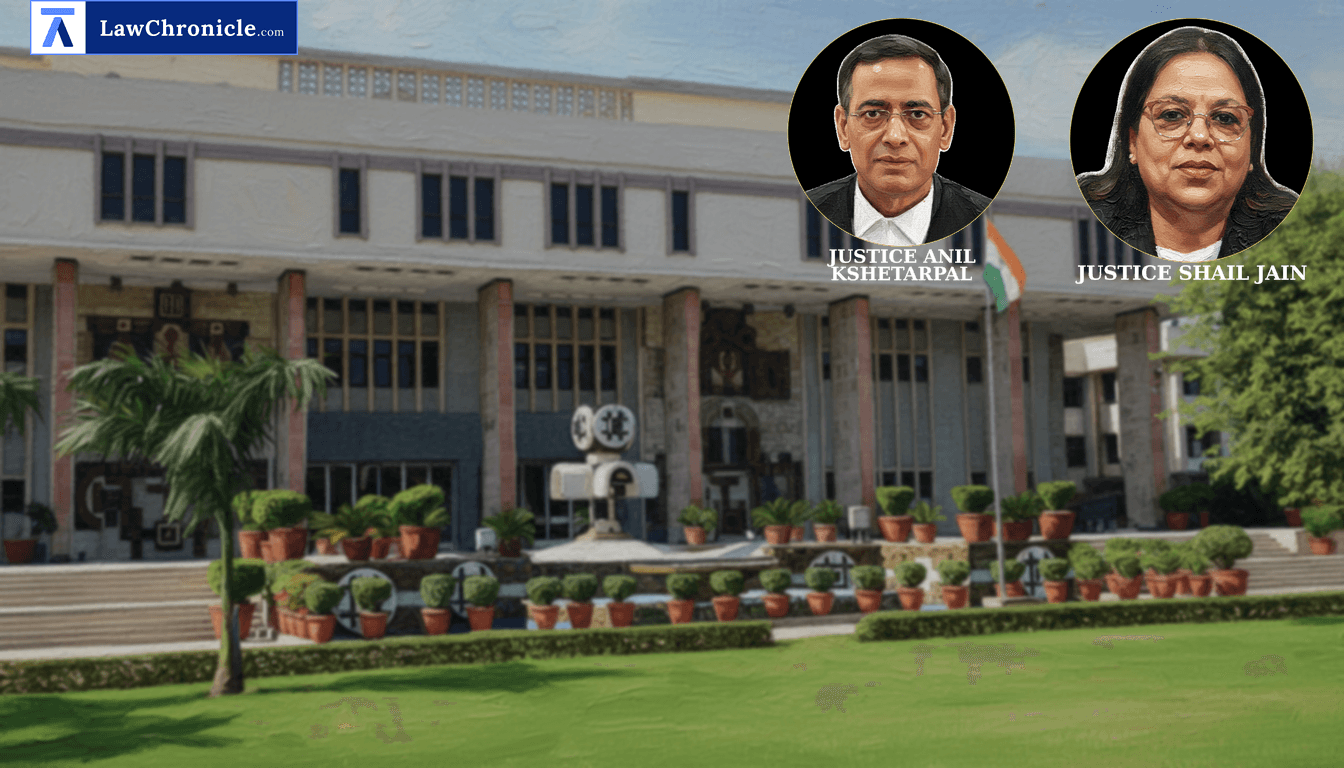
The Delhi High Court has clarified the legal interplay between property registration and maintainability of suits, ruling that an unregistered agreement to sell, even if accompanied by delivery of possession, remains admissible in evidence to prove a contract for specific performance. This decision prevents the summary rejection of suits under Code of Civil Procedure, 1908 solely for lack of registration, provided the document is received as proof of the contract rather than a claim for part-performance protection.
A bench comprising Justice Anil Kshetarpal and Justice Shail Jain heard the appeal challenging a District Judge's order that had rejected a plaint at the threshold. The lower court had concluded that an agreement to sell was inadmissible for want of registration and insufficient stamping, thereby barring the suit under the Transfer of Property Act, 1882 and the Registration Act, 1908.
Key Takeaways
Survival of Specific Performance Suits
Non-registration of an agreement to sell does not automate the rejection of a suit for specific performance under Order VII Rule 11 of the Code of Civil Procedure, 1908.
Evidence for Collateral Transactions
While an unregistered document cannot protect possession under Section 53-A of the Transfer of Property Act, 1882, it serves as admissible evidence for proving the existence of a contract.
Judicial Power to Cure Stamp Defects
Trial courts possess the authority to receive insufficiently stamped documents in evidence directly after the payment of deficient duty and penalty, without mandatory external impounding delays.
Differential Stamp Duty for Joint Owners
Stamp duty calculations must respect concessional rates for women, even in joint ownership scenarios, by applying proportional rates to their respective shares.
Admissibility of Unregistered Documents
The Court analyzed the impact of the 2001 amendments to the Registration Act, 1908 and the Transfer of Property Act, 1882. It noted that while Section 17(1-A) of the Registration Act, 1908 makes documents involving part performance compulsorily registrable, the proviso to Section 49 provides a critical exception.
Referring to the legal principles in Ram Kishan and Anr. v Bijendra Mann alia Vijendra Mann and Ors, the Court observed that non-registration only strips a party of the shield of 'part performance' under Section 53-A of the Transfer of Property Act, 1882 but does not destroy the right to seek specific performance of the agreement itself.
The Court, in its reasoning, observed: "...non-registration does not bar a suit for specific performance. In particular, the proviso to Section 49 of the Act of 1908... expressly permits an unregistered document to be received in evidence as proof of a contract in a suit for specific performance. Thus, while an unregistered agreement cannot be relied upon to claim the protection under Section 53-A, it may nevertheless form the basis of a suit for specific performance and be received in evidence for proving the contract."
Directives on Stamping and Penalty
Regarding the Stamp Act, 1899, the Court held that insufficiency of stamping is a curable defect and not a ground for rejection of a plaint under Order VII Rule 11(d). It emphasized that under Section 35 of the Stamp Act, 1899, a Court is competent to receive an instrument in evidence once the deficiency and penalty are paid. Citing Avinash Kumar Chauhan v Vijay Krishna Mishra ( "(2009) 2 SCC 532": 2008 CaseBase(SC) 1148) and Omprakash v. Laxminarayan ( "(2014) 1 SCC 618": 2013 CaseBase(SC) 758), the bench held that relegating parties to external collectors for impounding when the court itself can adjudicate the duty causes avoidable delay.
The Court has following directions:
"This Court directs the Plaintiffs to deposit the deficient stamp duty of Rs. 59,950/-, together with a penalty of Rs. 5,99,500/-, before the LDJ, within a period of one (01) month from today, whereupon the ATS shall stand admitted in evidence and suit would continue to proceed. However, the matter shall be forwarded to the Competent Collector for determination of the Plaintiffs entitlement, if any, to refund any part of the penalty in terms of Section 40 of the Act of 1899, in exercise of her/his discretionary power and in light of the principles laid down in H.C. Dhanda Trust (Supra) without affecting the progress of the pending suit."
Ratio
An unregistered agreement to sell, though falling under the ambit of Section 53-A of the Transfer of Property Act, 1882, is not inadmissible for the purpose of a suit for specific performance by virtue of the proviso to Section 49 of the Registration Act, 1908. Furthermore, a plaint cannot be rejected under Order VII Rule 11(d) of the CPC for insufficiency of stamp duty, as such defects are curable through payment of duty and penalty before the Court under Section 35 of the Indian Stamp Act, 1899.
Background
The dispute originated from an Agreement to Sell (ATS) dated May 10, 2019, for a shop in Okhla, New Delhi. The Appellants (Plaintiffs) paid the full consideration of Rs. 12,00,000 and the Respondent (Defendant) remained in possession as a tenant. When the Defendant allegedly stopped paying rent and denied the Plaintiffs' title, a suit was filed for specific performance and recovery of possession.
The District Judge rejected the plaint, citing Section 17(1-A) of the Registration Act, 1908, holding that the document was inadmissible and the suit barred. The High Court, however, relied on H.C. Dhanda Trust vs. State of Madhya Pradesh and Ors. regarding the court's discretion on penalties and Peteti Subba Rao vs. Anumala S. Narendra ( "2000 LawSuit(SC) 1869": 2000 CaseBase(SC) 73) to differentiate between the protective shield of Section 53-A and the substantive right to seek specific performance. The High Court set aside the lower court's judgment and restored the suit.
Case Details:
Case No.: RFA (COMM) 134/2023
Case Title: DHARMENDRA SINGH & ANR v. FAZLU REHMAN
Appearances:
For the Petitioner(s): Mr. Shekhar Dasi, Mohd. Talha, Mr. Ayush Dassi, Mr. Deepesh Kasana and Mr. Divyansh Malhotra, Advs.
For the Respondent(s): None.
Source: 2026 CaseBase(DEL) 5681
Similar Articles
 Breaking News


