


18-Month Tax Settlement Limit Mandatory; Board Transfer Cannot Reset Clock: Allahabad HC
 Copy Link
 Share
 Save
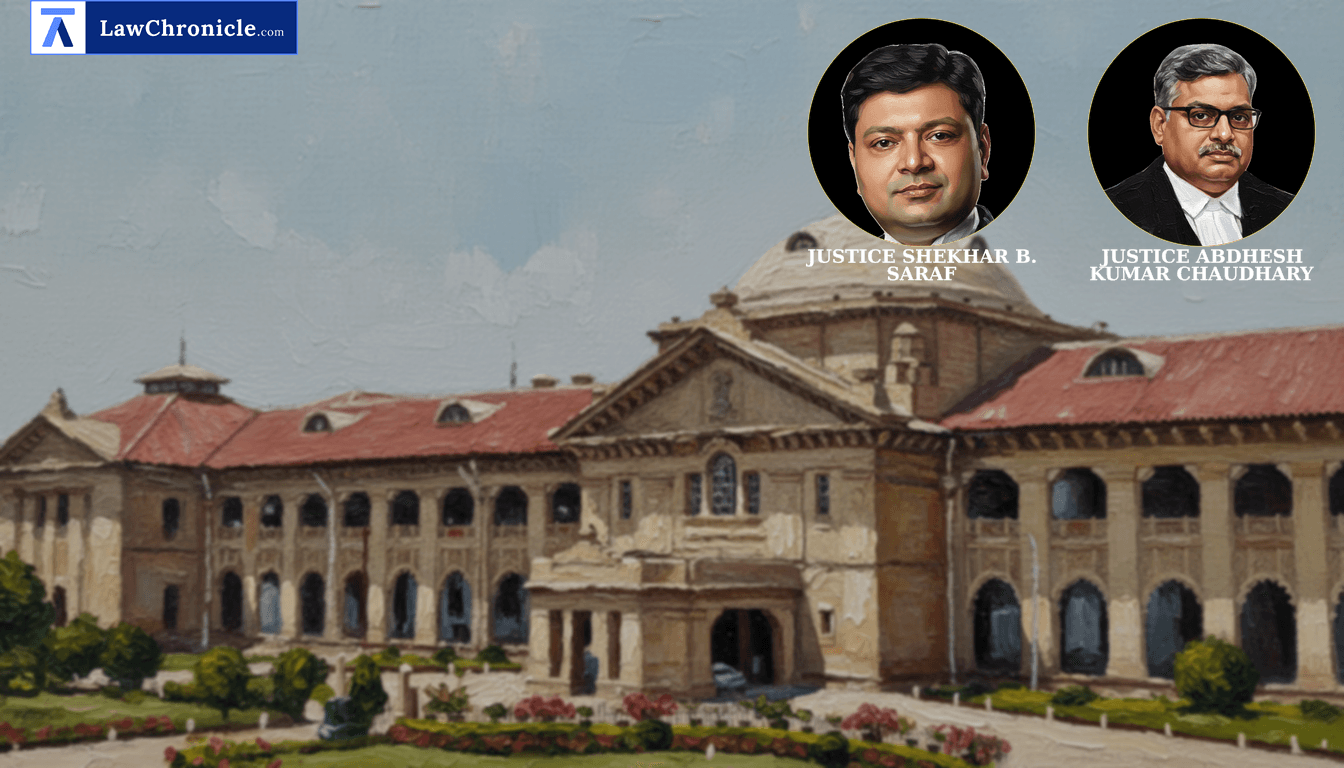
Administrative transfers between tax settlement boards cannot be weaponised by authorities to reset statutory deadlines and prolong proceedings indefinitely. A division bench of the Allahabad High Court ruled that the 18-month timeline prescribed under Section 245D(4A) of the Income Tax Act, 1961 for passing a final settlement order is mandatory, and administrative transfers between Interim Boards for Settlement cannot extend this limitation period.
A division bench of Justice Shekhar B. Saraf and Justice Abdhesh Kumar Chaudhary delivered the ruling while hearing a batch of writ petitions filed under Article 226 of the Constitution of India. The primary issue before the Court was whether the statutory 18-month period prescribed under Section 245D(4A)(iii) read with Section 245D(9)(iii) and Section 245M(2) of the Income Tax Act, 1961 commenced when the settlement application was initially allotted to an Interim Board or when it was subsequently transferred administratively to another Board by the Central Board of Direct Taxes (CBDT).
Key Takeaways
Strict Enforcement of Statutory Deadlines: The 18-month time limit for disposing of tax settlement applications under Section 245D(4A) of the Income Tax Act, 1961 is strictly mandatory, rendering orders passed beyond this window void.
Administrative Transfer Does Not Reset Clock: Subsequent transfer of a pending application from one Interim Board for Settlement to another by administrative order does not trigger a fresh limitation period.
Protection Against Executive Overreach: Accepting the revenue department's stance would allow endless extension of statutory periods through simple administrative shuffling, defeating the legislative mandate for time-bound dispute resolution.
Court's Reasoning and Observations
The High Court systematically rejected the revenue department's argument that limitation should be computed from the date of administrative transfer. The Court, in its reasoning, observed: "This argument, in our view, is not sustainable as the period prescribed
under Section 245D(4A)(iii) cannot be extended once the Interim Board takes cognizance of the interim application pending before it. Furthermore, the moment the Interim Board IBS-III, Delhi passed an order under Section 245D(4A)(iii) calling for the Rule 9 report, it would automatically mean that the IBS-III, Delhi had been allotted the said file."
The Court noted that the initial allotment to IBS-III, Delhi occurred under the e-Settlement Scheme, 2021 on November 1, 2021, and the Board took active steps by inviting a Rule 9 report on March 7, 2022. Computing limitation from either date demonstrated that the final order passed on October 30, 2023, was heavily time-barred. Relying on settled principles laid down in RNS Infrastructure Ltd. vs. Income-tax Settlement Commissioner, affirmed in CIT v. RNS Infrastructure Ltd. and upheld by the Supreme Court in SLP filed before the Hon’ble Supreme Court, the bench held that any order rendered beyond the mandatory 18-month timeframe is a nullity.
The Court issued the following directions:
"Accordingly, the order dated October 30, 2023 as well as consequential order dated December 15, 2023 of the Act passed by IBS-VII, Chennai are quashed and set aside accordingly the writ petition is allowed."
Ratio
The statutory period of 18 months prescribed under Section 245D(4A)(iii) of the Income Tax Act, 1961 for passing a final settlement order is mandatory. Once an Interim Board assumes jurisdiction and takes cognizance of a pending application, subsequent administrative transfers of the file to another Interim Board do not restart or extend the limitation period.
Background
Following a search operation under Section 132 of the Income Tax Act, 1961 on October 4, 2018, proceedings under Section 153A and Section 143(2) were initiated against the petitioner. When the Income Tax Settlement Commission was abolished by the Finance Act, 2021 with retrospective effect from February 1, 2021, the petitioner obtained judicial relief from the High Court permitting it to submit its settlement application by March 23, 2021.
Subsequent notifications by the CBDT treated the application as a pending application under Section 245A(eb) and allocated it to IBS-III, Delhi, which formally initiated proceedings on March 7, 2022, by calling for a Rule 9 report under the Income Tax Settlement Commission(Procedure) Rules, 1997. On June 13, 2022, the CBDT administratively transferred the application to IBS-VII, Chennai. IBS-VII, Chennai rejected the settlement application on October 30, 2023, and subsequently dismissed rectification applications on December 15, 2023.
The petitioner argued before the High Court that jurisdiction under Section 245D(3) was already exercised by the Delhi Board, making November 1, 2021 (or at latest March 7, 2022) the starting point of limitation, rendering the October 2023 order time-barred. Counsel relied on precedents including Major Metals Ltd. vs. Union of India, Omaxe Ltd. vs. ACIT, CIT vs. Express Newspapers Ltd., Thomas Phillip vs. Interim Board for Settlement, Jain Metal Rolling Mills vs. UOI, Sar Senapati Santaji Ghorpade Sugar Factory Ltd. vs. ACIT, Megha Engineering and Infrastructure Ltd. vs. Income-tax Settlement Commission ( "[2025] 481 ITR 356 (Delhi)": 2025 CaseBase(DEL) 5064), Star Television News Ltd. vs. UOI, Akshar Builders vs. Principal Commissioner of Income Tax, Re: Hindustan Lever Mazdoor Sabha vs. Hindustan Lever Ltd. ( "(1998) 8 SCC 349": 1996 CaseBase(SC) 646), and Raza Textiles Ltd. vs. Income Tax Officer, Rampur ( "(1973) 87 ITR 539 (SC)": 1972 CaseBase(SC) 367). Conversely, the revenue relied on Checkmate Services (P.) Ltd. vs. Commissioner of Income Tax ( "(2022) 143 taxmann.com 178 (SC)": 2022 CaseBase(SC) 874), Ajmera Housing Corpn. vs. Commissioner of Income Tax, Mathuram Agarwal vs. State of Madhya Pradesh and others ( "(1999) 8 SCC 667": 1999 CaseBase(SC) 539), and Star Television News Ltd. vs. UOI to contend that limitation restarted on June 13, 2022 upon transfer to Chennai, making the order timely.
Accepting the petitioner's contentions, the High Court held that the order was ex-facie barred by limitation, setting aside both the rejection and rectification orders.
Case Details:
Case No.: WRIT TAX No. - 77 of 2024
Case Title: M/s B.L. Agro Industries Limited v. Union of India and others
Appearances:
For the Petitioner(s): Kavita Jha, Anjali Pandey, Aahuti Agarwal, Abhishek Khare, Navneet Yadav, Shailesh Verma
For the Respondent(s): A.S.G.I., Dr. Ravi Kumar Mishra, Kushagra Dikshit, Neerav Chitravanshi, Ravi Kumar Mishra
Source: 2026 CaseBase(ALL) 608
Similar Articles
 Breaking News


