


Actual Institution Of Audit Determines Commencement Date Under CGST Act: Gujarat HC
 Copy Link
 Share
 Save
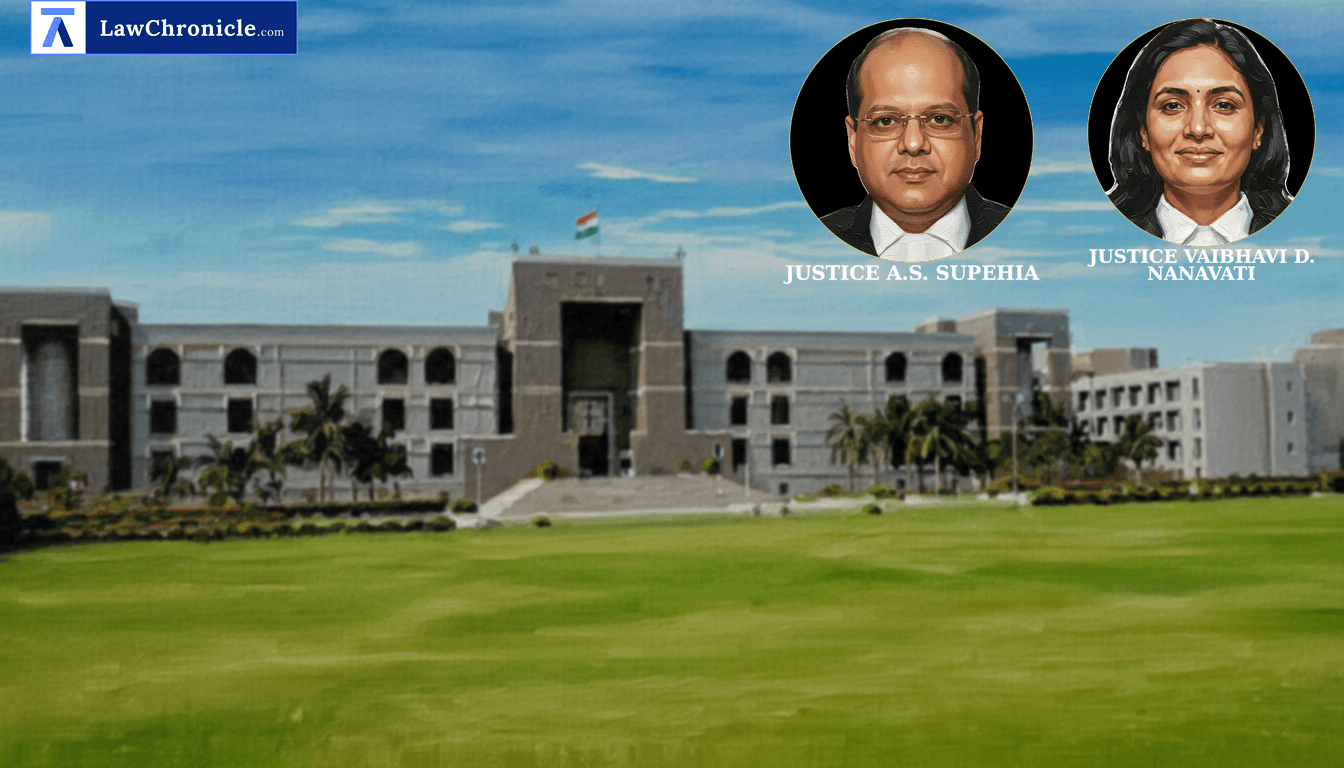
The Gujarat High Court has solidified the interpretation of audit timelines under the Central Goods and Services Tax Act, 2017, ruling that the date of 'actual institution' at the place of business serves as a valid alternative starting point for the limitation period regardless of when documents were initially furnished. This decision effectively shields tax authorities from claims of being time-barred in cases where disputes exist regarding the completeness of records submitted by a registered person.
A Division Bench comprising Justice A.S. Supehia and Justice Vaibhavi D. Nanavati adjudicated upon a writ petition challenging eight show-cause notices and an audit report. The petitioner sought to quash these proceedings, arguing that the audit for Financial Years 2017-18 to 2019-20 was concluded beyond the three-month statutory limit prescribed under Section 65(4) of the Central Goods and Services Tax Act, 2017.
Key Takeaways
Dual Trigger for Audit Commencement
The court clarified that under the Explanation to Section 65, the 'commencement of audit' is determined by either the submission of documents or the actual visit to the business premises, whichever occurs later.
Protection Against Procedural Technicalities
Taxpayers cannot claim an audit is time-barred simply by citing early document submission if the physical audit was instituted at a later date, especially when document sufficiency is in dispute.
Duty of Disclosure on Authorities
While the court upheld the audit's validity, it emphasized that tax authorities should ideally inform registered persons of missing documents within a reasonable time to prevent avoidable delays.
Alternative Remedy Exhaustion
The ruling reinforces that writ petitions against show-cause notices are generally not entertained when statutory appellate remedies under Section 107 of the GST law remain available.
Interpretation of Section 65 and Audit Timelines
The primary controversy revolved around whether the audit commenced when the petitioner first provided documents in 2022 or when the tax officers physically visited the premises in June 2024. The Court analyzed the statutory framework of Section 65 of the Central Goods and Services Tax Act, 2017, which mandates that an audit must be completed within three months from its commencement, extendable by the Commissioner for another six months.
The Court, in its reasoning, observed: "Sub-section(4) of Section 65 of the CGST Act prescribes a period of three months for the completion of an audit from the date of commencement of the audit... The Explanation to Section 65 of the CGST Act further defines the expression “commencement of audit” to mean the date on which the records and other documents called for by the tax authorities are made available by the registered person or the actual institution of the audit at the place of business, whichever is later. Thus, the date of commencement of the audit is determined by reference to the later of these two events."
The Court noted that since the audit was actually instituted at the place of business on 19.06.2024 and the report was prepared by 02.08.2024, it fell well within the three-month window. The bench refused to quash the show-cause notices issued under Section 74 of the Central Goods and Services Tax Act, 2017, which alleged willful misstatement and suppression of facts.
The Court has following directions:
"As regards the challenge to the impugned show-cause notices on merits, we are not inclined to set them aside at this stage. The petitioner-Company may respond to the notices. The petitioner-Company also has the remedy of challenging the action before the appellate authority by filing an appeal under Section 107 of the CGST Act. Hence, the writ petition fails. Rule is discharged."
Ratio
The "commencement of audit" under Section 65 of the Central Goods and Services Tax Act, 2017 is a legal fiction determined by the later of two specific events: the date of production of records or the date of actual institution of audit at the business premises. If there is a factual dispute regarding the completeness of documents furnished, the date of actual physical institution of the audit serves as the definitive baseline for calculating the three-month limitation period for completion.
Background
The petitioner, a company manufacturing pigments and printing ink, was served an audit notice in June 2022 for F.Ys. 2017-18 to 2019-20. Despite multiple submissions of documents via email and pen drives throughout 2022 and 2023, the respondent authorities issued subsequent notices in 2022 and 2024, eventually expanding the scope to include F.Ys. 2021-22 and 2022-23. The respondents alleged that the petitioner failed to provide all requisite documents, leading to the physical institution of the audit only on June 19, 2024.
The petitioner argued that the repeated notices were a strategy to cover up the authorities' failure to complete the audit within the initial statutory period. However, the High Court found that the statutory definition of "commencement" allowed for the later date of physical inspection to be used. Finding no procedural illegality in the timing of the audit report dated August 2, 2024, the Court dismissed the writ petition, granting the petitioner liberty to reply to the show-cause notices or pursue an appeal under Section 107 of the Central Goods and Services Tax Act, 2017.
Case Details:
Case No.: R/SPECIAL CIVIL APPLICATION NO.14772 of 2024
Neutral Citation: 2026:GUJHC:67057-DB
Case Title: Hubergroup India Private Limited Versus Union Of India & Ors.
Appearances:
For the Petitioner(s): MR. S S IYER(6553)
For the Respondent(s): Mr Ankit Shah(6371) for Respondent Nos. 1,2,3,4,5; Mr. Archit P Jani(7304) for Respondent No. 6
Source: 2026 CaseBase(GUJ) 31758
Similar Articles
 Breaking News


