


Adjudicating Authorities Cannot Ignore Final Appellate Orders: Delhi HC
 Copy Link
 Share
 Save
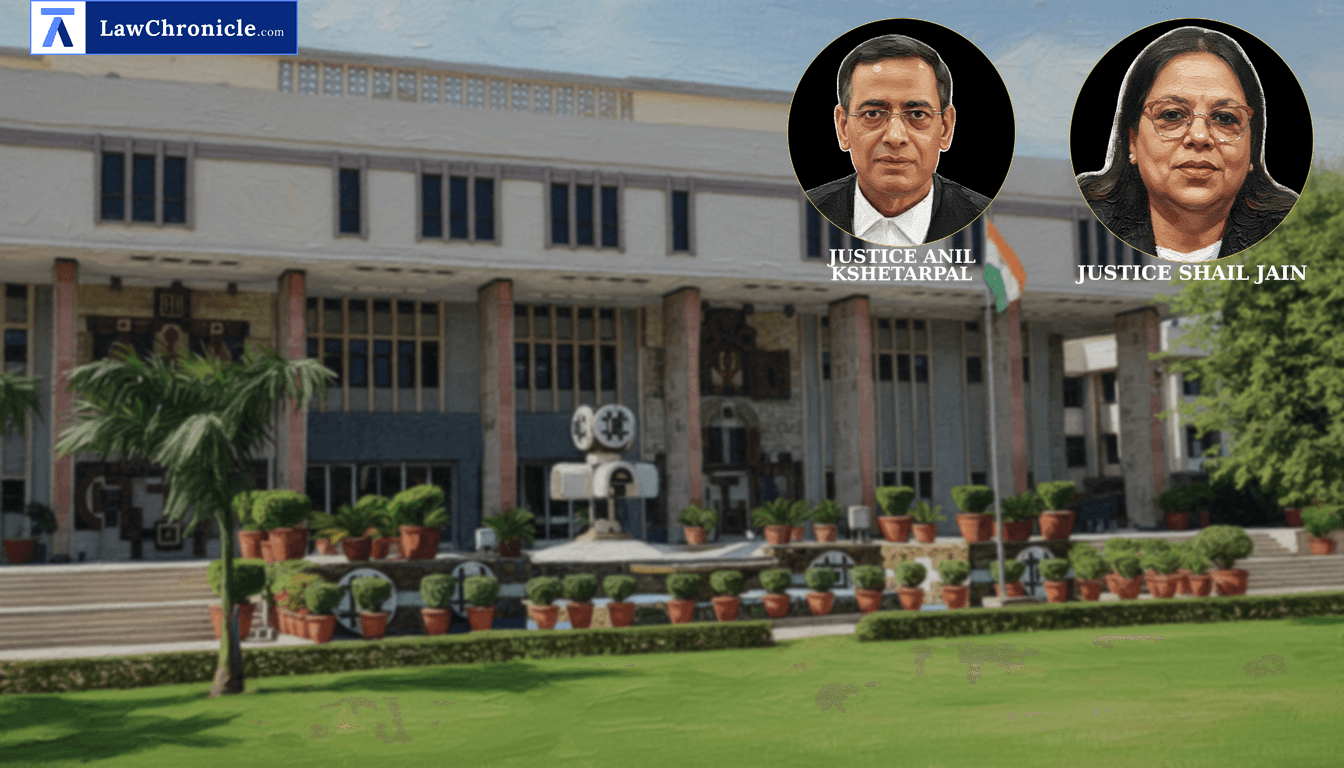
The Delhi High Court has quashed a multi-million rupee tax demand, reinforcing the binding nature of higher tribunal orders over subordinate executive authorities who attempted to revive dead litigation. In a stern rebuke to departmental persistence, the Court ruled that adjudicating officers cannot base their findings on orders that have already been set aside by an appellate tribunal.
A bench comprising Justice Anil Kshetarpal and Justice Shail Jain heard the petition challenging a Demand-cum-Show Cause Notice and a subsequent Order-in-Original that sought to recover a refund previously upheld by the Customs, Excise and Service Tax Appellate Tribunal [CESTAT] Final Order No.56215/2024. The Court examined whether a demand confirmed during the pendency of higher appeals could survive once the underlying basis for the demand was judicially extinguished.
Key Takeaways
- Tribunal Supremacy Upheld
Subordinate adjudicating authorities are legally bound to follow the final determinations of the CESTAT, especially when specifically apprised of such orders. - Res Judicata on Limitation
Once an appellate forum like the CESTAT has expressly ruled that a refund claim is not barred by limitation, the department cannot re-adjudicate or reopen the same issue under the guise of a 'fresh claim'. - Administrative Finality
The Court emphasized that orders accepted by the Competent Authority (Reviewing) and not challenged further attain finality and cannot be circumvented through subsequent parallel proceedings. - Procedural Integrity
Statutory authorities cannot act in ignorance of operative appellate orders, and doing so constitutes a manifest error of law that warrants the invocation of writ jurisdiction.
Invalidity of Demand Based on Extinguished Orders
The High Court observed that the sequence of events was critical, noting that the demand confirmed on March 24, 2025, relied on a 2019 Order-in-Appeal that had already been set aside by the Customs, Excise and Service Tax Appellate Tribunal [CESTAT] Final Order No.56215/2024 in August 2024. The Court noted that the adjudicating authority was specifically informed of the tribunal's final order but chose to disregard it.
The Court, in its reasoning, observed: "An adjudicating authority exercising statutory powers is necessarily required to take into account the operative orders of the appellate authorities having appellate jurisdiction over the adjudicating authority. The adjudicating authority cannot disregard a subsequent appellate determination which directly bears upon the very issue under adjudication."
Furthermore, the Court held that the department’s attempt to treat the refund claim as a "fresh application" to trigger limitation was legally unsustainable. The Court stated: "Once the question of limitation had been specifically considered and decided by the CESTAT in favour of the Petitioner, the Additional Commissioner could not have proceeded to adjudicate the issue by simply treating the refund claim as a fresh claim and arriving at a conclusion contrary to the finding recorded by the CESTAT."
The Court has following directions:
"The Respondent is directed to refund to the Petitioner the amount of Rs.7,67,200/- deposited by the Petitioner as pre-deposit while filing Excise Appeal No.51000 of 2020 before the CESTAT, together with applicable interest, in accordance with law."
Ratio
An adjudicating authority cannot confirm a demand based on a legal or factual premise that has been set aside by a superior appellate forum. Findings on limitation and substantive entitlement rendered by a Tribunal are binding on the department, and any subsequent order passed in ignorance or defiance of such appellate determinations is a manifest error of law and subject to being quashed under Article 226 of the Constitution of India.
Background
The dispute originated from a CENVAT credit claim by Welspring Universal, a 100% Export Oriented Unit. The Petitioner had paid duty on goods purchased from a sister concern and subsequently on exported goods. Despite succeeding in multiple rounds of litigation before the High Court in CEAC No.8/2017 and the Customs, Excise and Service Tax Appellate Tribunal [CESTAT] Final Order No.56215/2024, the Department issued a Demand-cum-Show Cause Notice on December 10, 2019, alleging the sanctioned refund of Rs. 76,72,000/- was erroneous under Rule 5 of the CENVAT Credit Rules, 2004.
The Department argued that the Petitioner should have transitioned credit via TRAN-1 and that the refund was time-barred under Section 11B of the Central Excise Act, 1944. However, the High Court found that the Customs, Excise and Service Tax Appellate Tribunal [CESTAT] Final Order No.56215/2024 had already settled these issues in Customs, Excise and Service Tax Appellate Tribunal [CESTAT] Final Order No.56215/2024, holding the claim was within time and valid under the CENVAT Credit Rules, 2004. The High Court set aside the impugned demand and the show cause notice, allowing the writ petition.
Case Details:
Case No.: W.P.(C) 11957/2025
Case Title: Welspring Universal V. Additional Commissioner Of Central Gst
Appearances:
For the Petitioner(s): Mr. Kunal Sharma and Ms. Rishika Goyal, Advs.
For the Respondent(s): Mr. Brijesh Yadav, SPC with Ms. Nikita, Mr. Sandeep Yadav, Mr. Sawan Saini, Mr. Anirudh Nagar, Mr. Atul Yadav & Mr. Kunal Chaudhary, Advs.
Source: 2026 CaseBase(DEL) 5696
Similar Articles
 Breaking News


