


Blocked ITC Cannot Satisfy Pre-Deposit Requirement Under CGST Act: Delhi HC
 Copy Link
 Share
 Save
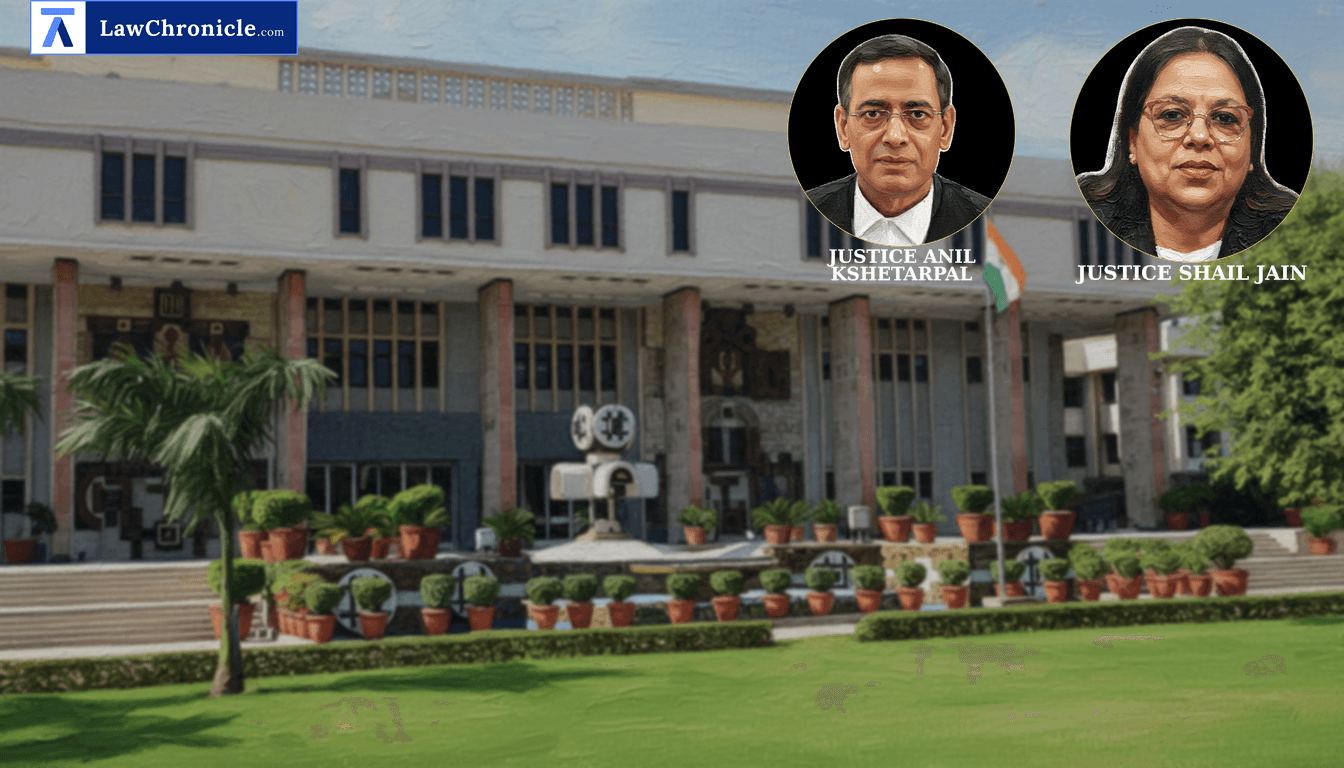
Blocked input tax credit cannot be appropriated towards mandatory statutory pre-deposits, establishing that mere restriction on credit does not equate to tax payment or discharge of liability. Clarifying the operational scope of electronic credit ledgers, the High Court held that taxpayer credit locked under anti-evasion measures cannot be treated as actual debit to fulfill pre-appeal deposit mandates.
A Division Bench comprising Justice Anil Kshetarpal and Justice Shail Jain addressed a writ petition seeking to utilize blocked input tax credit from an Electronic Credit Ledger to meet the ten percent mandatory pre-deposit under Section 107(6) of the Central Goods and Services Tax Act, 2017 for filing a statutory appeal.
Key Takeaways
Blocked Credit Is Not Payment: Placing input tax credit beyond a taxpayer's use under Rule 86A does not constitute payment or appropriation towards an adjudicated demand.
Non-Blocked ECL Funds Usable: Litigants remain free to satisfy mandatory pre-deposits using unencumbered funds lawfully available in their Electronic Credit Ledger.
Necessary Parties Mandatory: Non-impleadment of state tax authorities who imposed credit blocks precludes writ courts from ordering appropriation or modification of those restrictions.
Court's Analysis on Pre-Deposit and Blocked Credit
The court scrutinized the statutory framework under Section 107(6) and Section 49(4) of the Central Goods and Services Tax Act, 2017 alongside Rule 86A of the Central Goods and Services Tax Rules, 2017. While Section 49(4) permits credit usage for output tax, Rule 86A restricts debits when fraudulent availment is suspected. Distinguishing earlier precedents in Oasis Realty v. Union of India and Yasho Industries Limited v. Union of India, the Court noted that those decisions pertained to unencumbered credit rather than blocked funds.
The Court, in its reasoning, observed: "The mere blocking of input tax credit does not amount to its payment or appropriation towards an adjudicated demand. A restriction under Rule 86A only prevents debit of the specified amount from the ECL. Unless the amount is actually debited or appropriated towards the liability, the requirement of pre-deposit cannot be treated as satisfied merely because the credit has been placed beyond the use of the registered person."
Addressing the technical difficulties and procedural errors, the Court issued specific directions to ensure the petitioner is not deprived of the statutory appellate remedy. The Court has following directions:
"42.1. Since the error in FORM GST DRC-07 has admittedly been rectified, the prayer seeking its rectification has become infructuous. Respondent No.1 shall furnish a copy of the corrected FORM GST DRC-07 to the Petitioner within a period of one week, if not already furnished.
42.2. The prayer seeking appropriation of ₹3,33,257/- out of the input tax credit presently blocked under Rule 86A of the CGST Rules cannot be granted in the present Writ Petition. However, the Petitioner shall be at liberty to seek removal or modification of the restrictions dated 03.10.2025 and 02.01.2026 from the competent authority or to challenge the same in appropriately constituted proceedings.
42.3. The Petitioner is permitted to file its Appeal under Section 107 of the CGST Act against the OIO within a period of four weeks from the date of this judgment. If the Appeal is filed within the aforesaid period, it shall not be rejected on the ground of limitation and shall be considered on merits, subject to compliance with Section 107(6) of the CGST Act.
42.4. In terms of the stand taken by the Respondents before this Court, the Petitioner shall not be required to make the pre-deposit exclusively through the Electronic Cash Ledger. The Petitioner may utilise any amount otherwise lawfully available and capable of being debited from its ECL. However, the credit presently blocked under Rule 86A shall not be treated as payment of the pre-deposit unless the concerned restriction is removed or suitably modified by the competent authority.
42.5. Respondent Nos.1 and 3 shall render the necessary assistance to enable the Petitioner to file the Appeal electronically. In case the GST portal continues to prevent filing of the Appeal despite correct completion of FORM GST APL-01 and compliance with Section 107(6) of the CGST Act, the Petitioner shall be permitted to submit the Appeal manually before the competent Appellate Authority, which shall accept and process it in accordance with law.
42.6. No coercive steps for recovery of the demand confirmed by the OIO shall be taken against the Petitioner for a period of four weeks from the date of this judgment. If the Petitioner files the Appeal within the aforesaid period after complying with Section 107(6) of the CGST Act, the consequences contemplated under Section 107(7) shall follow. In case no Appeal is filed within the stipulated period, the protection shall cease automatically."
Ratio
Input tax credit restricted under Rule 86A of the Central Goods and Services Tax Rules, 2017 cannot be treated as payment or appropriated towards the mandatory pre-deposit under Section 107(6) of the Central Goods and Services Tax Act, 2017. Blocking of credit is a preventive restriction on debit, not an actual discharge of tax liability.
Background
The dispute arose after the Directorate General of GST Intelligence investigated alleged non-genuine invoice transactions. A Show Cause Notice culminated in an Order-in-Original confirming an IGST demand of ₹33,32,568/- against the petitioner. However, the summary demand uploaded in FORM GST DRC-07 reflected an erroneous total penalty of ₹66,65,136/-, forcing the GST portal to incorrectly calculate the required 10% pre-deposit at ₹6,66,514/- instead of ₹3,33,257/-.
Although the tax authorities corrected the DRC-07 form under Section 161 of the Central Goods and Services Tax Act, 2017 during the writ proceedings, the petitioner contended that ₹17,96,088/- of its input tax credit remained blocked under Rule 86A by Haryana state authorities. The petitioner requested the court to appropriate ₹3,33,257/- from this blocked credit as pre-deposit to enable the filing of its appeal. The Respondents relied on rulings like Jyoti Construction v. Deputy Commissioner of CT & GST and KOG-KTV Food Products (India) Private Limited v. Joint Commissioner (Appeals) to argue that blocked credit cannot satisfy statutory pre-deposit requirements. The High Court declined to appropriate the blocked credit, citing the absence of the state officers who imposed the restrictions, but granted four weeks to file the statutory appeal with interim protection.
Case Details:
Case No.: W.P.(C) 3418/2026, CM APPL. 16397/2026 & CM APPL. 16398/2026
Case Title: Spherion Solutions Private Limited V. Additional Commissioner Adjudication Cgst Delhi North & Ors.
Appearances:
For the Petitioner(s): Mr. Abhishek Garg, Mr. Ranesh Singh and Ms. Mankotia, Advs.
For the Respondent(s): Mr. Akash Verma, SSC along with Ms Aanchal Uppal and Ms. Teevra Mishra, Advs., Mr. Harpreet Singh, SSC.
Source: 2026 CaseBase(DEL) 5675
Similar Articles

 Breaking News


