


Bombay HC Restrains GST Recovery of Interest During Pending Tribunal Appeals
 Copy Link
 Share
 Save
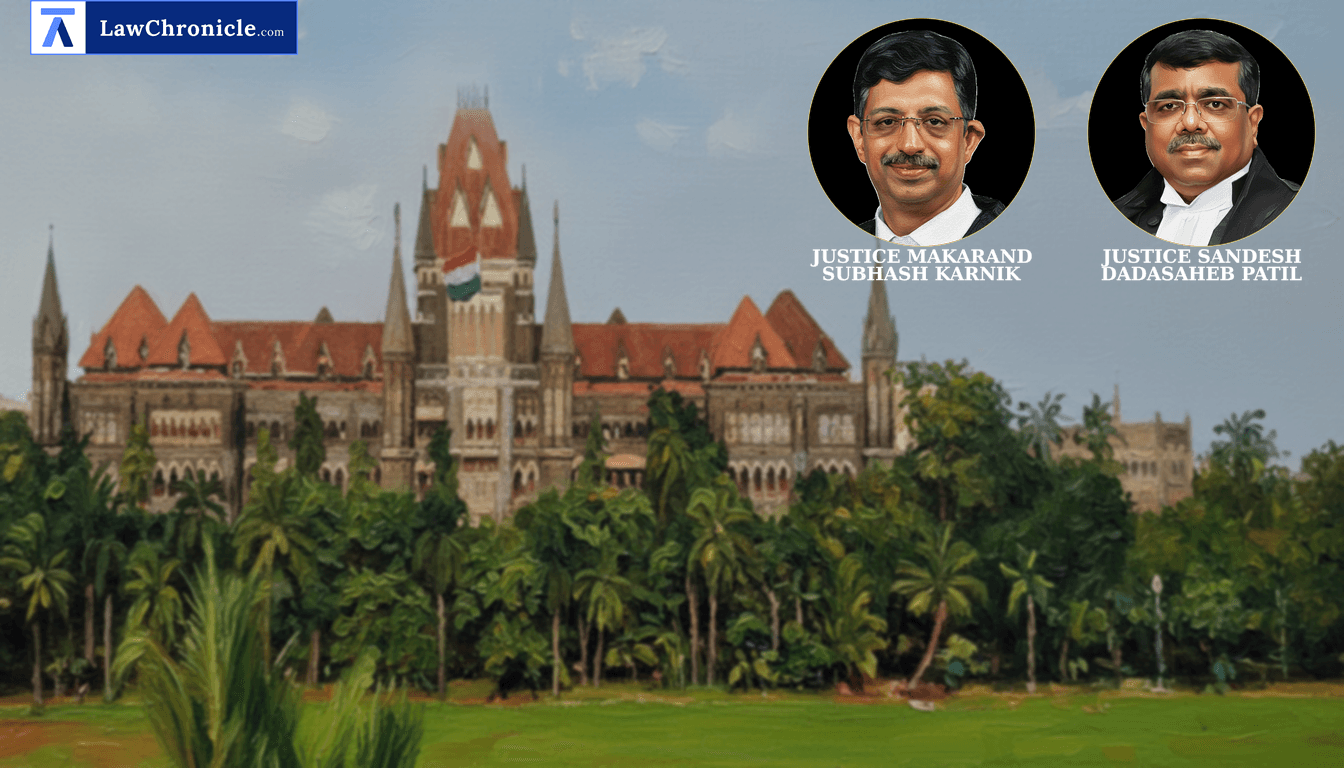
In a decisive check on coercive tax collection, the Bombay High Court has ruled that the GST Department cannot initiate recovery proceedings for disputed interest when the entire tax amount has been paid and an appeal is pending before the Tribunal.
A division bench comprising Justice M. S. Karnik and Justice Sandesh D. Patil adjudicated on the matter. The Bench was hearing a batch of writ petitions challenging bank attachment notices and recovery intimations issued by the State Tax authorities despite the petitioner having filed appeals before the Goods and Services Tax Appellate Tribunal.
Key Takeaways
Statutory Stay on Recovery
Once a taxpayer complies with the pre-deposit requirements under Section 112(8), any further recovery for the balance amount is deemed stayed by operation of law.
Interest Pre-deposit Not Mandatory
The Bombay High Court clarified that there is no legal requirement to pre-deposit disputed interest to maintain an appeal if the entire principal tax amount has already been discharged.
Protection of Banking Operations
The ruling prevents the Department from freezing bank accounts for interest recovery during the pendency of a second appeal, thereby safeguarding the business continuity of litigants.
Court Observations and Directions
The Bombay High Court scrutinized the interplay between the recovery powers under Section 79 of the Central Goods and Services Tax Act, 2017 and the appellate protections. It observed that the legislative intent behind the pre-deposit mechanism was to provide a balance between revenue interest and the taxpayer's right to appeal.
The Bench elaborated that “A reading of Section 107(6) of CGST/MGST Act indicates that the petitioner is required to pre-deposit entire undisputed amount of tax, interest, penalty etc. and 10% of the disputed tax, arising out of the order appealed against... There is no mention of deposit of any amount towards interest, if interest alone is under challenge... we have no hesitation in holding that the percentage-based pre-deposit prescribed by Section 112(8)(b) does not extend to disputed interest alone, especially when the entire tax has been paid.”
Ratio
Under Sections 107(7) and 112(9) of the CGST/MGST Act, once the statutorily required pre-deposit is made, recovery of the balance amount is deemed stayed by operation of law. Furthermore, Section 112(8)(b) does not mandate a percentage-based pre-deposit of disputed interest as a condition for filing an appeal when the underlying tax liability has been fully discharged.
Background
The petitioner, a construction firm engaged in highway projects, was served with show-cause notices alleging delay in depositing tax dues for the periods 2023-26. While the petitioner paid the principal tax, it challenged the subsequent demand for interest. After the First Appellate Authority upheld the interest demand, the petitioner moved the Tribunal. Despite the pendency of these appeals, the Assistant Commissioner of State Tax issued intimations for recovery and directed banks to pay approximately Rs. 22.12 Crores to the Government.
The Revenue argued that interest under Section 50 of the Central Goods and Services Tax Act, 2017 is an automatic statutory levy and compensatory in nature, making it an admitted liability that should be paid regardless of the appeal. However, the Bombay High Court distinguished between admitted tax and disputed interest. Relying on precedents including Evergreen Construction Pvt. Ltd. vs. Commissioner of Commercial Taxes, Tejas Arecanut Traders vs. Joint Commissioner of Commercial Taxes (Appeals), Magnum Estates Pvt. Ltd. vs. Additional Commissioner, GST (Appeals), Bhubaneswar, and Hongkong and Shanghai Banking Corporation Ltd. vs. State of Maharashtra, the Court held that the department's attempt to bypass the statutory stay was illegal.
Case Details:
Case No.: WRIT PETITION NO.14038 OF 2026 with connected matters
Neutral Citation: 2026:BHC-AS:43662-DB
Case Title: Roadway Solutions India Infra. Ltd. v. The State of Maharashtra & Ors.
Appearances:
For the Petitioner(s): Mr. Darius Shroff, Senior Advocate a/w Adv. Parag Khandhar, Adv. Kiran Chavan, Adv. Tapan Radkar i/b. Cenex Legal LLP
For the Respondent(s): Smt. Shruti D. Vyas, Addl.G.P. a/w Mr. A. R. Deolekar, AGP
Source: 2026 CaseBase(BOM) 7131
Similar Articles

 Breaking News


