


Deduction under Section 80IA: Gujarat HC rejects notional set-off of absorbed losses
 Copy Link
 Share
 Save
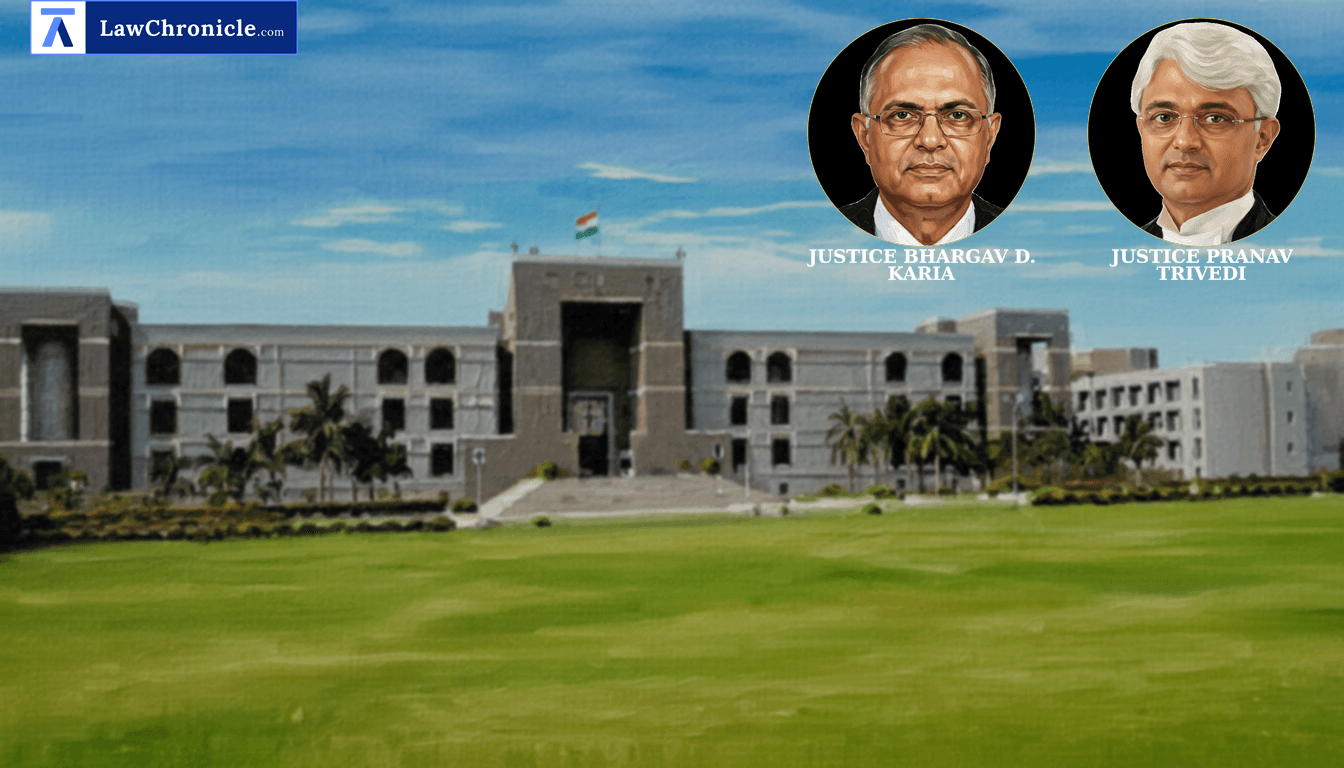
The Gujarat High Court has barred the Revenue from notionally reviving and setting off losses that were already absorbed against other business income in years prior to an assessee's chosen 'initial assessment year' for claiming tax holidays. This authoritative ruling reinforces the assessee’s statutory right to choose the commencement of their tax benefit period without being penalized by past losses that have already been legally adjusted.
A bench comprising Justice Bhargav D. Karia and Justice Pranav Trivedi delivered the judgment in a batch of tax appeals, primary among them being the case of Goldmine Shares and Finance Pvt Ltd. The Court was tasked with determining whether the Income Tax Act, 1961 permits the notional carry forward of losses and depreciation from an eligible business for the purpose of computing Income Tax Act, 1961 deductions, even when such losses were already set off against other income in earlier years.
Key Takeaways
Statutory Option Preserved
Assessees retain the absolute right to choose the initial year for claiming tax benefits within the prescribed window, and the Revenue cannot diminish this benefit by looking backward to revive absorbed losses.
Fiction Limited to Quantum Computation
The deeming fiction that the eligible business is the 'only source of income' applies strictly to the computation of profits during the tax holiday period and does not extend to reviving past, non-existent losses.
Consistency Across High Courts
By aligning with the Madras and Delhi High Courts, this ruling narrows the conflict on tax holiday computations, providing greater certainty for infrastructure and power sector enterprises.
Interpretation of Section 80IA(5) and the 'Only Source' Fiction
The Revenue contended that in view of the non-obstante clause and the deeming fiction in Section 80IA(5) (equivalent to the erstwhile Section 80IA(7)), the eligible business must be treated as the only source of income from its inception. They argued that any loss or depreciation incurred since the start of the business must be notionally brought forward to reduce the current year's profits for deduction purposes, regardless of whether those losses were already utilized against other income streams.
The Court, however, found this interpretation contrary to the plain language of the Income Tax Act, 1961. Relying on the precedent set by Velayudhaswamy Spinning Mills (P.) Ltd. v. Assistant Commissioner of Income-tax, the Court noted that once a set-off has taken place against other income in earlier years, the Revenue cannot 'rework' the set-off amount and bring it back notionally. The Court, in its reasoning, observed: "[T]here is nothing to suggest therein that profits derived by the assessee from the eligible business can be adjusted against notional loss/unabsorbed depreciation which have already been set off against the profits of other business in earlier years... the fiction is created only for the limited purpose and the same cannot be extended beyond the purpose for which it is created."
The Court has the following directions:
"In view of above conspectus of law and for the foregoing reasons, the questions of law are answered in favour of the assessee and against the Revenue. Appeals are accordingly allowed."
Ratio
Losses of an eligible business unit that have been absorbed against the profits of other business units in years prior to the 'initial assessment year' cannot be notionally brought forward and set off against the profits of the eligible business for computing the quantum of deduction under Section 80IA of the Income Tax Act, 1961.
Background
The appellant, a company dealing in shares and securities, established wind mills for electricity generation in Financial Year 1995-96. In the early years, the undertaking incurred significant depreciation which was set off against its share-trading income. The assessee opted to claim the Income Tax Act, 1961 deduction starting from Assessment Year 1997-1998, when the unit turned profitable. The Assessing Officer, however, insisted on notionally bringing forward the depreciation already absorbed in 1996-97 to reduce the profits eligible for deduction in 1997-98 and subsequent years.
The Income Tax Appellate Tribunal's Special Bench had originally ruled in favor of the Revenue. However, the High Court noted that this Special Bench decision was subsequently reversed by Velayudhaswamy Spinning Mills (P.) Ltd. v. Assistant Commissioner of Income-tax and its principles were adopted by the CIT v. Mewar Oil and General Mills Ltd. in PCIT v. Sterling Agro Industries Limited. The Court also referred to Vodafone Essar Gujarat Ltd. v. Assistant Commissioner of Income-tax ( "(2020) 424 ITR 498 (Guj.)": 2020 CaseBase(GUJ) 627) regarding the limited scope of Section 80IA(5) and the Circular No.1/2016 dated 15.02.2016 which clarified the definition of 'initial assessment year'. While acknowledging a contrary view by Microlabs Ltd. v. Assistant Commissioner of Income-tax, Bangalore, the Court chose to follow the line of reasoning that favors the assessee’s statutory choice and prevents the double-counting of losses on a notional basis.
Case Details:
Case No.: R/TAX APPEAL NO. 1521 of 2010
Neutral Citation: 2026:GUJHC:69220-DB
Case Title: Goldmine Shares And Finance Pvt Ltd Versus Assistant Commissioner Of Income Tax
Appearances:
For the Petitioner(s): Mr SN Soparkar Senior Advocate With Mr BS Soparkar With Mrs Swati Soparkar
For the Respondent(s): Mr. Varun K. Patel Senior Standing Counsel
Source: 2026 CaseBase(GUJ) 31970
Similar Articles


 Breaking News


