


Gujarat HC Quashes Reassessment Notice Issued Under TOLA For AY 2015-16
 Copy Link
 Share
 Save
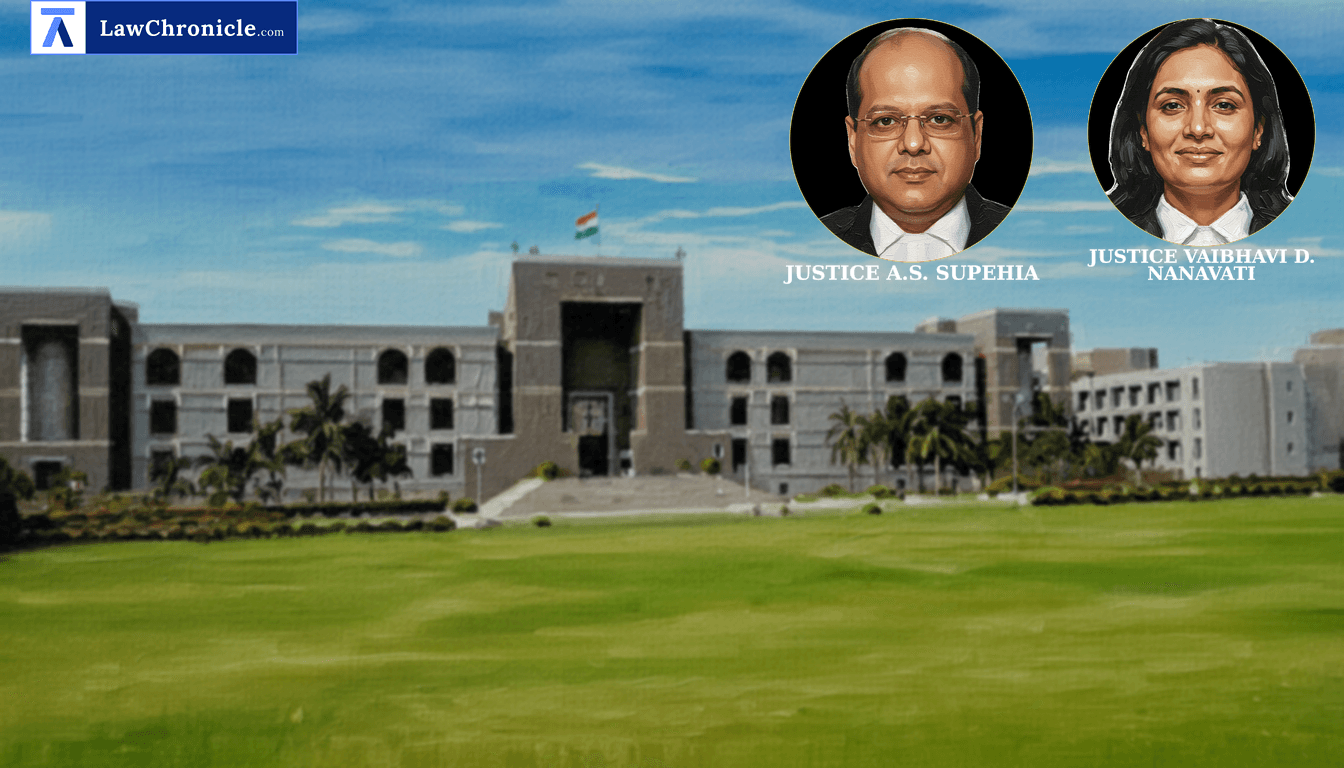
The Gujarat High Court has ruled that reassessment notices issued for the Assessment Year 2015–16 during the extended period under the Relaxation Ordinance are invalid.
A division bench comprising Justice A.S. Supehia and Justice Vaibhavi D. Nanavati heard the challenge against the reopening of assessment under the old regime of the Income Tax Act, 1961. The court examined the interplay between the new reassessment regime introduced in 2021 and the extensions granted under the Taxation and Other Laws (Relaxation of Certain Provisions) Ordinance, 2020.
Invalidity of Notices Issued for AY 2015-2016 During TOLA Extension
The court observed that the Revenue had previously conceded before the Supreme Court that for the Assessment Year 2015-2016, notices issued on or after April 1, 2021, must be dropped as they do not fall within the permissible completion period under Taxation and Other Laws (Relaxation of Certain Provisions) Ordinance, 2020. This position was solidified in the decisions of Union of India Vs. Rajeev Bansal ( "(2024) 469 ITR 46 (SC)": 2024 CaseBase(SC) 945) and Deepak Steel and Power Ltd vs. Central Board of Direct Taxes.
The Court has the following directions:
"The impugned notice issued under Section 148 of the Act, for Assessment Year 2015-2016, is held to be invalid as same was issued during the extended period from 01.04.2021 to 30.06.2021 under TOLA. Accordingly, the present petition is disposed of. Rule is made absolute to the above extent. No order as to costs."
Court's Rationale on Statutory Time Limits
The Court, in its reasoning, observed: "...for the assessment year 2015-2016, all notices issued on or after April 1, 2021 will have to be dropped as they will not fall for completion during the period prescribed under the Taxation and other Laws (Relaxation and Amendment of Certain Provisions) Act, 2020. ...the respondent-Assessing Officer has issued the notice under section 148A(b) of the Act after the period of six years were over on 31.03.2022. ...therefore, nothing further is required to be adjudicated in the matters as the notice so far as the present petitions are concerned, though dated 31.03.2021, admittedly have been issued after 01.04.2021."
Background:
The petitioner, Adesh Enterprise, challenged a notice issued under Section 148 of the Income Tax Act, 1961 for the Assessment Year 2015-2016. The notice was issued on June 30, 2021, following the old reassessment regime, despite the new regime under Section 148A coming into effect from April 1, 2021. The Revenue had relied on Taxation and Other Laws (Relaxation of Certain Provisions) Ordinance, 2020 to extend the time limit for issuing such notices.
However, following the landmark ruling in Union of India and others Vs. Ashish Agarwal ( "(2022) 444 ITR 1 (SC)": 2022 CaseBase(RAJ) 5256), the department treated these notices as show-cause notices under the new Section 148A(b). The petitioner argued that by the time the fresh notices were issued, the statutory six-year limitation period had already expired on March 31, 2022. The court relied on Union of India Vs. Rajeev Bansal ( "(2024) 469 ITR 46 (SC)": 2024 CaseBase(SC) 945), where the Supreme Court noted that for AY 2015-16, the three-year limit ended in 2019 and the six-year limit ended in 2022, making the TOLA extensions inapplicable for these specific periods. The bench also cited similar views taken by various High Courts, including the Delhi High Court in Bhagwan Sahai Sharma Vs. Deputy Commissioner of Income Tax and Lalit Gulati vs. Assistant Commissioner of Income Tax, the Punjab and Haryana High Court in Jay Jay Agro Industries Vs. Income Tax Officer, Ward-I, Karnal & Anr, and the Rajasthan High Court in Shreyansh Mehta S/o Shri Shanti Lal Mehta, Vs. Income Tax Officer, Udaipur. Consequently, the High Court quashed the notice and allowed the petition.
Case Details:
Case No.: R/SPECIAL CIVIL APPLICATION NO. 7313 of 2022
NeutralCitation: 2026:GUJHC:38750-DB
Case Title: ADESH ENTERPRISE Versus UNION OF INDIA & ORS.
Appearances:
For the Petitioner(s): MS VAIBHAVI K PARIKH
For the Respondent(s): MR. KARAN G SANGHANI, Senior Standing Counsel
Source: 2026 CaseBase(GUJ) 312
Similar Articles

 Breaking News


