


Reassessment Based On Bank's System Error Void Ab Initio: Patna High Court
 Copy Link
 Share
 Save
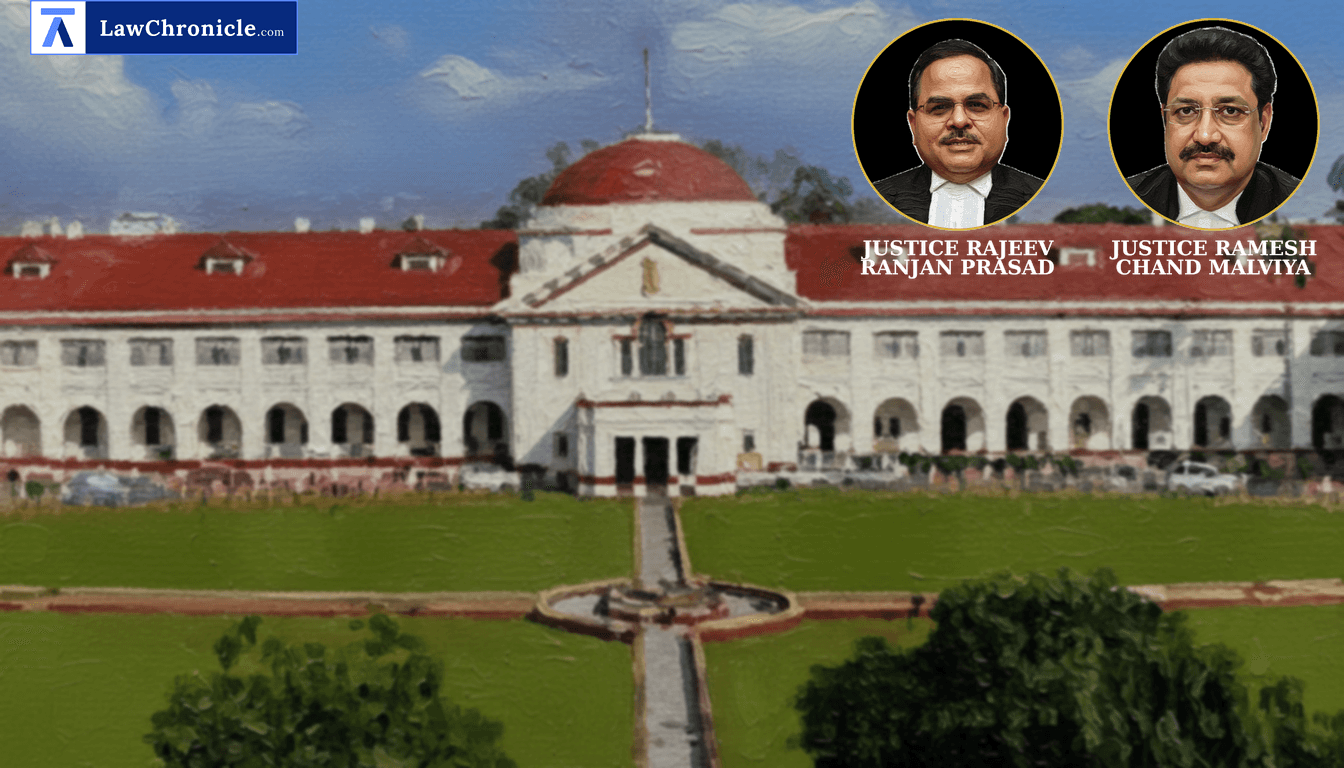
Exposing critical lapses caused by erroneous banking data, the Patna High Court has quashed reassessment proceedings and penalty orders against a senior citizen after discovering that a reported ₹12.5 Crore term deposit was merely a technical glitch for a ₹12.5 Lakh investment.
In a division bench comprising Justice Rajeev Ranjan Prasad and Justice Ramesh Chand Malviya, the High Court adjudicated a writ petition challenging reassessment notices and penalty orders issued under the Income Tax Act, 1961.
Key Takeaways
- Erroneous Data Nullifies Reassessment: Reassessment proceedings based on demonstrably wrong information supplied by financial institutions lack jurisdiction.
- Strict Thresholds for Extended Limitation: Reopening assessments beyond three years requires genuine evidence of escaped income exceeding ₹50 Lakhs under Section 149(1)(b) of the Income Tax Act, 1961.
- Financial Accountability on Banks: The Court imposed litigation costs directly on the reporting bank for initiating erroneous tax demands through system errors.
Invalidation of Reassessment and Judicial Findings
The Patna High Court observed that the show-cause notice issued under Section 148A(b) of the Income Tax Act, 1961 was founded entirely on incorrect data transmitted by the bank, which falsely reflected a deposit of ₹12.50 Crores instead of ₹12.50 Lakhs.
The Court has following directions:
"In view of the discussions made hereinabove, we set aside the impugned orders in terms of the prayers made in the writ application. It is evident that the petitioner had to suffer by way of not only mental agony, but also monetary implications in fighting the case due to a wrong information furnished by respondent no.4, which was made basis for initiation of the action by respondent no.2, we are of the considered opinion that the petitioner deserves cost of litigation which we assess at Rs.25,000/-. The respondent no.4 shall be liable to pay Rs. 25,000/- by way of cost of litigation to the petitioner within six weeks from today, failing which the same will be realised in accordance with law."
The Court, in its reasoning, observed: "On the facts appearing from the records, there is no iota of doubt to this court that no effective show-cause notice under section 148A(b) of the Act of 1961 was served upon the petitioner. The fact that the petitioner did not respond to the show-cause notice dated March 23, 2022 would not make the show-cause notice good and compliant with the requirement of law. After coming into force of the Finance Act, 2021 the respondents could have issued a notice under section 148 of the Act of 1961, if the condition prescribed under section 149(1)(b) would have been satisfied."
Ratio
A show-cause notice issued under Section 148A(b) of the Income Tax Act, 1961 based on demonstrably false or erroneous information does not constitute an effective or legal show-cause notice. Where the actual income escaping assessment is under ₹50 Lakhs, reopening proceedings beyond the normal limitation period of three years under Section 149(1)(b) of the Income Tax Act, 1961 is entirely without jurisdiction and void ab initio.
Background
The petitioner, a senior citizen, received an ex-parte assessment order under Section 147 read with Section 144 and Section 144B of the Income Tax Act, 1961, along with penalty notices under Sections 271(1)(b), 271F, and 271(1)(c). The proceedings originated from an automated signal indicating a term deposit of ₹12,50,00,000/- for Assessment Year 2015-16 supplied by Union Bank of India.
Upon receiving penalty notices, the petitioner approached the bank, which issued a formal certificate acknowledging that the ₹12.5 Crore transaction entry was a "technical error or system fault" and that the actual deposit was only ₹12,50,00/-. The petitioner argued that because the actual escaped income was well below the ₹50 Lakh threshold required by Section 149(1)(b) of the Income Tax Act, 1961 as amended by the Finance Act, 2021, the reopening beyond three years was time-barred.
The petitioner also referred to procedural non-compliances under Section 151A inserted by the Taxation and Other Laws (Relaxation and Amendment of Certain Provisions) Act, 2020 and relied on precedents including Ankit Agarwal vs. The Principal Chief Commissioner of Income Tax, Union of India vs. Rajeev Bansal ( "[2024] 469 ITR 46 (SC)": 2024 CaseBase(SC) 945), Union of India and Others vs. Ashish Agarwal ( "(2023) 1 SCC 617": 2022 CaseBase(SC) 682), Kankanala Ravindra Reddy vs. The Income Tax Officer and Others, and Ganesh Dass Khanna v. ITO.
The High Court held that since the foundation of the notice was erroneous, the extended limitation period was inapplicable. Consequently, the High Court quashed the notice under Section 148A(b), the order under Section 148A(d), the notice under Section 148, the assessment order, and all consequential penalty proceedings, while directing the bank to pay ₹25,000 as litigation costs.
Case Details:
Case No.: Civil Writ Jurisdiction Case No.16288 of 2024
Case Title: Satya Narayan Jha v. Principal Chief Commissioner of Income Tax Bihar and Jharkhand and Ors.
Appearances:
For the Petitioner(s): Mr. Aman Raja, Advocate
For the Respondent(s): Mrs. Archana Sinha, Sr. Advocate; Mrs. Shilpi Keshri, Advocate; Mr. Alok Kr. Shahi, Advocate; Ms. Richa Rajiv Singh, Advocate; Ms. Komal, Advocate; Ms. Swarna Roy, Advocate (for Resp Nos. 1 to 3); Mr. Prashant Kumar, Advocate; Mr. Nishant Kumar, Advocate; Ms. Kritika Upadhya, Advocate (for Resp No. 4)
Source: 2026 CaseBase(PAT) 83
Similar Articles

 Breaking News


