


PC Act | Prosecution Not Bound To Conduct Roving Probe Into Undisclosed Income: SC
 Copy Link
 Share
 Save
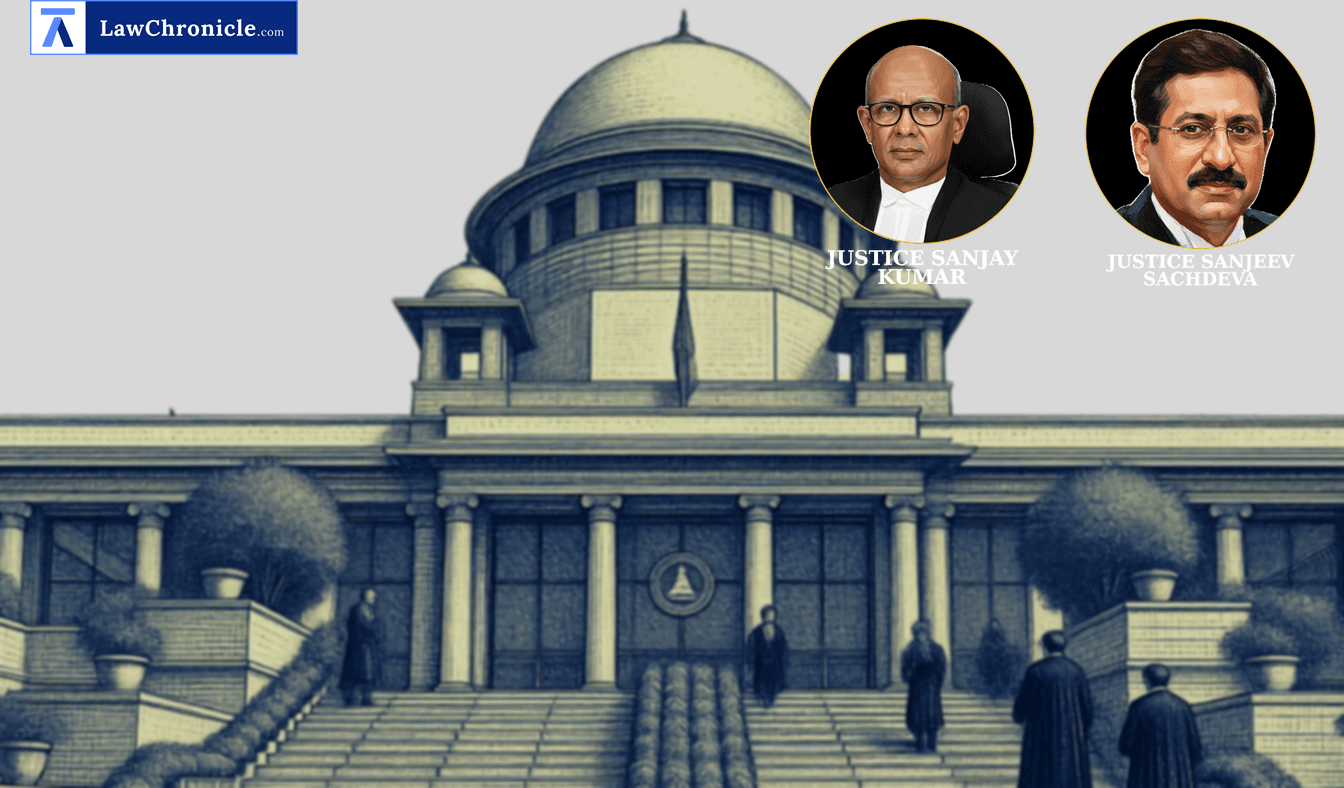
The Supreme Court has settled that public servants facing corruption charges cannot shift the onus onto investigating agencies to unearth secret, undisclosed income sources to explain wealth far exceeding their legal earnings. The Apex Court has ruled that law enforcement is not obligated to conduct open-ended or roving inquiries into unrecorded income to disprove disproportionate assets claims in corruption cases.
A Division Bench comprising Justice Sanjay Kumar and Justice Sanjeev Sachdeva delivered the judgment while dismissing an appeal filed by a former Sub Registrar against his conviction for possessing disproportionate assets.
Key Takeaways
End of Roving Inquiries: Investigating agencies are only required to probe known, legally declared sources of income, relieving them from disproving hypothetical financial claims.
Onus on Accused Public Servant: Once initial disproportion is established by the prosecution, the burden squarely rests on the accused to prove legitimate acquisition using contemporaneous and credible records.
Strict Application of 10% Margin: The 10% buffer allowed in precedent for asset appreciation is an upper ceiling and cannot be expanded to condone higher margins of unexplained wealth.
Burden of Proof and Scope of Investigation
The Supreme Court underscored the statutory framework governing disproportionate assets under Section 13(1)(e) of the Prevention of Corruption Act, 1988. The Bench affirmed that while the prosecution must establish the initial foundational facts, the burden of accounting for disproportionate wealth lies strictly with the public servant. The Apex Court observed that "The statutory framework does not contemplate an open-ended, limitless, or roving enquiry obliging the investigating agency to explore every possible avenue of income that may be imagined or claimed by the accused. Such a construction would impose an impracticable burden upon the prosecution and would permit an accused public servant to defeat the objective of the provision merely by advancing speculative or belated claims regarding undisclosed sources of income."
Addressing the evidentiary burden under Section 109 of the Bharatiya Sakshya Adiniyam, the Bench emphasized that facts regarding undisclosed assets are within the special knowledge of the accused. Highlighting the principles from State of Tamil Nadu. Versus R. Soundirarasu and P. Nallamal & Anr. versus. State, the Supreme Court reinforced that the prosecution's mandate is limited to investigating lawful sources known through official returns and records. Furthermore, the Bench reiterated that the legislature deliberately used the term "satisfactorily account" to cast a heavy burden on the public servant, drawing upon State of Madhya Pradesh versus Awadh Kishore Gupta ( "(2004) 1 SCC 691": 2003 CaseBase(SC) 837). Distinguishing the relief margin, the Court referenced B.C. Chaturvedi versus Union of India ( "(1995) 6 SCC 749": 1995 CaseBase(SC) 611) to reiterate that the 10% allowance laid down in Krishnanand Agnihotri versus State of Madhya Pradesh due to inflationary trends cannot be stretched beyond its limits to cover massive percentage gaps in income and assets.
Ratio
Under Section 13(1)(e) of the Prevention of Corruption Act, 1988, the prosecution's obligation to investigate 'known sources of income' is restricted to lawful sources declared or reasonably ascertainable through official records. Once the prosecution establishes a prima facie disproportion between known sources of income and accumulated assets, the evidentiary burden shifts entirely to the accused public servant under Section 109 of the Bharatiya Sakshya Adiniyam to satisfactorily account for the excess through credible evidence. The prosecution is not required to conduct roving or open-ended inquiries into undisclosed or unrecorded sources of income asserted by the accused.
Background
The dispute originated from an investigation initiated on January 15, 2001, by the Vigilance and Anti-Corruption Bureau against the appellant, who joined government service as a Lower Division Clerk in 1971 and rose to the position of Sub Registrar in 1993. The prosecution alleged that during the check period between January 1, 1993, and January 16, 2001, the appellant acquired assets disproportionate to his known sources of income.
According to the prosecution's basic statements, the appellant and his family held assets worth Rs. 1,93,898.26 at the start of the check period, which rose to Rs. 12,37,720 by the end of the period. Total income was calculated at Rs. 10,12,117.20, while expenditures stood at Rs. 4,93,424. Consequently, the net disproportionate assets were computed at Rs. 5,25,129, amounting to 51.88% above the known income.
The Special Judge convicted the appellant under Section 13(2) read with Section 13(1)(e) of the Prevention of Corruption Act, 1988, sentencing him to two years of rigorous imprisonment and a fine of Rs. 5,50,000. On appeal, the High Court confirmed the conviction but reduced the sentence to one year of rigorous imprisonment and a fine of Rs. 2,00,000, considering the delay in proceedings and the age of the appellant.
Before the Supreme Court, the appellant contested the valuation of a commercial-cum-residential building and household expenses, claiming his expenditure was lower and relying on a private notebook seized during searches. The Apex Court rejected the unverified notebook entries and noted that even after hypothetically accepting all reductions claimed by the appellant, the disproportionate assets remained at over 26% above known income, far exceeding any permissible threshold. Finding no legal infirmity in the lower court judgments, the Supreme Court dismissed the appeal.
Case Details:
Case No.: Criminal Appeal No. 5399 of 2025
Neutral Citation: 2026 INSC 1172
Case Title: V. Gopalakrishnan v. The State of Kerala
Source: 2026 CaseBase(SC) 9510
Similar Articles
 Breaking News


