


SC Rules Amalgamated Company Cannot Claim Predecessor Losses Without Statutory Basis
 Copy Link
 Share
 Save
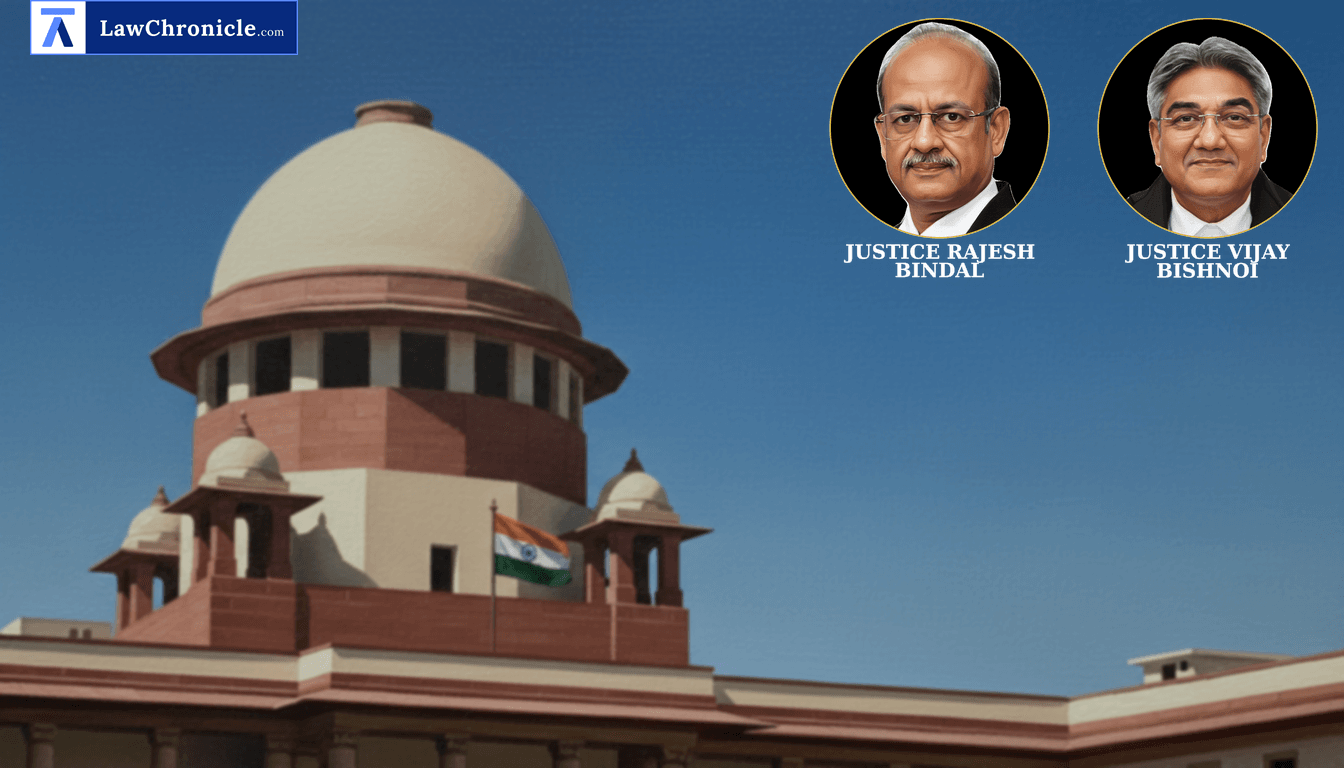
A bench of Justice Rajesh Bindal and Justice Vijay Bishnoi heard consolidated appeals challenging High Court orders that upheld tribunal rulings on entitlement to set off of accumulated agricultural losses following a scheme of amalgamation.
The Court dismissed the appeals and clarified the limited scope on which an amalgamated company could claim carry forward of agricultural losses. The bench held that the appellant’s primary contention based on the scheme clause and the absence of objection did not override statutory limits under the applicable taxation law and that factual findings on limitation of carry forward remained intact.
The Court, in its reasoning, observed: "The facts in the present case are distinguishable. Neither there is any statutory requirement for issuing notice to the State Government before any scheme of amalgamation is approved by the Court under the Companies Act, 1956 nor such notice was issued. Hence, to state that the judgment in Dalmia Power Ltd. and Another v. Assistant Commissioner of Income Tax covers the case of the appellant, is misconceived and deserves to be rejected. Ordered accordingly."
Background
The appeals arose from five civil appeals in which a scheme sanctioned in November 2006 effected the amalgamation of Pullangode Rubber & Produce Co. Ltd. into the appellant company with an appointed date of 01.01.2006. The appellant contended that Clause 14.2 of the scheme "With effect from the Appointed Date, all the profits or Income accruing or arising to PRPL or expenditure or losses arising or incurred by PRPL shall, for all purposes, be treated as and shall deemed to accrue as the profits or income or expenditure or losses, as the case may be, of Aspinwall & Co." entitled the amalgamated company to setoff accumulated losses of the amalgamating company. The appellant relied on the proposition that an approved scheme binds parties where no objection was taken during sanction proceedings and placed primary reliance on Dalmia Power Ltd. and Another v. Assistant Commissioner of Income Tax. The respondent countered that statutory provisions governed succession and carry forward, that no notice had been served on the State of Kerala during the amalgamation process, and that the Kerala regime did not permit the claimed set‑off where the loss bearing entity had ceased to exist or where the loss related to a period beyond the limitation period.
The Court analysed provisions of the Kerala Agricultural Income Tax Act, 1991, notably Section 12 which prescribed carry forward of losses "but no loss shall be carried forward for more than eight years," and Section 54 dealing with succession to business, and contrasted those with Section 72A of the Income Tax Act, 1961 which specifically addresses carry‑forward in certain amalgamation contexts under central income tax law. The bench found that the statutory text of the Kerala Agricultural Income Tax Act, 1991 did not provide for the broad set off claimed by the appellant and observed that the factual finding of the High Court that the relevant loss pertained to a period beyond eight years was not specifically challenged before this Court. The Court further noted that the judgment in Dalmia Power Ltd. and Another v. Assistant Commissioner of Income Tax was founded on circumstances where statutory notice and objection procedures applicable in that company‑law regime had produced no objection, a factual matrix distinguishable from the present case.
The Court also recorded that the appellant had relied heavily on Clause 14.2 of the scheme but had not identified any provision in the Kerala Agricultural Income Tax Act, 1991 that permitted an entity which had not itself incurred the loss to claim carry forward beyond the statutory period. The respondent relied on precedents including General Radio & Appliances Co. Ltd. v. M.A. Khader, Saraswati Industrial Syndicate Ltd. v. CIT, Singer India Limited v. Chander Mohan Chadha and Others ( 2004 INSC 447: 2004 CaseBase(SC) 1099), CIT v. Maruti Suzuki (India) Ltd. and Religare Finvest Ltd. v. State (NCT of Delhi) to support the proposition that statutory limits and succession rules governed assessment and recovery, and to distinguish the central income‑tax provision in Section 72A of the Income Tax Act, 1961 from the Kerala statute.
In conclusion the Court dismissed the appeals, affirmed the High Court’s acceptance of the tribunal’s findings and declined to give effect to the scheme clause as displacing statutory limitations. The Court recorded: "There shall not be any order as to costs." The appeals were dismissed and pending applications were disposed of.
Case Details:
Case No.: CIVIL APPEAL NOS. 7796 OF 2012, 6617 OF 2019, 13454 OF 2015, 13455 OF 2015, 19865 OF 2017
NeutralCitation: 2026 INSC 359
Case Title: Aspinwall and Co. Ltd. v. Inspecting Assistant Commissioner
Appearances:
For the Petitioner(s): Mr. S. Ganesh, learned senior counsel
For the Respondent(s): Mr. Pallav Shishodia, learned senior counsel
Source: 2026 CaseBase(SC) 319
Similar Articles

 Breaking News


