


Tax Recovery Without Assessment Order Service Is Illegal: Delhi High Court
 Copy Link
 Share
 Save
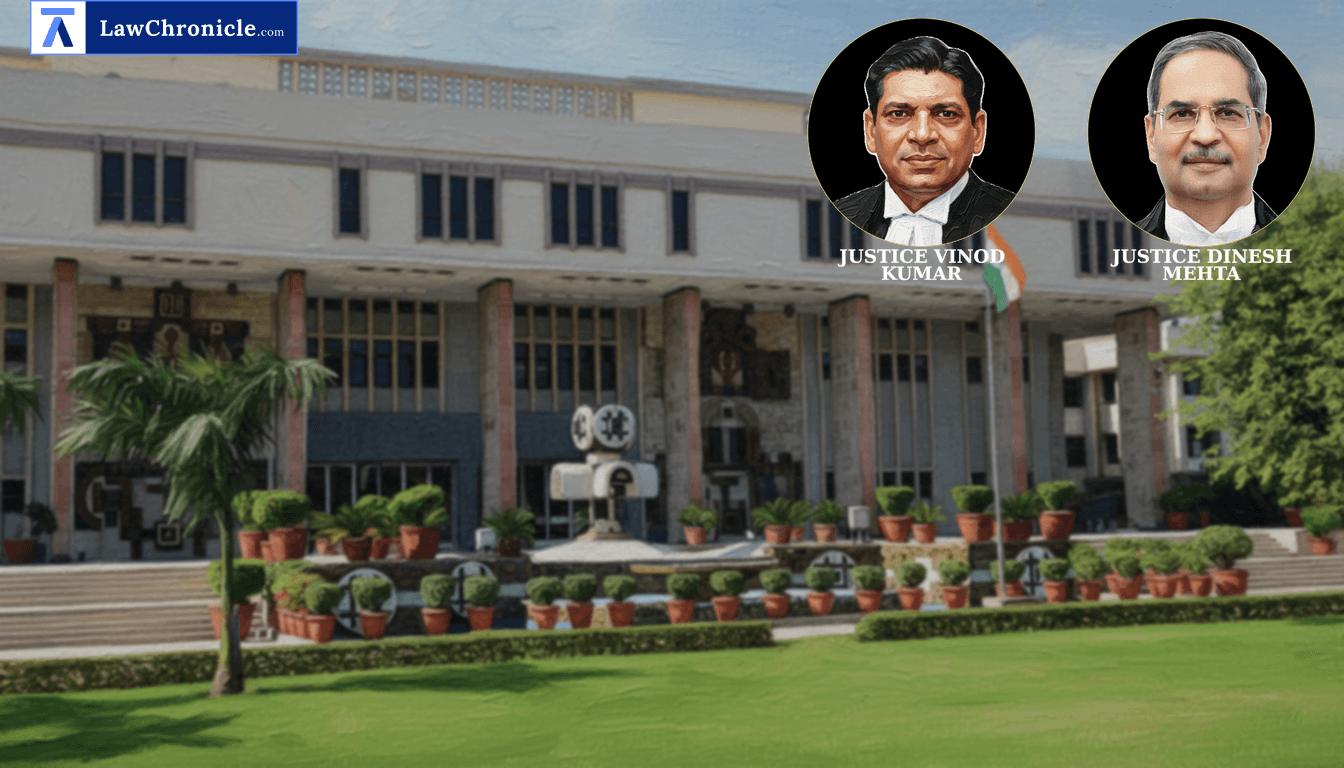
The Delhi High Court has declared that any recovery of tax demand by the Income Tax Department without the formal service of an assessment order or a demand notice is an action devoid of the authority of law. Rebuking the revenue's reliance on 'untraceable' records post-digitization, the Court mandated the refund of seized amounts if the Department fails to prove the existence and service of the original assessment order by a fixed deadline.
A bench comprising Justice Dinesh Mehta and Justice Vinod Kumar heard the plea challenging the recovery of over Rs. 11 lakh from a taxpayer's refunds across multiple subsequent years. The Bench observed that while administrative transitions to digital databases might explain certain delays, they cannot serve as a shield for the Department's failure to provide foundational legal documents justifying a financial liability.
The Requirement of Legal Authority for Tax Recovery
The petitioner approached the court under Article 226 of the Constitution of India, 1950, aggrieved by the recovery of Rs. 11,14,660/- from refunds spanning 2010 to 2017. This recovery pertained to an alleged demand for the Assessment Year (AY) 2001-02. The petitioner contended that despite multiple representations and applications under the Right to Information Act, 2005, the Department failed to provide the assessment order or the demand notice required under Section 156 of the Income Tax Act, 1961.
The Department argued that the records were difficult to trace due to digitization and that the petitioner had failed to update their address in the PAN database. However, the Court noted that once the petitioner requested the order following the recovery, the respondents were duty-bound to supply it.
Court Directs Refund and Fixed Timeline for Compliance
The Court expressed that the continuous failure to produce the assessment order, even under judicial direction, rendered the recovery illegal. The Court has the following directions:
"1. We hereby direct respondent No.1 to refund the amount of Rs.11,14,660/- along with interest to the petitioner in accordance with law latest by 31.03.2026.
2. In case, respondent No.1 is able to trace out and serve a copy of the assessment order (whereby the demand to the tune of Rs.11,14,660/- was raised against the petitioner) by 31.03.2026, the amount of Rs.11,14,660/- shall not be required to be refunded.
3. If the assessment order has been served upon the petitioner, it shall be free to challenge the same by way of filing an appeal under Section 246(A) of the Act of 1961, within a period of 30 days of service of the assessment order.
4. Until 31.03.2026, no further recovery shall be made by Centralised Processing Centre (CPC) from the petitioner in relation to the purported demand of AY 2001-02."
The Court, in its reasoning, observed: "Recovery of the amount from the petitioner and not supplying copy of the order amounts to recovery without authority of law. As the petitioner has been trying hard to get a copy of the assessment order and even pursuant to orders passed by this Court, the respondents have failed to provide a copy of the same."
Key Takeaways:
Statutory Compliance Over Administrative Lapses
The Department cannot justify the absence of an assessment order by citing digitization hurdles; the legal right to recover taxes must be backed by a traceable and served order.
Mandatory Service of Assessment Orders
The court reinforced that without the service of a demand notice under Section 156, no valid statutory liability is created against a taxpayer.
Protection Against Arbitrary Set-offs
Income Tax authorities are restricted from setting off refunds against historical demands if they cannot substantiate the legitimacy of those demands with actual documentation.
Ratio Decidendi:
The recovery of tax amounts from a taxpayer without the service of a valid assessment order or a demand notice under Section 156 of the Income Tax Act, 1961 is an exercise of power without the authority of law. The Department's failure to provide a copy of the assessment order upon request, especially after recovery has been initiated, entitles the taxpayer to a refund of the recovered amounts.
Background:
The dispute originated from tax recoveries made between 2010 and 2017 regarding a demand allegedly raised for AY 2001-02. The petitioner, Philco Exports Private Limited, discovered these deductions only after seeking information through the Right to Information Act, 2005 in 2019. Despite several legal prompts, the Assistant Commissioner of Income Tax could not produce the original assessment order, citing that the record was 'not easily traceable' following the Department’s shift to digital systems. The Court held that regardless of the petitioner's failure to update their PAN address, the Department's inability to provide the order post-recovery constituted a violation of law. The writ petition was disposed of with the direction to refund the amount plus interest by March 31, 2026, unless the order is traced and served before then.
Case Details:
Case No.: W.P.(C) 12318/2021, CM APPL. 38748/2021(stay)
Case Title: Philco Exports Private Limited V. Assistant Commissioner Of Income Tax, & Ors.
Appearances:
For the Petitioner(s): Mr. Somil Agarwal, Mr. Dushyant Agarwal, Advs.
For the Respondent(s): Mr. Sunil Agarwal, SSC, Ms. Priya Sarkar, JSC, Mr. Anugrah Dwivedi, Adv.
Source: 2026 CaseBase(DEL) 546
Similar Articles
 Breaking News


