


Income Tax Dept Must Refund Tax Dues Recovered From Mining Lease Holders: Chhattisgarh HC
 Copy Link
 Share
 Save
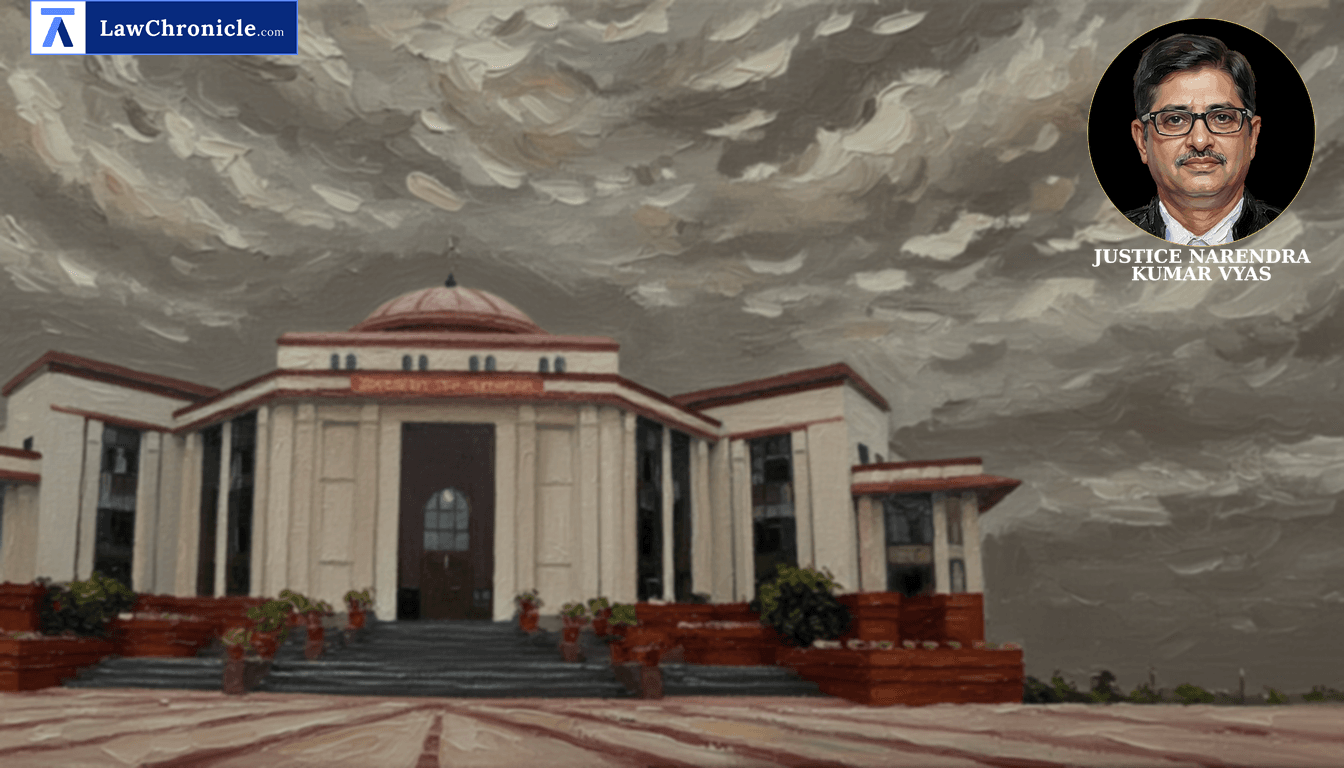
The Chhattisgarh High Court has ordered the Income Tax Department to refund tax amounts recovered from mining lease holders after the underlying tax demand against the State Mining Department was quashed by a Division Bench. Justice Narendra Kumar Vyas heard a bunch of writ petitions filed under Constitution of India by cement manufacturing companies. The petitioners challenged the refusal of the State to adjust or refund advance royalty payments that were essentially intercepted by the Income Tax Department to satisfy alleged tax dues of the Mining Department.
Key Takeaways
Protection of Lease Holders
Lease holders cannot be penalized for the tax defaults of the State Mining Department, especially when such demands have been judicially invalidated.
Direct Refund Mechanism
Tax authorities must return recovered amounts directly to the source entity if the primary recovery notice issued under Section 226(3) of the Income Tax Act loses its legal basis.
Judicial Consistency
Single-judge benches must align relief with the findings of Division Benches to ensure legal certainty in tax disputes involving state instrumentalities.
Court Observations and Directions
The Chhattisgarh High Court noted that the entire premise of the recovery from the petitioners was a notice issued under Section 226(3) of the Income Tax Act because the Mining Department had allegedly failed to deposit Tax Collected at Source (TCS) on royalty payments. However, the State had successfully challenged this demand in The Deputy Director (Geology and Mining) 1st Floor, Collectorate Parisar, Kutcheri Chowk, Raipur CG vs. The Deputy Commissioner of Income Tax (Tds) Raipur, CG and other connected matters, where the Division Bench quashed the demand raised against the Mining Department.
The Bench observed that “In view of the fact that since Tax cases preferred by the Mining Department has been allowed by the Division Bench of this Court wherein demand so raised against the Mining Department has already been quashed, it is directed that if any amount has already been recovered by the Income Tax Department against the petitioners, the same shall be returned back to the petitioners on furnishing the application by the individual petitioners.”
Ratio
When a tax demand raised against a primary entity (the State Mining Department) is quashed by a competent court, any consequential recovery made from third parties (lease holders) under Section 226(3) of the Income Tax Act becomes legally unsustainable and must be refunded upon application.
Background
The petitioners, including Ultratech Cement Limited and Shree Cement Limited, are engaged in cement manufacturing and hold mining leases for limestone. Under the Mines & Minerals Regulations & Development Act, 1957 and related rules, they pay royalty to the State's Mining Department. In 2018, the Income Tax Department issued orders under Section 206C of the Income Tax Act, alleging that the Mining Department failed to collect TCS on these royalties. Consequently, the tax authorities issued notices under Section 226(3) of the Income Tax Act to the petitioners to recover the dues directly from the royalty amounts payable to the State.
The petitioners sought refund or adjustment of these payments from the State, which was rejected via a letter dated January 4, 2021. However, during the pendency of these petitions, the Division Bench in The Deputy Director (Geology and Mining) 1st Floor, Collectorate Parisar, Kutcheri Chowk, Raipur CG vs. The Deputy Commissioner of Income Tax (Tds) Raipur, CG and other connected matters ruled in favor of the Mining Department, quashing the tax demand. Following this development, the Chhattisgarh High Court disposed of the writ petitions, directing the Income Tax Department to return the recovered funds.
Case Details:
Case No.: WPT No. 76 of 2021 (and connected matters)
Neutral Citation: 2026:CGHC:45671
Case Title: Ultratech Cements Limited vs. Union of India and Others
Appearances:
For the Petitioner(s): Mr. Ashish Shrivastava, Sr. Advocate with Mr. Aman Pandey, Mr. Rahul Ambast, Ms. Shotabdi Bageli and Mr. Ishaan Singh Rathore, Advocates; Mr. Raja Sharma, Advocate.
For the Respondent(s): Mr. Ramakant Mishra, Deputy Solicitor General; Ms. Anuradha Jain, Dy. Govt. Advocate; Mr. Ajay Kumrani, Advocate.
Source: 2026 CaseBase(CTH) 21286
Similar Articles
 Breaking News


