


Assessee Entitled To Pre-Deposit Refund To Extent Demand Dropped: Bombay HC
 Copy Link
 Share
 Save
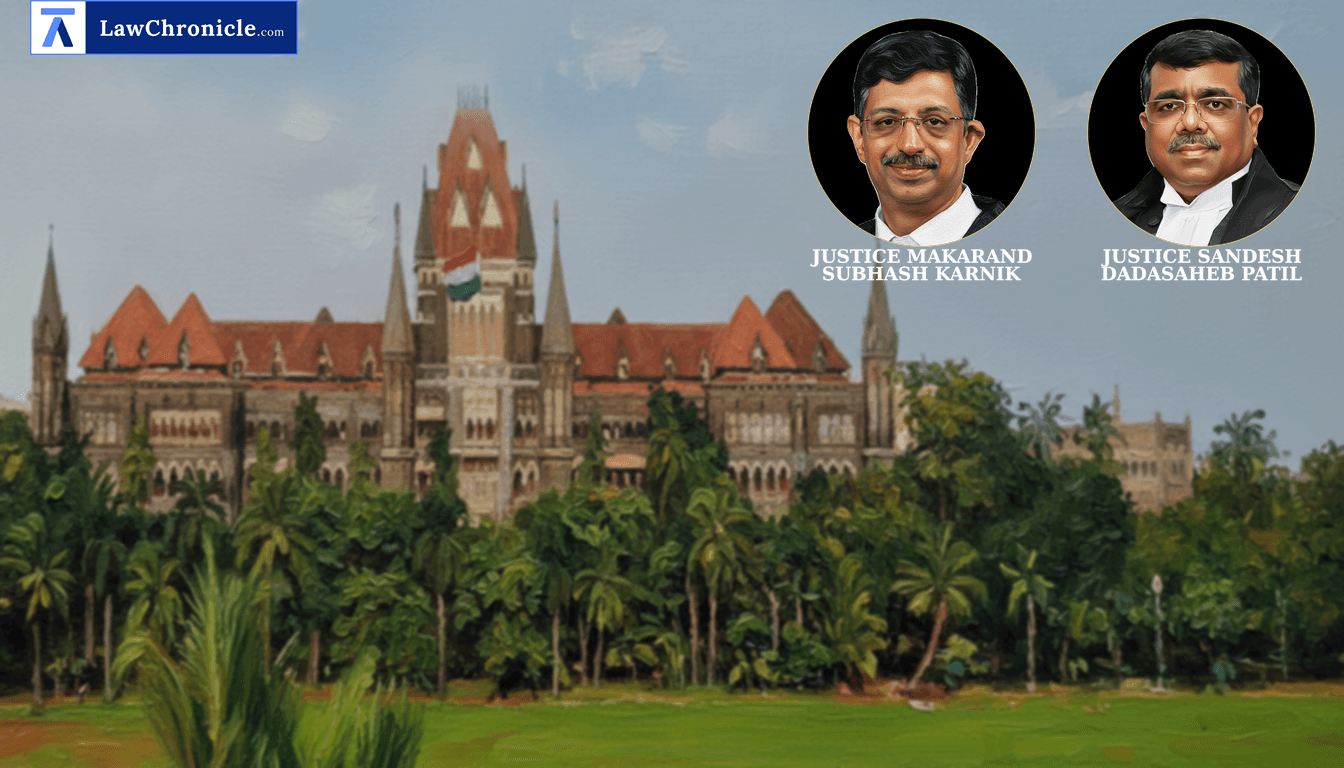
In a major relief for taxpayers, the Bombay High Court has ruled that the continued retention of a statutory pre-deposit by revenue authorities after a tax demand is partially dropped in appeal violates Constitution of India and creates an immediate statutory right to a refund.
A Division Bench comprising Justice M. S. Karnik and Justice Sandesh D. Patil quashed an order of the Deputy Commissioner of State Tax that had rejected a refund application filed by an assessee following a successful partial appeal under the Maharashtra Goods and Services Tax Act, 2017.
Key Takeaways
Partial Success Triggers Refund: Taxpayers are entitled to a proportionate refund of pre-deposits to the extent the tax demand is dropped by appellate authorities.
Intention To Appeal Is Irrelevant: The Revenue cannot withhold a refund for dropped demands merely because the assessee intends to challenge the remaining confirmed demand before a higher tribunal.
Pre-Deposit Is Security, Not Duty: Amounts paid as a statutory condition precedent for hearing an appeal bear the character of a security deposit and must be returned upon success.
Constitutional Bar On Retention: Unauthorized retention of pre-deposits post-adjudication offends the mandate of Constitution of India.
Court's Observations and Legal Rationale
The High Court observed that the tax authorities proceeded on an entirely erroneous footing by claiming the appellate proceedings had not attained finality. The Bench clarified that the assessee proposed to challenge only the part of the order that went against it, while the portion of the demand dropped by the appellate authority had attained complete finality as the Revenue filed no appeal against it.
The Court, in its reasoning, observed: "Once the demand of INR 31,45,84,219/- stood set aside, a statutory right accrued in favour of the Petitioner to receive a refund of the amount paid towards pre-deposit i.e. INR 3,14,58,422/- along with interest. The continued retention of such an amount is wholly unauthorized and offends Article 265 of the Constitution."
Highlighting the fundamental nature of pre-deposits, the Court placed reliance on Nelco Limited Vs. UoI, reiterating that amounts paid as a condition precedent for hearing an appeal do not bear the character of duty but only of a security deposit.
The Court has following directions:
"(i) The writ petition is allowed.
(ii) The impugned Order is quashed and set aside.
(iii) The application for refund to the extent of Rs.3,14,58,422/- Crores be processed expeditiously and accordingly be refunded to the petitioner in any case within a period of six weeks from the date of communication of this Order."
Ratio
When a tax demand is set aside or reduced in appeal, the appellate proceedings attain finality to the extent of the dropped demand if unappealed by the Revenue, creating an immediate statutory right for the assessee under Section 107(16) of the CGST Act to receive a proportionate refund of the pre-deposit made under Section 107(6). The retention of such funds violates Constitution of India.
Background
The petitioner, IBM India Pvt. Ltd., was initially assessed with a tax demand of Rs. 48,96,54,949/- by the Adjudicating Authority. On challenging the order under Section 107 of the Maharashtra Goods and Services Tax Act, 2017, the First Appellate Authority partly allowed the appeal, dropping 64% of the original demand (amounting to Rs. 31,45,84,219/-) and confirming a demand of Rs. 17,50,70,729/-.
Following this, the petitioner applied under Form GST RFD-01 seeking a refund of Rs. 3,14,58,422/-, representing the 10% pre-deposit paid corresponding to the dropped demand. However, the Deputy Commissioner of State Tax rejected the refund claim under Section 54 of the Maharashtra Goods and Services Tax Act, 2017 read with Rule 92(3) of the MGST Rules, 2017, relying on Circular No. 125/44/2019-GST. The authority reasoned that the proceedings had not attained finality because the petitioner expressed an intention to challenge the remaining confirmed demand before the GST Appellate Tribunal under Section 112 of the Maharashtra Goods and Services Tax Act, 2017.
Agrieved, the petitioner approached the High Court under Article 226 of the Constitution of India. Citing precedents including Brij Mohan Mangla Vs. Union of India, M/s. G. S. Industries Vs. Commissioner of CGST, Delhi West & Anr., and M/s. Bla Infrastructure Pvt. Ltd. Vs. The State of Jharkhand, Commissioner, State Goods & Services Tax & Ors., the petitioner argued that pre-deposits cannot be retained once a demand is set aside.
The High Court held that the order setting aside the demand was binding on the tax officer under Section 107(16) of the CGST Act. Although statutory interest was requested under Section 115 of the CGST Act, the petitioner graciously waived its claim for interest upon the Court's request, prompting the Court to direct the refund of the principal amount within six weeks.
Case Details:
Case No.: WRIT PETITION (L) NO. 38052 OF 2025
Neutral Citation: 2026:BHC-OS:19255-DB
Case Title: IBM India Pvt. Ltd. v. Union of India & Ors.
Appearances:
For the Petitioner(s): Mr. Mahir Chablani a/w. Mr. Prathamesh Gargate and Ms. Dimpal Jangid i/b Mr. Mahir Chablani
For the Respondent(s): Smt. Anjali Helekar, Govt. Pleader a/w. Mr. Himanshu Takke, AGP for Respondent Nos.2 & 3-State
Source: 2026 CaseBase(BOM) 4697
Similar Articles

 Breaking News


