


Customs Authorities Retain Jurisdiction to Scrutinize Third-Party Export Remittances
 Copy Link
 Share
 Save
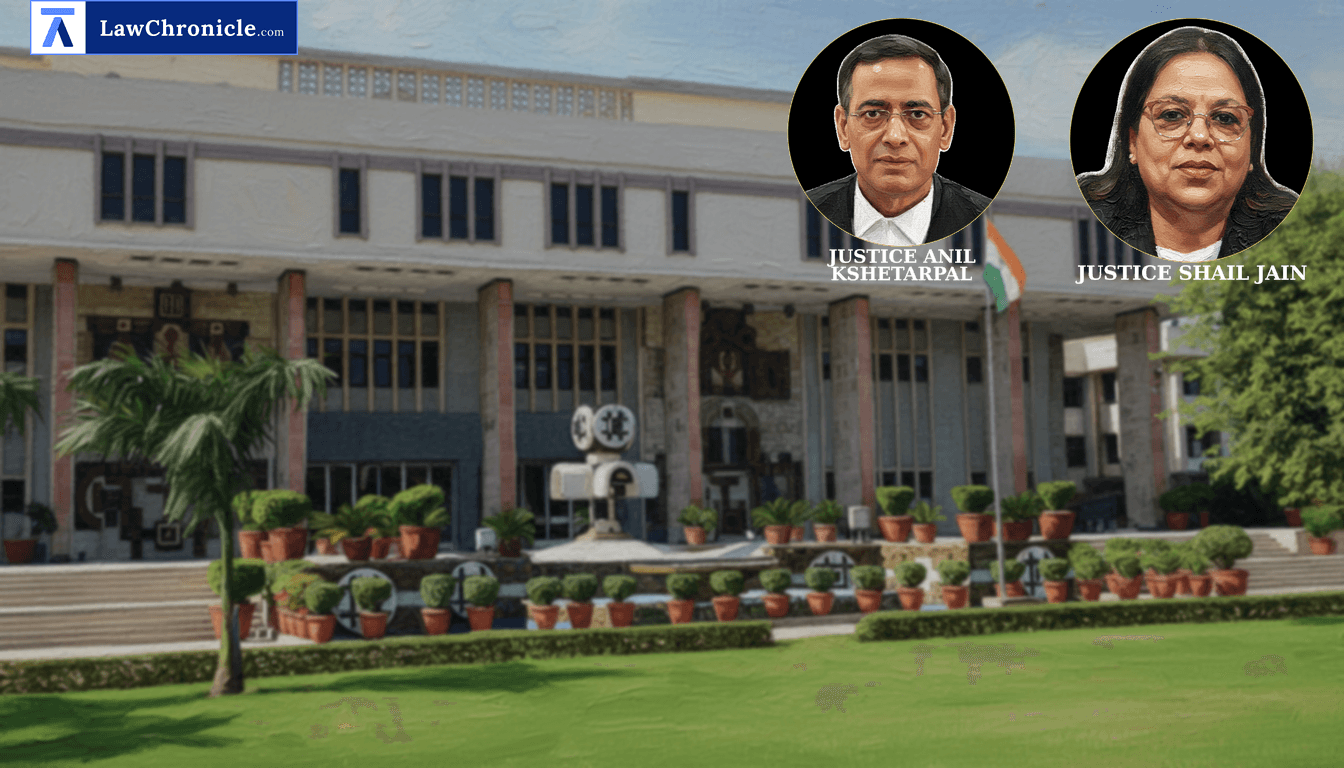
In a decisive blow to exporters seeking to shield suspicious financial trails from regulatory scrutiny, the Delhi High Court has ruled that Customs authorities possess the independent jurisdiction to examine the genuineness of third-party remittances under the Customs Act, 1962, regardless of existing foreign exchange oversight by the Reserve Bank of India.
A division bench of Justice Anil Kshetarpal and Justice Shail Jain delivered this significant judgment while setting aside a common order of the CESTAT which had previously exonerated several exporting entities accused of massive overvaluation and round-tripping of funds to fraudulently claim drawback benefits.
Key Takeaways
- Customs Jurisdiction Independent of FEMA
The court established that Customs authorities do not need a prior determination from the RBI to investigate if export remittances actually constitute genuine sale proceeds for drawback eligibility. - Substance Over Form in Financial Realizations
Merely receiving funds in a bank account does not automatically satisfy the statutory requirement of 'sale proceeds' if the financial trail indicates artificial inflation or unrelated third-party sources. - Civil Decrees Do Not Bind Non-Party Statutory Bodies
A declaratory decree obtained against a bank in a civil suit regarding the cancellation of Bank Realisation Certificates (BRCs) cannot preclude the Customs Department from conducting its own statutory enquiry if it was not a party to the suit.
Customs Enforcement Not Barred by RBI Regulatory Domain
The controversy centered on 13,008 consignments of readymade garments where the Revenue alleged the exporters inflated values by 2 to 20 times to siphon off drawback under Section 75 of the Customs Act, 1962 and benefits under Focus Product Schemes. The CESTAT had earlier held that Customs lacked jurisdiction to question third-party payments as foreign exchange regulation falls under the Foreign Exchange Management Act, 1999. Reversing this, the High Court clarified that when examining the entitlement to drawback, the authorities must verify the nexus between the money received and the goods exported.
The Court has the following directions:
"Accordingly, the present Appeals are allowed. The Final Order Nos. 59488-59509/2024 dated 25.11.2024 passed by the CESTAT are set aside, except to the extent that the penalty imposed upon Shri Nitin Gupta of M/s Oak Shipping Services Pvt. Ltd. was set aside on the ground of non-compliance with the requirements of notice, supply of documents and opportunity of hearing. The Order-in-Original dated 30.05.2023 passed by the Commissioner of Customs (Export) is restored in all other respects, but the penalty imposed upon Shri Nitin Gupta shall remain set aside."
The Court, in its reasoning, observed: "The Customs authorities are not thereby exercising the regulatory jurisdiction of the Reserve Bank of India under Foreign Exchange Management Act, 1999. They are examining the statutory entitlement to retain a benefit granted under the Customs Act, 1962. ... Receipt of money in a bank account is a fact; whether that receipt constitutes sale proceeds in respect of the exported goods is a matter which has to be determined from the surrounding circumstances and the evidence available on record."
Ratio
The High Court declared that the expression 'sale proceeds in respect of such goods' under Section 75 of the Customs Act, 1962 empowers Customs authorities to examine the source and nature of remittances to ensure a genuine nexus with exported goods. Furthermore, a declaratory judgment in a civil suit operates in personam and does not bind statutory authorities who were not impleaded in the proceedings.
Background
The Directorate General of Revenue Intelligence (DRI) investigation alleged that five exporting entities, including M/S G.D. Manglam Exim Pvt. Ltd., received over $76 million from unrelated third parties in Hong Kong and the UAE. The Revenue argued these were not genuine payments but part of a money-laundering circuit involving diamond traders. The Adjudicating Authority had confirmed recoveries for 1,650 shipping bills where BRCs were cancelled by Punjab National Bank.
While the CESTAT set aside these recoveries by relying on Razia Begum v. Sahebzadi Anwar Begum ( "AIR 1958 SC 886": 1958 CaseBase(SC) 180) regarding third-party payments and a civil court decree declaring the BRC cancellations void, the High Court found this reasoning flawed. The High Court noted that the Adjudicating Authority relied on extensive documentary evidence, including Navin Chemicals Manufacturing and Trading Co. Ltd. v. Collector of Customs ( "(1993) 4 SCC 320": 1993 CaseBase(SC) 5) and Commissioner of Customs v. Motorola India Ltd. for jurisdictional principles, and foreign customs data showing massive value disparities. The High Court distinguished the present case from Additional Director General, DRI v. Knowledge Infrastructure Systems Pvt. Ltd. and Deccan Paper Mills Co. Ltd. v. Regency Mahavir Properties Pvt. Ltd. ( "(2021) 4 SCC 786": 2020 CaseBase(SC) 1689), noting that the absence of formal re-valuation under the Customs Valuation (Determination Of Value Of Export Goods) Rules, 2007 did not prevent a finding of deliberate misdeclaration for fraudulent benefit availment. The court upheld the recovery under Section 28AAA of the Customs Act, 1962 and restored the 2023 Order-in-Original, except for a specific procedural relief granted to an individual noticee based on Kothari Filaments & Anr. v. Commissioner of Customs (Port), Kolkata & Ors. ( "(2009) 2 SCC 192": 2008 CaseBase(SC) 434).
Case Details:
Case No.: CUSAA 92/2025
Case Title: The Commissioner Of Customs (Export) V. M/S. G.D. Manglam Exim Pvt. Ltd. (Now Known As M/S. Welldone Exim Pvt. Ltd.)
Appearances:
For the Petitioner(s): Mr. Anurag Ojha, SSC along with Mr. Dipak Raj, Mr. Aryaman Singh Chouhan and Mr. Aditya Chaudhary, Advs.
For the Respondent(s): Mr. Tarun Gulati, Sr. Adv. along with Dr. G. K. Sarkar, Ms. Malabika Sarkar, Mr. Prashant Srivastav, Ms. Shruti Kulkarni and Mr. Karan Khaitan, Advs.
Source: 2026 CaseBase(DEL) 7529
Similar Articles
 Breaking News


