


Limitation Period For Income Tax Appeal Commences Only From Receipt Of Signed Order: Bombay High Court
 Copy Link
 Share
 Save
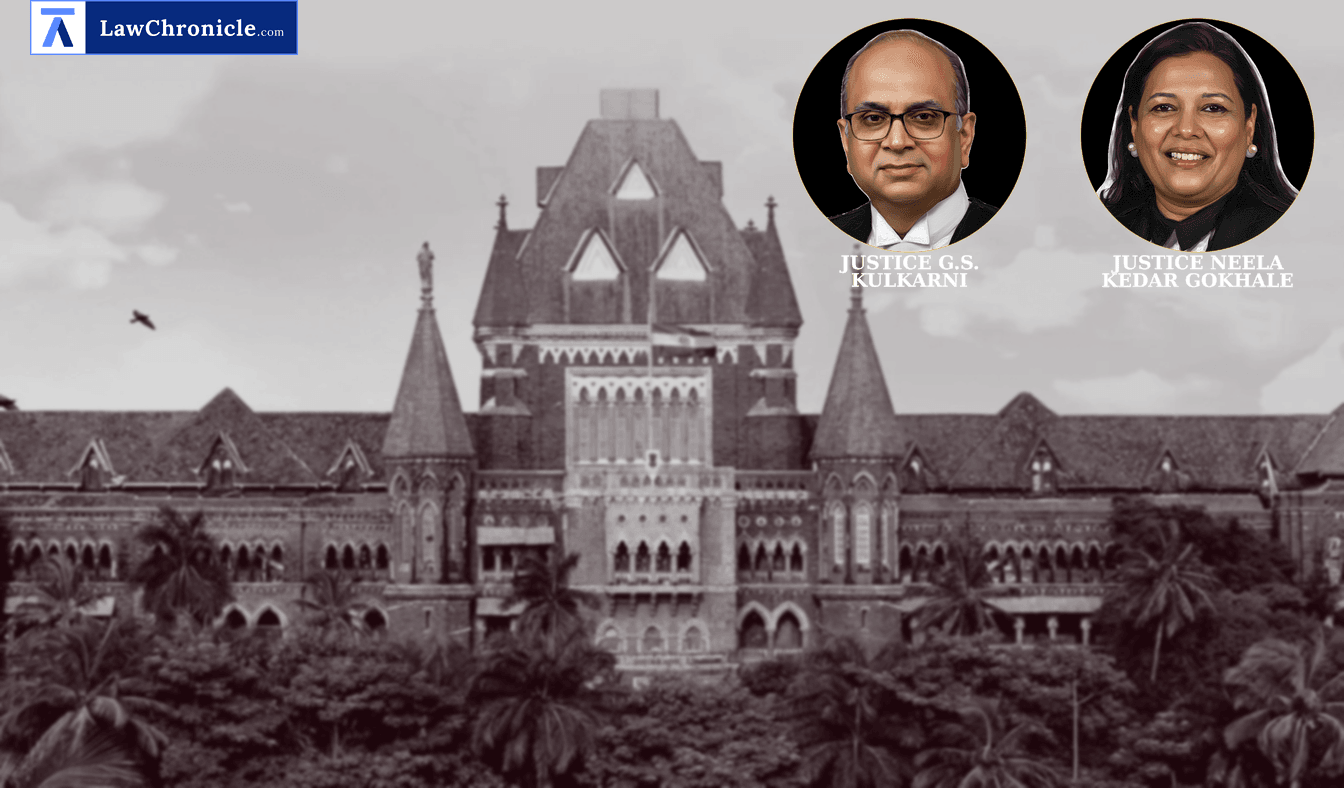
In a decisive clarification of appellate procedure, the Bombay High Court has ruled that the limitation period for filing a tax appeal begins only upon the physical receipt of a signed judgment, rejecting the revenue department's contention that mere knowledge of an oral pronouncement triggers the limitation period.
A division bench of Justice G. S. Kulkarni and Justice Dr. Neela Gokhale delivered this ruling while hearing an application for the condonation of an 88-day delay in filing an appeal against an order of the Income Tax Appellate Tribunal (ITAT).
Key Takeaways
Receipt Over Knowledge
Limitation for filing appeals under the Income Tax Act, 1961 is calculated from the date of receipt of the signed order, not from the date of its oral pronouncement in open court.
Procedural Fairness
Parties are entitled to a complete copy of the judgment to deliberate on grounds of appeal, ensuring that the right to prefer a substantive appeal is not rendered illusory.
Mandatory Communication
Under the Income-Tax (Appellate Tribunal) Rules, 1963, the Tribunal is statutorily obligated to communicate signed orders to both the assessee and the Commissioner free of cost.
Liberal Condonation
Courts should adopt a justice-oriented and liberal approach toward minor delays, provided there is no evidence of mala fide intent or gross negligence.
Limitation Commences From Receipt Of Certified Copy
The Revenue Department had vehemently opposed the condonation application, arguing that the applicant was aware of the ITAT's dismissal on the date of pronouncement and that the delay should be calculated from that date. However, the Bombay High Court scrutinizing the statutory framework of the Income Tax Act, 1961 and the Income-Tax (Appellate Tribunal) Rules, 1963, observed that the law specifically mandates the dispatch of orders to the parties.
The Bench reasoned while explaining that "The Act and the Rules themselves contemplates that the copy of the Judgment and Order pronounced by the Appellate Tribunal is sent by the Tribunal to the parties. There is no provision in the Act or in the Rules regarding applying for or obtaining a certified copy. Thus, considering the relevant ITAT Rules, we are of the clear opinion that once the Rules contemplate dispatching the copy of the Judgment and Order by the Tribunal to the Assessee and the PCIT, the limitation shall naturally commence from the day on which the same is received by the respective party. Mere knowledge of the order, by way of pronouncement is not enough to hold that day to be the first day on which the limitation commences."
The Importance of Cogent Grounds for Appeal
The Bench further noted that for an aggrieved party to effectively challenge a decision, they must have access to the full text of the findings. The Court remarked: “For the aggrieved party to deliberate and consider as to whether he wishes to assail the same and on what grounds to do so, it is necessary for the party have a complete copy of the Judgment and Order which will apprise him of the finding and reasons given by the Court/Tribunal, on the basis of which the order is passed.”
Ratio
In the absence of a provision for applying for certified copies, and where the statute mandates the Tribunal to communicate orders to parties, the limitation period for filing an appeal under Section 260A of the Income Tax Act, 1961 begins from the date of actual receipt of the communicated order, rather than the date of pronouncement.
Background
The Applicant, GS Strategic Investments Limited, sought to appeal an ITAT order dated October 22, 2024, which had remanded the issue of long-term capital gains tax exemption back to the Assessing Officer. Although the order was pronounced in October 2024, the signed copy was only received by the Applicant on February 27, 2025. Following internal deliberations and a shift in strategy from filing a miscellaneous application under Section 254(2) to filing a substantive appeal, the Appeal was lodged on September 23, 2025.
The Court relied on the principles established in Maniben Devraj Shah v. Municipal Corporation of Brihan Mumbai ( "Civil Appeal No. 2970-2971/2012 dated 9th April 2012": 2012 CaseBase(SC) 836), noting that while a liberal approach is required under Section 5 of the Limitation Act, 1963, the court must balance it against the rights acquired by the successful litigant. Finding that the applicant provided a stage-wise explanation and showed no negligence, the Bombay High Court condoned the 88-day delay.
Case Details:
Case No.: Interim Application (L) No. 30896 of 2026 In Income Tax Appeal (L) No. 30455 of 2025
Case Title: GS Strategic Investments Limited v. Assistant Commissioner of Income Tax
Appearances:
For the Petitioner(s): Mr. Madhur Agrawal a/w Punit J. Shah i/b Mint & Confrers
For the Respondent(s): Mr. Subir Kumar a/w Ashita Aggarwal
Source: 2026 CaseBase(BOM) 7128
Similar Articles

 Breaking News


