State Authorities Empowered To Seize Tax-Evading Vehicles: Karnataka HC
 Copy Link
 Share
 Save
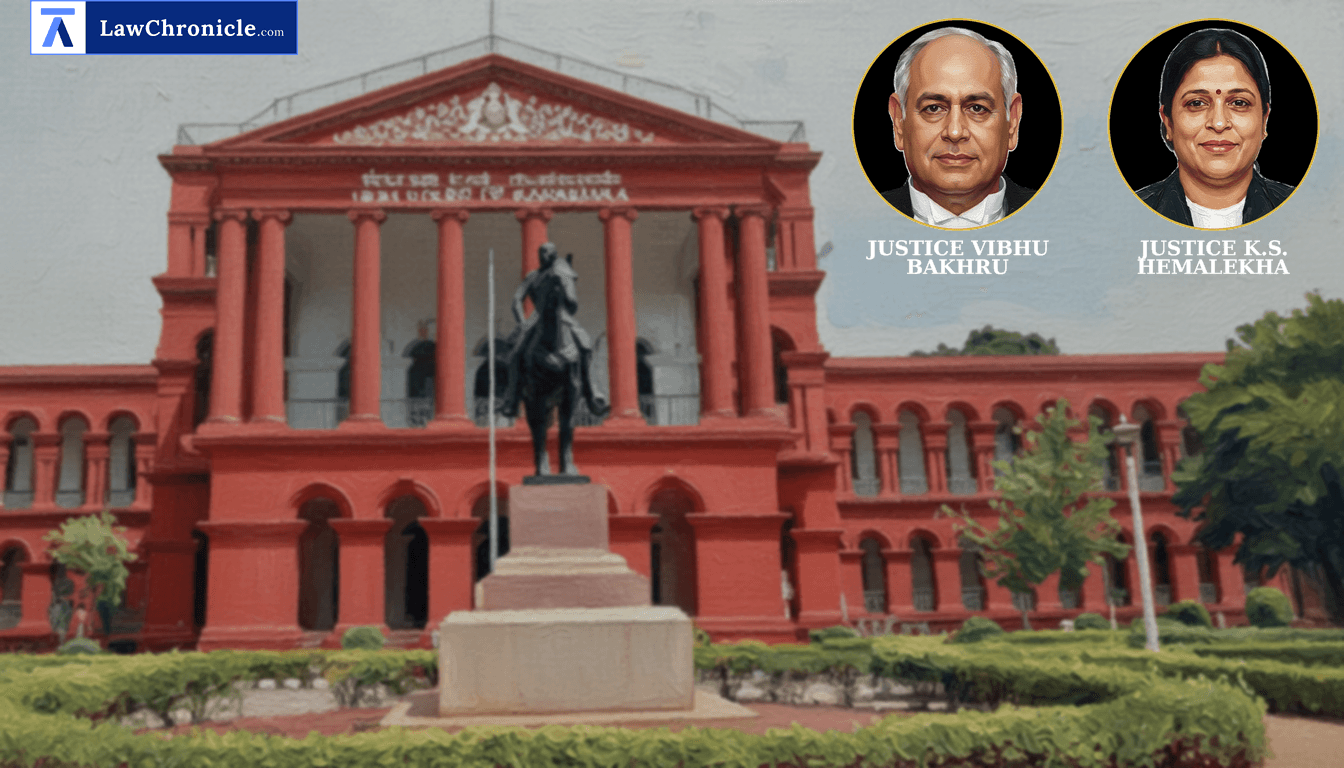
In a major crackdown on tax evasion involving high-end luxury automobiles, the High Court of Karnataka has upheld the statutory powers of transport authorities to seize vehicles registered using forged documentation and understated values.
A Division Bench comprising Chief Justice Vibhu Bakhru and Justice K.S. Hemalekha allowed an intra-court writ appeal filed under Section 4 of the Karnataka High Court Act by the State of Karnataka against a Single Judge order. The Single Judge had previously quashed an investigation report, set aside an order cancelling the vehicle's registration certificate, and directed the release of a high-end luxury car to the respondent.
Jurisdiction of Transport Officers to Seize Tax-Evading Vehicles
The High Court scrutinised the statutory authority under Section 11A of the Karnataka Motor Vehicles Taxation Act, 1957 read with Rule 27-A of the Karnataka Motor Vehicles Taxation Rules, 1957. Reversing the Single Judge's finding that the inspecting officer lacked jurisdiction, the division bench clarified that officers not below the rank of Inspector of Motor Vehicles possess explicit statutory authority to execute enforcement tasks and seize vehicles where tax evasion is detected.
The Court, in its reasoning, observed: "In the aforesaid view, it is clear that Sri Ranjith N, being an official not below the rank of an Inspector of Motor Vehicles had the necessary authority for taking steps or to undertake the enforcement tasks. These would also include seizure of vehicles where it was found that there was evasion of tax. There is merit in the contention that the said memorandum does not include any powers other than those which were statutorily contemplated under Section 11A of the KMVT Act and Rule 27A of the KMVT Rules. The conclusion of the learned Single Judge that the memorandum conferred limited powers to submit a report and not to take any other action under the relevant statute, in our view, is erroneous."
Validity of Cancellation of Registration
Addressing the cancellation of registration by the transport authority under Section 55 of the Motor Vehicles Act, 1988, the bench rejected the argument that the order was passed to overreach court proceedings. The Court held that in the absence of a stay order, statutory authorities remain fully competent to exercise their statutory functions upon discovering that registration was secured through fabricated sale certificates and tax invoices.
Key Takeaways
- Statutory Enforcement Power: Motor Vehicle Inspectors possess full legal authority to seize and detain vehicles suspected of tax evasion under motor vehicle taxation laws.
- Fraud Vitiates Registration: Registration certificates obtained through misrepresentation of vehicle specifications or forged tax invoices are subject to cancellation under Section 55 of the Motor Vehicles Act, 1988.
- Absence of Stay Orders: Statutory authorities are not barred from exercising independent statutory duties simply due to the pendency of a writ petition, provided no express stay order is operating.
Ratio
An officer not below the rank of Inspector of Motor Vehicles holds statutory power under Section 11A of the Karnataka Motor Vehicles Taxation Act, 1957 and Rule 27-A of the Karnataka Motor Vehicles Taxation Rules, 1957 to seize and detain motor vehicles where tax evasion or fraudulent registration is detected, and transport authorities may validly exercise powers under Section 55 of the Motor Vehicles Act, 1988 to cancel registrations obtained via forged documents during pending proceedings absent an express judicial stay.
Background:
The dispute arose regarding a Mercedes-Benz AMG G63 originally purchased in 2016 for approximately Rs 1.96 Crore. Following a series of transfers, criminal complaints under the Indian Penal Code,1860, and recovery proceedings before the Debt Recovery Tribunal, the vehicle was fraudulently registered in Karnataka as a lower-end "BENZ GLA 200 CDI" valued at Rs 32.15 Lakhs. This misrepresentation drastically reduced the lifetime tax payable from Rs 78.31 Lakhs to Rs 12.69 Lakhs.
Upon inspection by a Special Checking Squad on 15.06.2025, the disparity in chassis numbers, engine specifications, and fabricated sale documents came to light, leading to seizure under the Karnataka Motor Vehicles Taxation Act, 1957. The respondent filed a writ petition seeking release of the vehicle and quashing of the report, which was initially allowed by a Single Judge. Setting aside the Single Judge's directive, the division bench allowed the State's appeal and upheld the administrative actions.
Case Details:
Case No.: Writ Appeal No. 1203 of 2026 (MV)
Case Title: The State of Karnataka and Others v. Neeraj Kumar Sharma
Appearances:
For the Petitioner(s): Sri K.S. Harish, Principal Government Advocate
For the Respondent(s): Sri H. Pavan Chandra Shetty, Advocate
Source: 2026 CaseBase(KAR) 4894
Similar Articles
 Breaking News