


Writ Jurisdiction Cannot Be Invoked For Contractual Disputes Over Pre-closure Charges: Kerala HC
 Copy Link
 Share
 Save
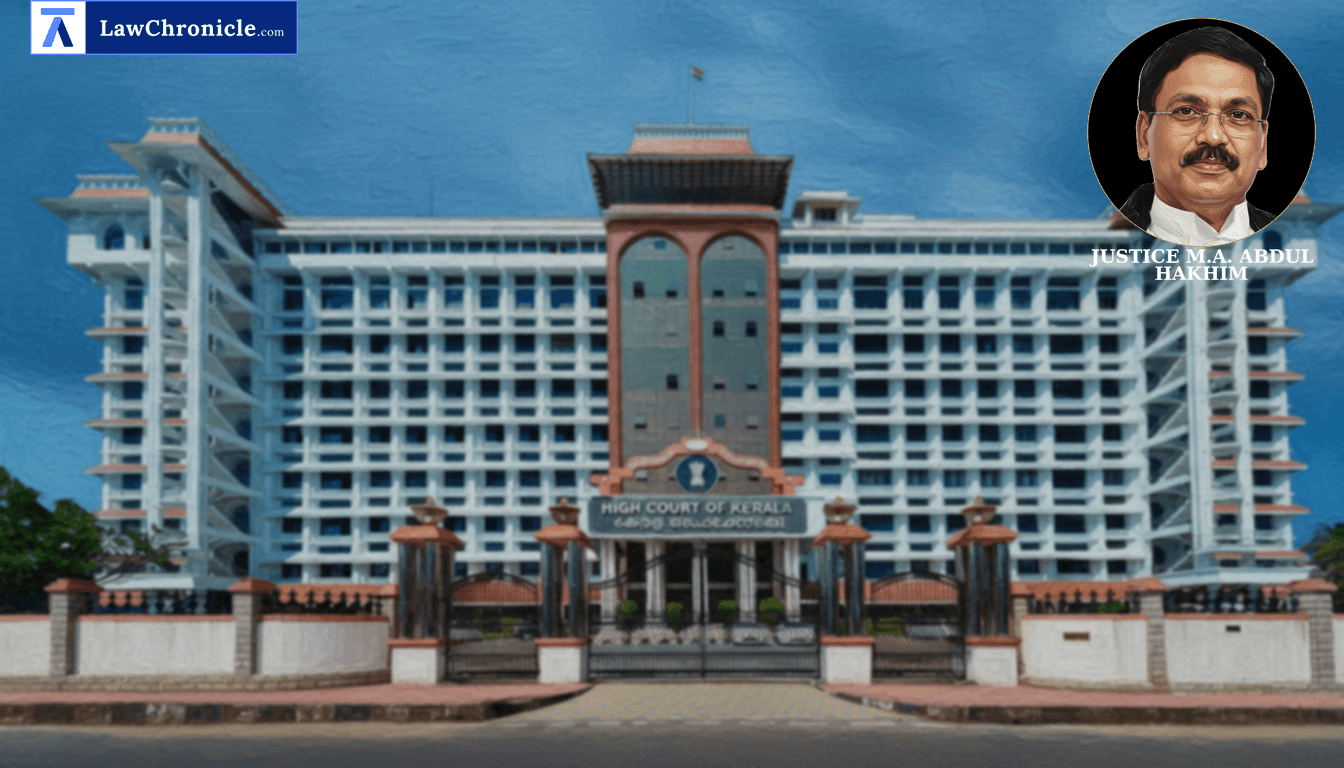
The Kerala High Court has slammed the door on litigants seeking to bypass civil courts in contractual disputes with financial corporations, ruling that the interpretation of loan pre-closure terms constitutes an adjudication of civil rights unsuitable for writ jurisdiction. In a significant clarification of the boundaries of judicial review, the Court held that even when a state financial body is involved, disputes stemming from the voidability or enforceability of specific contract clauses must be resolved through traditional civil suits rather than Article 226 petitions.
Justice M.A. Abdul Hakhim presided over the matter, where a private limited company challenged the deduction of over ₹8.47 lakhs as foreclosure premium by the Kerala Financial Corporation. The petitioner had sought a declaration that such charges were arbitrary and illegal, primarily arguing that the terms were vague and violated Section 29 of the Indian Contract Act, 1872.
Key Takeaways
Contractual Primacy Over Writ
Disputes arising purely from the interpretation of loan agreements and financial sanction letters are civil in nature and do not automatically qualify for constitutional remedies.
Limited Scope of Judicial Review
While state authorities are subject to Constitution of India, the Court will not interfere in matters requiring detailed factual adjudication of contractual obligations or the validity of internal policies.
Exhaustion of Alternative Remedies
Borrowers challenging 'uncertain' or 'arbitrary' foreclosure charges must approach Civil Courts to establish evidence regarding the communication of rules and policies during the loan currency.
Court Rejects Adjudication of Civil Rights via Writ
The Court observed that the crux of the dispute lay in whether the pre-closure charges were applicable as per the specific letters of sanction and internal rules. The petitioner argued that the 'Rules of the Corporation' mentioned in the contract were never disclosed and that a produced policy extract was not the same as the 'Rules' cited in the agreement.
The Court, in its reasoning, observed: "The question whether the Respondent Nos.1 & 2 are entitled to demand and deduct pre-closure charges from the Petitioner is to be considered in terms of the contract executed by the Petitioner and Respondent Nos.1 & 2. It requires the interpretation of various clauses provided in the contract between the Petitioner and the Respondents... Since the adjudication includes civil rights of the parties arising out of the contract, it is not desirable for this Court to adjudicate it in a Writ Petition filed under Article 226 of the Constitution of India."
While acknowledging the precedent in ABL International Ltd. and Another v. Export Credit Guarantee Corporation of India Ltd. and Others ( "(2004) 3 SCC 553": 2003 CaseBase(SC) 82), which allows interference in contractual matters in 'appropriate cases', the Court distinguished the present facts. It noted that determining the applicability of a 2% foreclosure premium required examining the voidability and enforceability of terms, a task best suited for a civil forum.
The Court has following directions:
"Accordingly, this Writ Petition is dismissed giving liberty to the Petitioner to approach the Civil Court claiming the pre-closure premium and leaving open all the contentions of the Petitioner and further making it clear that, in the event of the Petitioner filing a Civil Suit, the Civil Court shall dispose of the same untrammelled by the observations contained in this Judgment."
Ratio
When a dispute involves the interpretation of specific contractual clauses, the voidability of terms due to uncertainty, and the adjudication of civil rights arising from a loan agreement between a borrower and a state financial corporation, the High Court shall not exercise its extraordinary jurisdiction under Article 226 of the Constitution of India. Such matters are to be relegated to the competent Civil Court for a full trial on facts and law.
Background
The petitioner, Pukkattupady Hotels and Resorts (P) Ltd., had availed two term loans totaling ₹5.35 crores from the Kerala Financial Corporation (KFC). To optimize interest costs, the petitioner settled these loans through prepayments after securing takeover financing from HDFC Bank. Upon closure, KFC deducted ₹8,47,712/- as pre-closure charges.
The petitioner moved the High Court contending that the foreclosure terms were void under the Indian Contract Act, 1872 for being uncertain and that the specific 'Rules' governing these charges were never shared. KFC countered by relying on Divyaram Medical and Research Institute Pvt. Ltd. v. Kerala Financial Corporation and Another, arguing that the matter was purely contractual and the writ was not maintainable. The Court upheld this preliminary objection, noting that determining if a policy document (Ext.R1(a)) qualified as 'Rules' under the contract required a degree of factual scrutiny inappropriate for summary writ proceedings.
Case Details:
Case No.: WP(C) NO. 14819 OF 2026
Neutral Citation: 2026:KER:68633
Case Title: Pukkattupady Hotels And Resorts (P) Ltd. V. Kerala Financial Corporation And Others
Appearances:
For the Petitioner(s): Sri.S.Vinod Bhat, Kum.Anagha Lakshmy Raman, Smt.V.Namitha, Smt.Gitanjali Sadan Pillai
For the Respondent(s): Shri.M.R.Venugopal, Sc, Kfc; Smt.Dhanya P.Ashokan (Sr.); Sri.S. Muhammad Alikhan; Smt.Gayathri Venugopal; Smt.A. A. Akhila Sree Parvathy; Shri.G.Rajan Potayil
Source: 2026 CaseBase(KER) 20072
Similar Articles
 Breaking News


